Valuation · EV/EBITDA model
Is TransDigm (TDG) stock undervalued?
On November 15, 2026, with the shares at $1,217.28, a quick EV/EBITDA model by Brief Equity valued TransDigm at about $2,263 for fiscal 2029, about 86% above the price. TransDigm looks undervalued on that model if the 20% return management looks for before buying back stock holds at today's price, and the interest rate on its debt stops rising.
By The Brief Equity Team · Model dated · Published
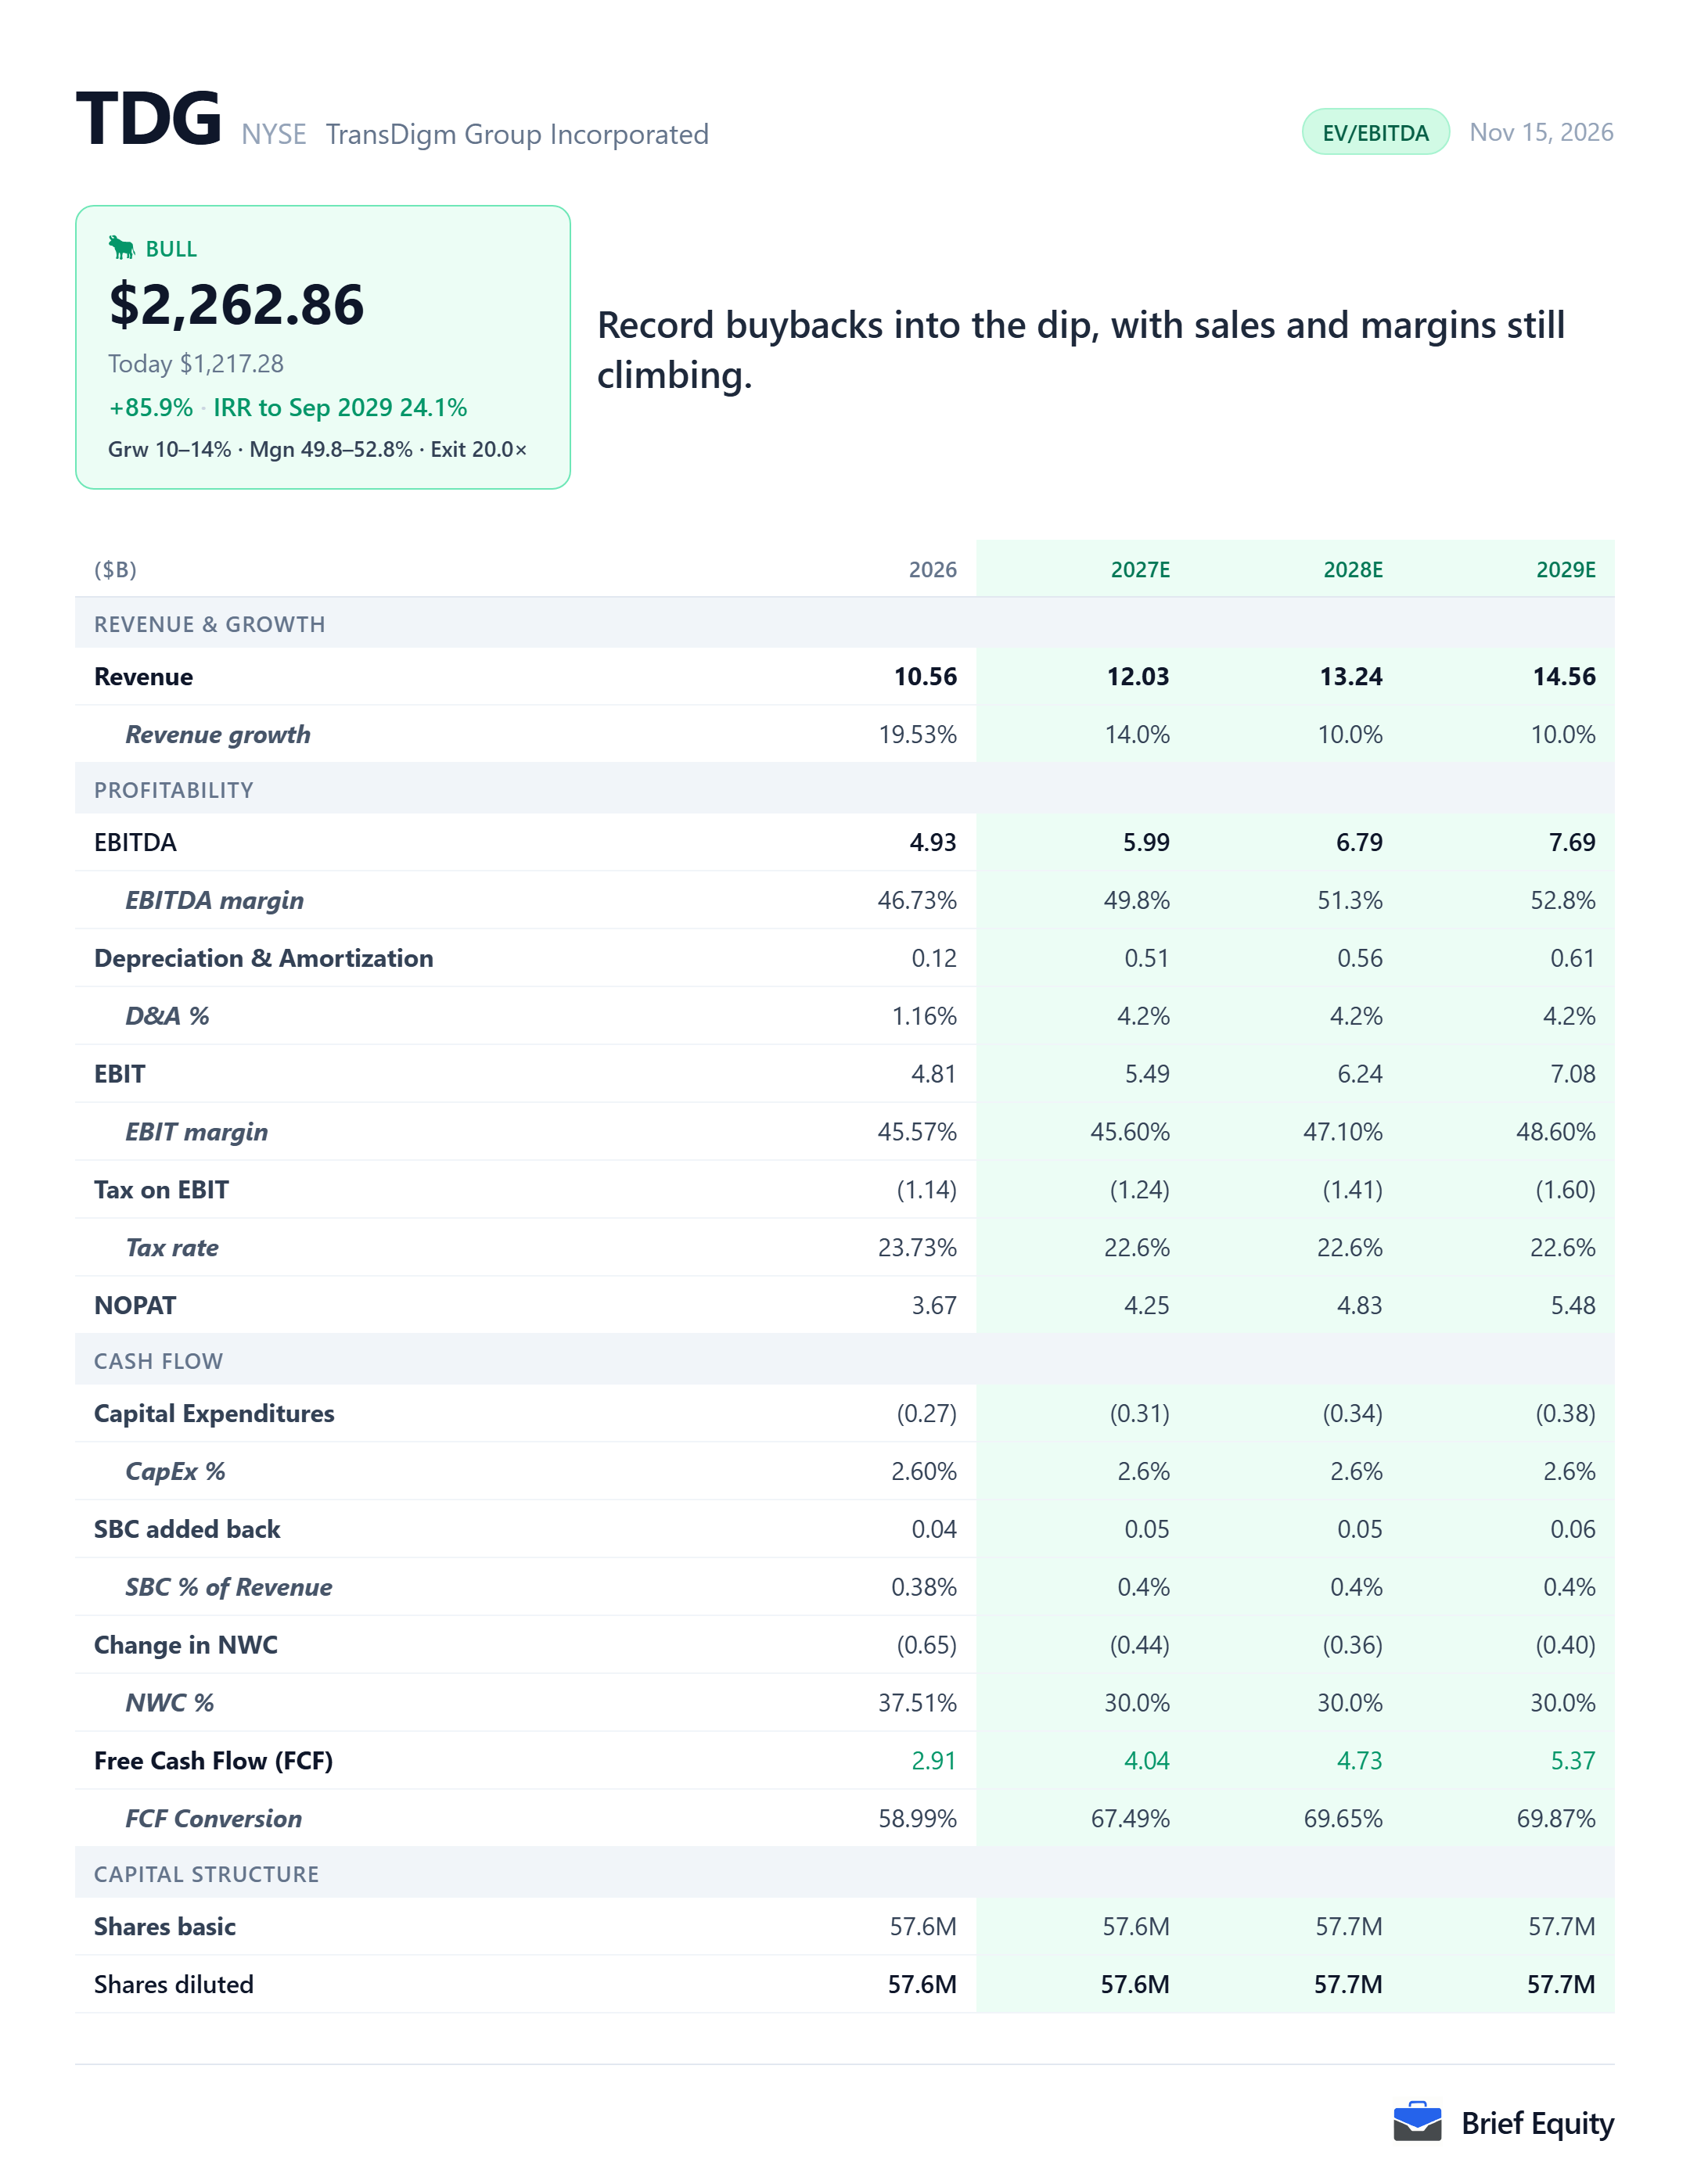
The model's assumptions for TransDigm
TransDigm's fiscal year ends on September 30, and the last year it has reported in full is fiscal 2026. The model runs three years, to fiscal 2029, and values the company on a multiple of its fiscal 2029 EBITDA. Every figure below is the model's own, except the analyst consensus row.
| 2027 | 2028 | 2029 | |
|---|---|---|---|
| Revenue, model | 12.03 | 13.24 | 14.56 |
| Revenue growth, model | 14.0% | 10.0% | 10.0% |
| EBITDA, model | 5.99 | 6.79 | 7.69 |
| EBITDA margin, model | 49.8% | 51.3% | 52.8% |
| Revenue, analyst consensus | 12.03 | 12.92 | 13.85 |
Why TransDigm looks undervalued
TransDigm bought back a record $2.75 billion of its own stock in fiscal 2026, at an average price of $1,187, and its chief executive said the company buys more aggressively when it sees a return of about 20% or better. At $1,217.28, TransDigm looks undervalued if that return holds from about today's price.
“And when we see something like a 20% IRR or better, we're likely to step out and be more aggressive on the share repurchases.”
Michael Lisman, Chief Executive Officer, TransDigm fourth-quarter fiscal 2026 earnings call, November 10, 2026
TransDigm spent $943 million of that in the fourth quarter, at an average of $1,150 a share, when its chief executive said it used a dip in the share price to buy. Paying down debt comes last in the company's order of priorities, with about $35 billion of gross debt and net debt of 5.9 times EBITDA at the end of fiscal 2026.
“Consistent with our long-term focus, we took advantage of the air pocket's effect on our share price to repurchase approximately $940 million of TransDigm stock in the quarter, bringing fiscal 2026 total repurchases to $2.75 billion.”
Michael Lisman, Chief Executive Officer, TransDigm fourth-quarter fiscal 2026 earnings call, November 10, 2026
For TransDigm, the Brief Equity model is a quick one. It has revenue growing 14% in fiscal 2027, the midpoint of the company's own guidance, then 10% a year. After fiscal 2027, its EBITDA margin rises 1.5 points a year, the top of the yearly improvement the chief executive said the businesses TransDigm already owns deliver. At 20 times fiscal 2029 EBITDA, the model values TransDigm at about $2,263 a share, about 86% above the price of $1,217.28.
This view of TransDigm needs the interest rate on its debt to stop rising: the company expects a weighted average rate of about 6.5% in fiscal 2027, against 6.1%.
What has to be true, and what would break it
The view that TransDigm looks undervalued at $1,217.28 rests on its buyback return holding and on the cost of its debt.
What has to be true
- Revenue grows about 14% in fiscal 2027, the midpoint of TransDigm's guidance, then 10% a year.
- After fiscal 2027, the EBITDA margin rises 1.5 points a year, the top of the range TransDigm's chief executive gave for the businesses it already owns.
- The weighted average interest rate on TransDigm's debt stops rising after the 6.5% expected for fiscal 2027.
What would break it
- The interest rate on about $35 billion of gross debt keeps climbing.
- Margin improvement comes in below the 1.5 points a year the model assumes.
The parts of TransDigm's business
TransDigm reports its revenue in three segments. In fiscal 2026, Power & Control was more than half of the revenue and brought most of the year's revenue growth.
| Share of revenue | Share of revenue growth | |
|---|---|---|
| Power & Control | 54.7% | 70.3% |
| Airframe | 43.6% | 28.4% |
| Non-aviation | 1.7% | 1.2% |
TransDigm beside its peers
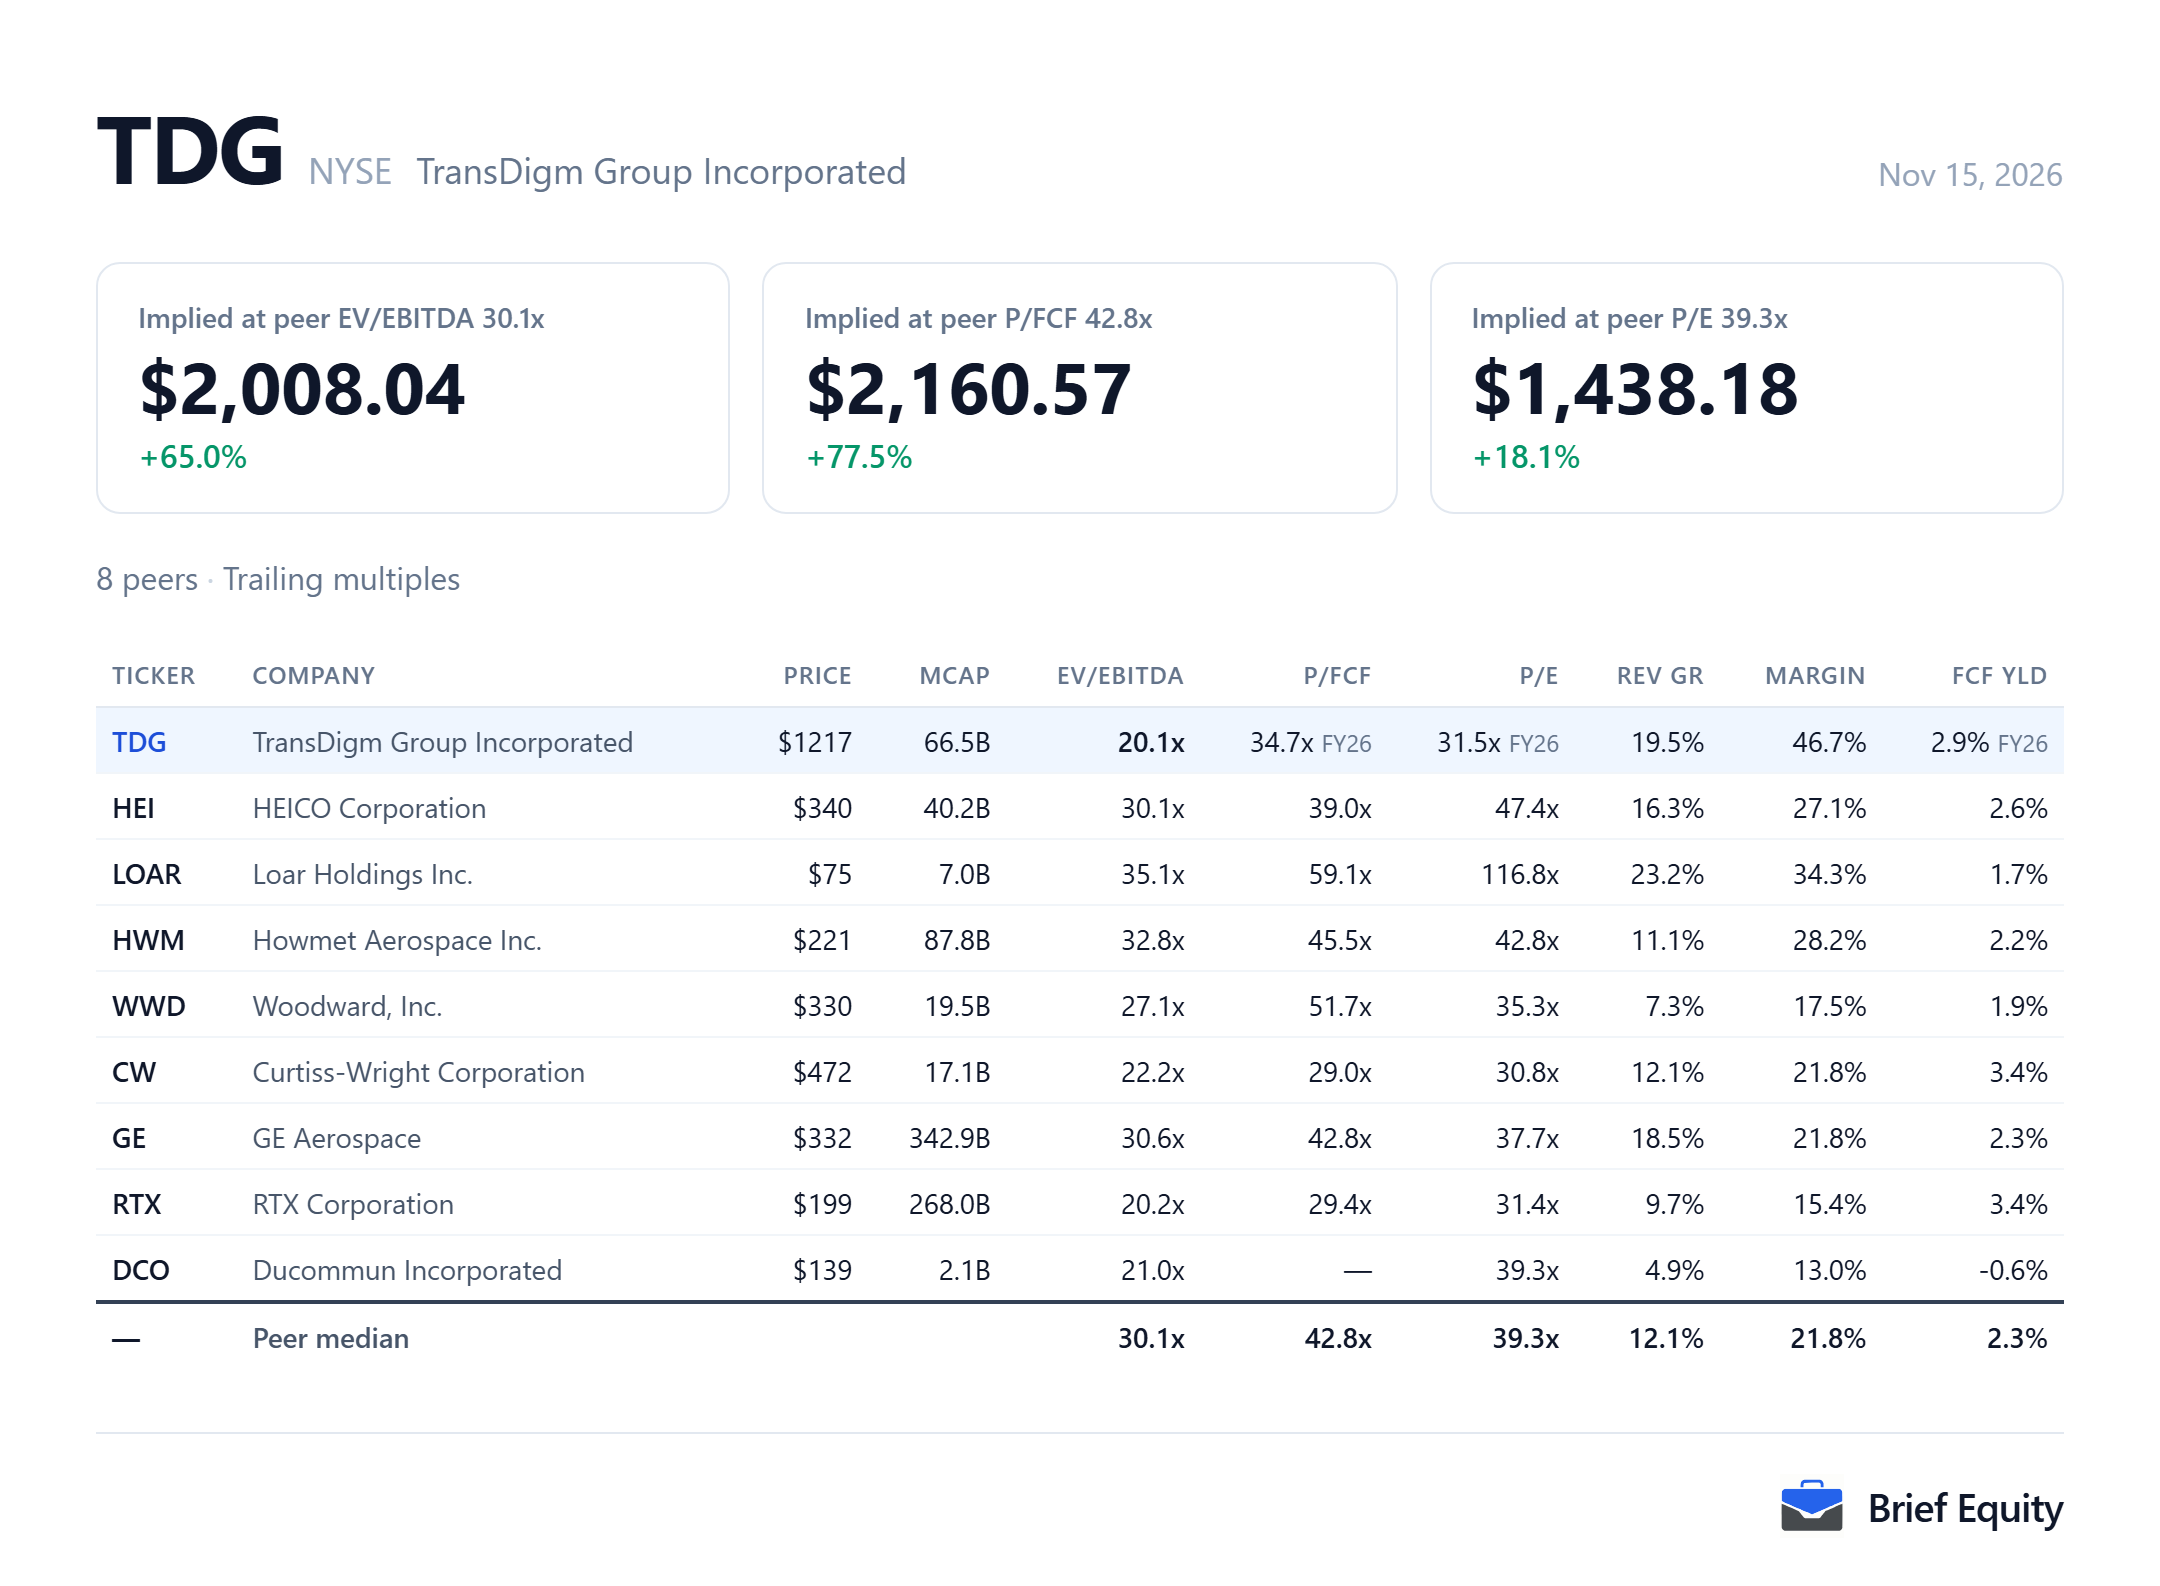
TransDigm is compared here with eight companies chosen for this post: makers of proprietary aircraft parts and components, and the engine and defense suppliers that sell into the same aftermarket and the same programs.
- HEI: Proprietary aftermarket parts, the closest business to TransDigm's
- LOAR: Proprietary aircraft components, run on a similar model
- HWM: Engine and structural parts
- WWD: Aircraft controls, against TransDigm's Airframe segment
- CW: Defense components, against TransDigm's defense sales
- GE: Engine aftermarket and spare parts
- RTX: Collins Aerospace, aircraft components
- DCO: A smaller aerostructures and components supplier
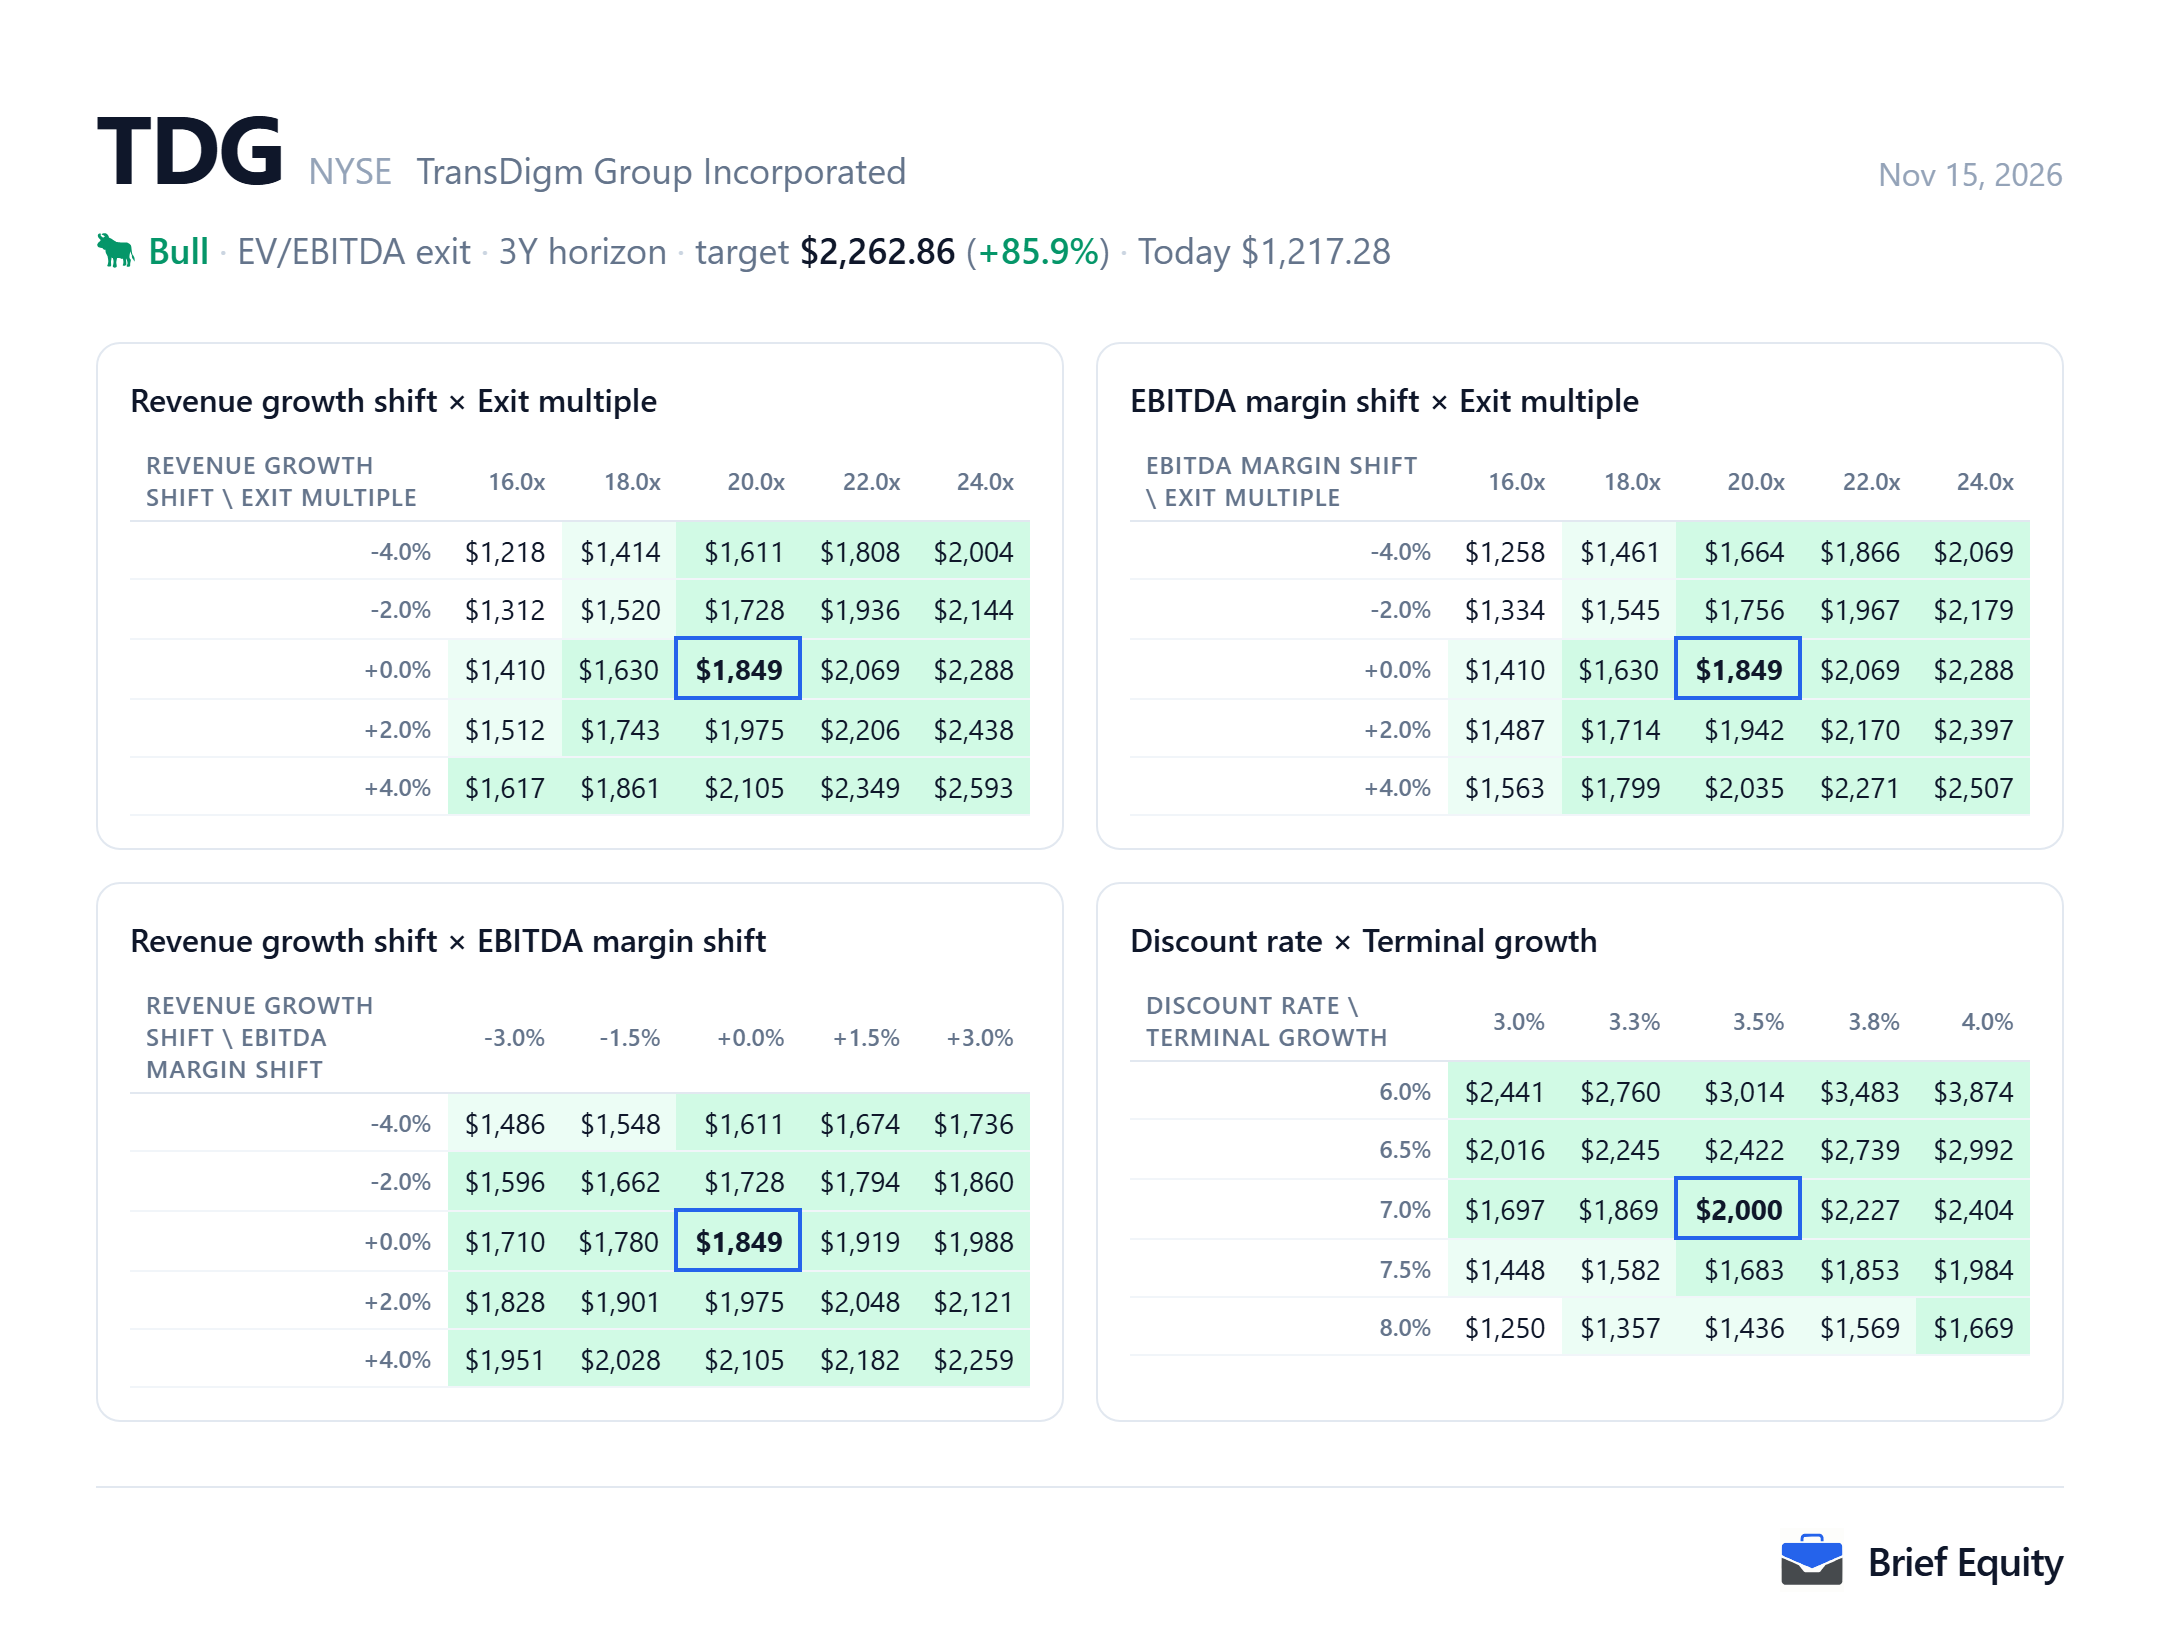
How the estimate moves with its assumptions
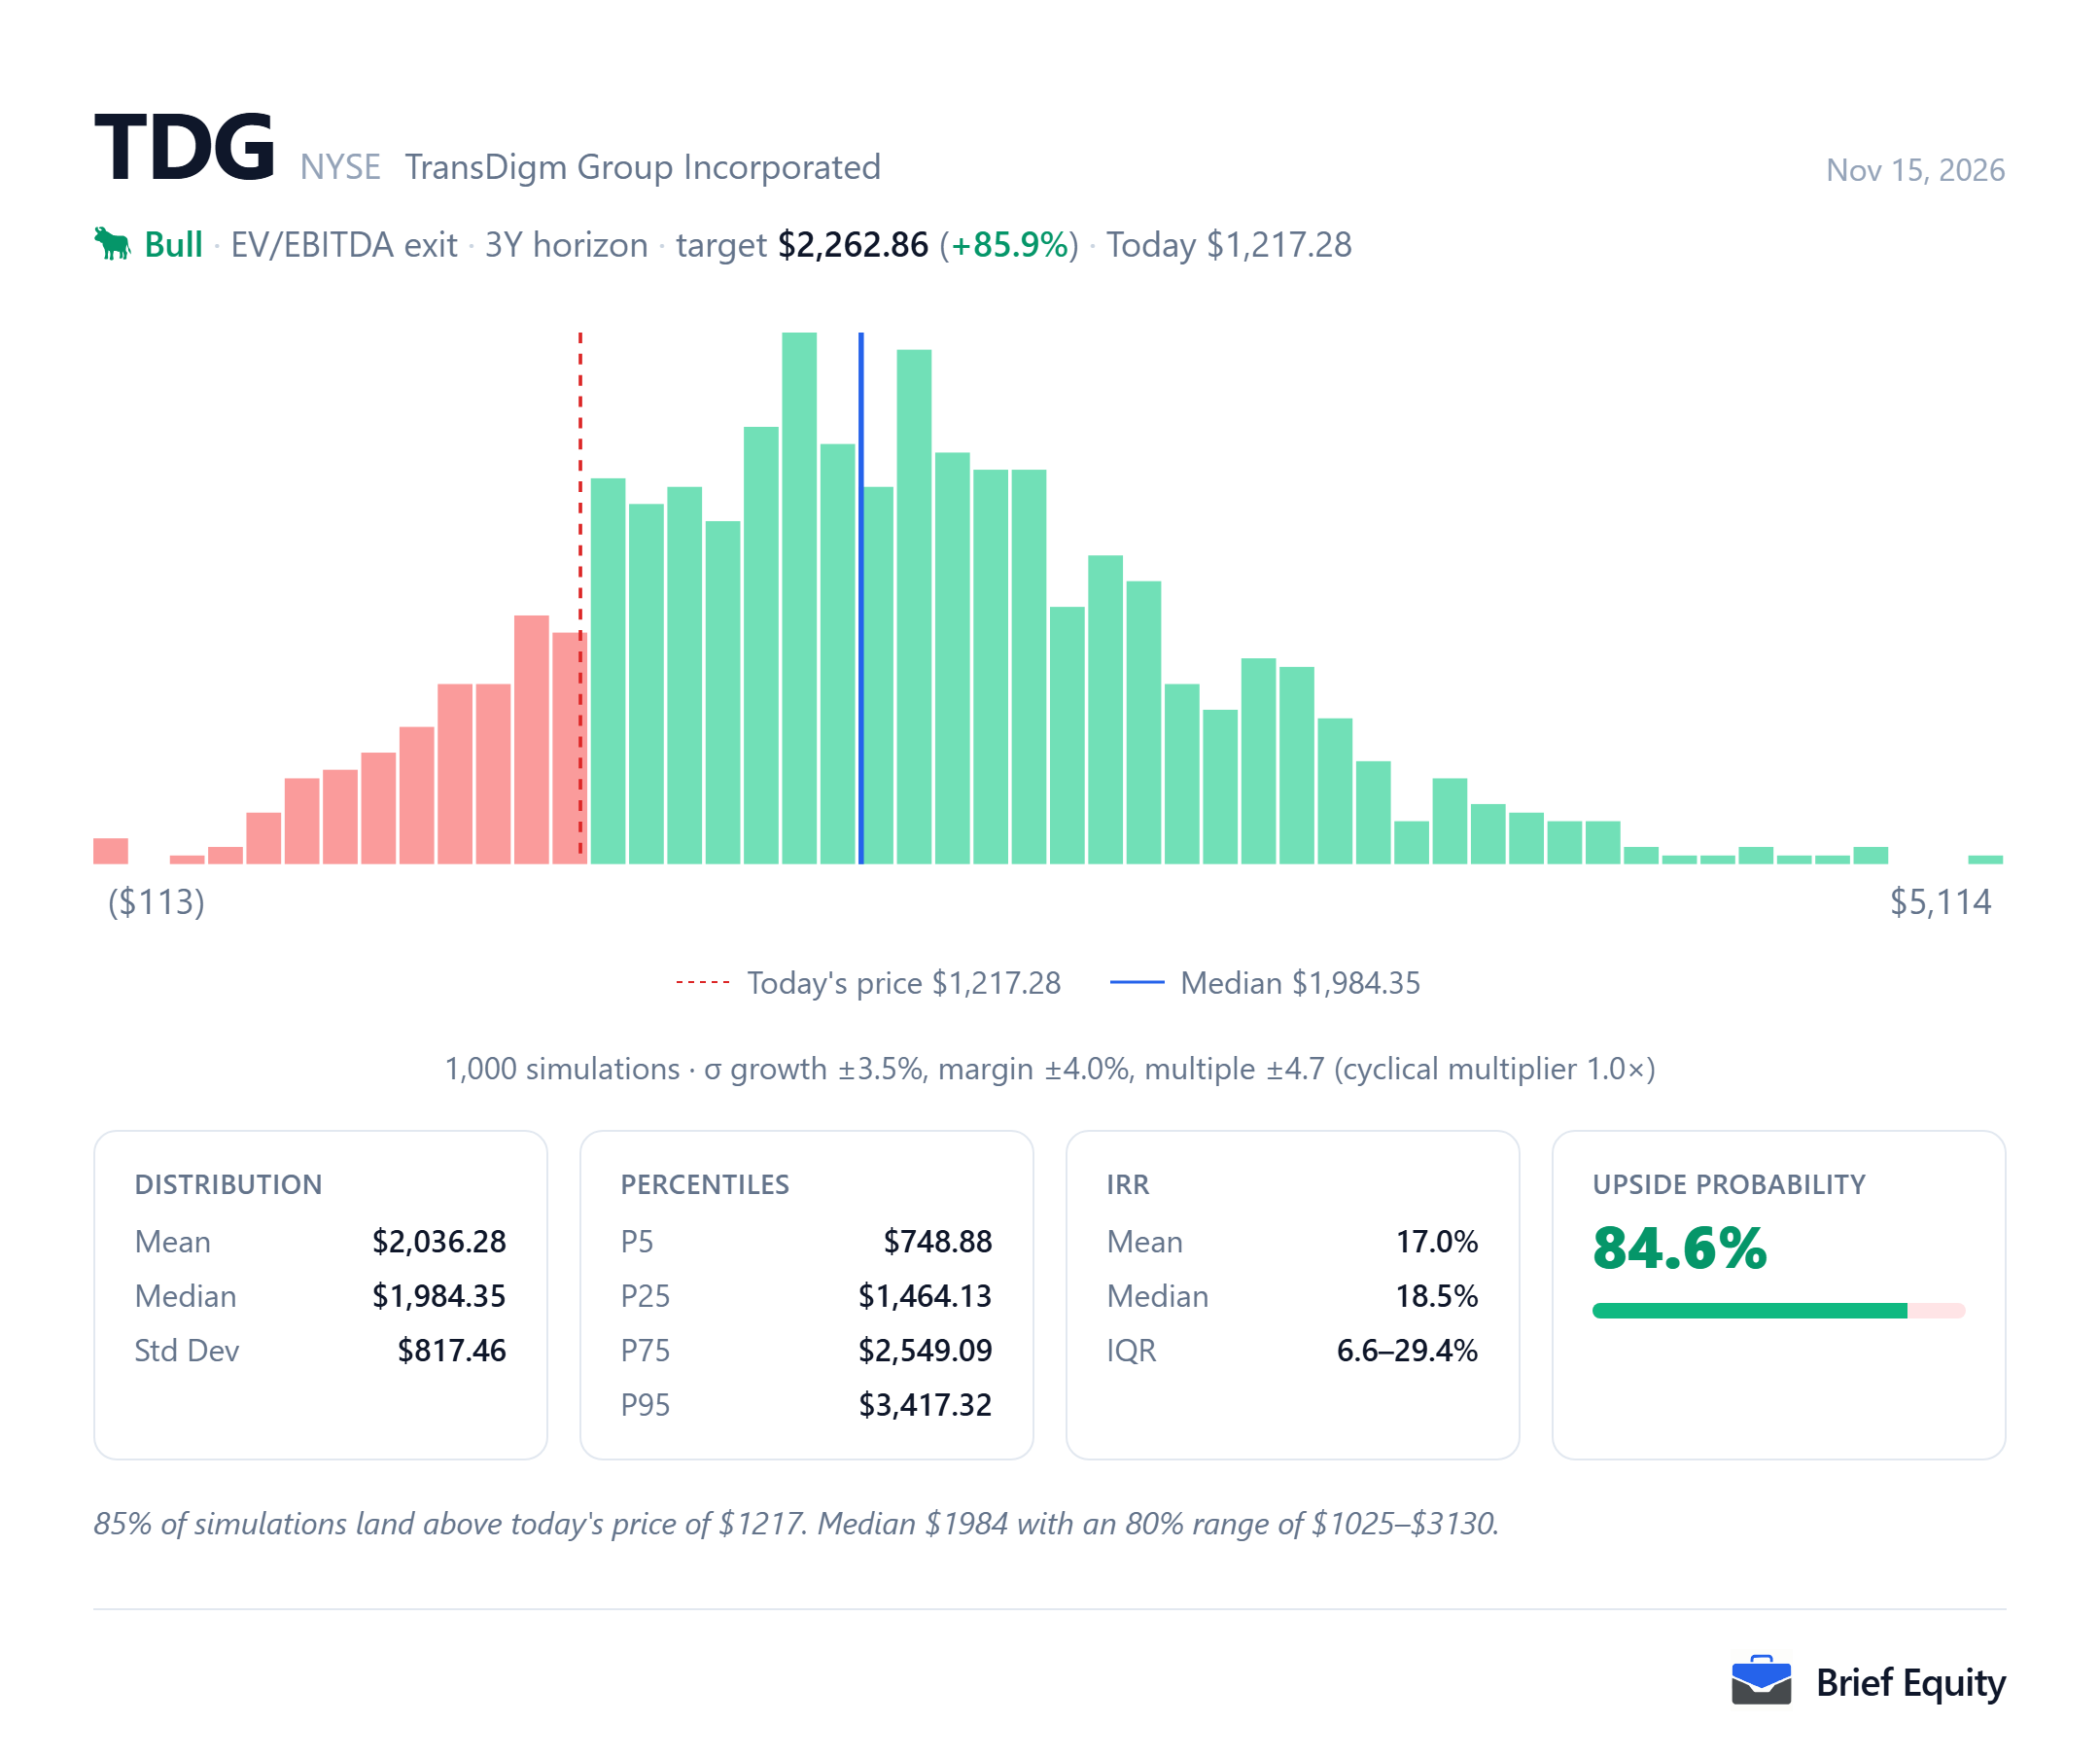
The two TransDigm cards below test the estimate: the sensitivity grids move two assumptions at a time, and the Monte Carlo card reruns the model many times with growth, margin and the exit multiple drawn at random.
Questions about TransDigm
These questions about TransDigm (TDG) are answered from the documents listed under Sources.
- How much of TransDigm's sales come from proprietary products and the aftermarket?
- TransDigm estimates that approximately 90% of its net sales in fiscal 2026 came from proprietary products and approximately 55% from the aftermarket, according to its annual report for that year.
- When did TransDigm acquire Prince & Izant?
- TransDigm completed the acquisition of 99% of Prince & Izant on September 28, 2026, for approximately $1,058 million in cash, net of cash acquired, according to its annual report for fiscal 2026.
- How much does TransDigm sell directly to the U.S. government?
- On its call of November 10, 2026, TransDigm said its direct sales to the U.S. government are historically approximately 6% of total sales.
Sources
The quotations and facts about TransDigm (TDG) on this page rest on the documents below.
- TransDigm fourth-quarter and fiscal 2026 results release, November 10, 2026
- TransDigm fourth-quarter fiscal 2026 earnings call, November 10, 2026
- TransDigm annual report on Form 10-K for fiscal 2026, November 10, 2026
About this page
Brief Equity and its team hold no position in TransDigm (TDG) as of November 15, 2026.
This page is research, not investment advice. It describes one model and the assumptions behind it, and market data is delayed. Read how these models are built and our editorial policy.
Related guides: EV/EBITDA explained, How to read a 10-K (SEC filing), What is enterprise value (EV).