Valuation · EV/EBITDA model
Is Tesla (TSLA) stock undervalued?
Brief Equity's quick EV/EBITDA model of Tesla, dated October 23, 2026, puts the shares at about $2,075 for 2030, against a price of $374.58 that day. On those assumptions Tesla looks cheap, with a return of about 454%. The model is deliberately speculative, and it rests on one condition: that Tesla reaches the operational targets of its chief executive's 2025 performance award by 2030.
By The Brief Equity Team · Model dated · Published
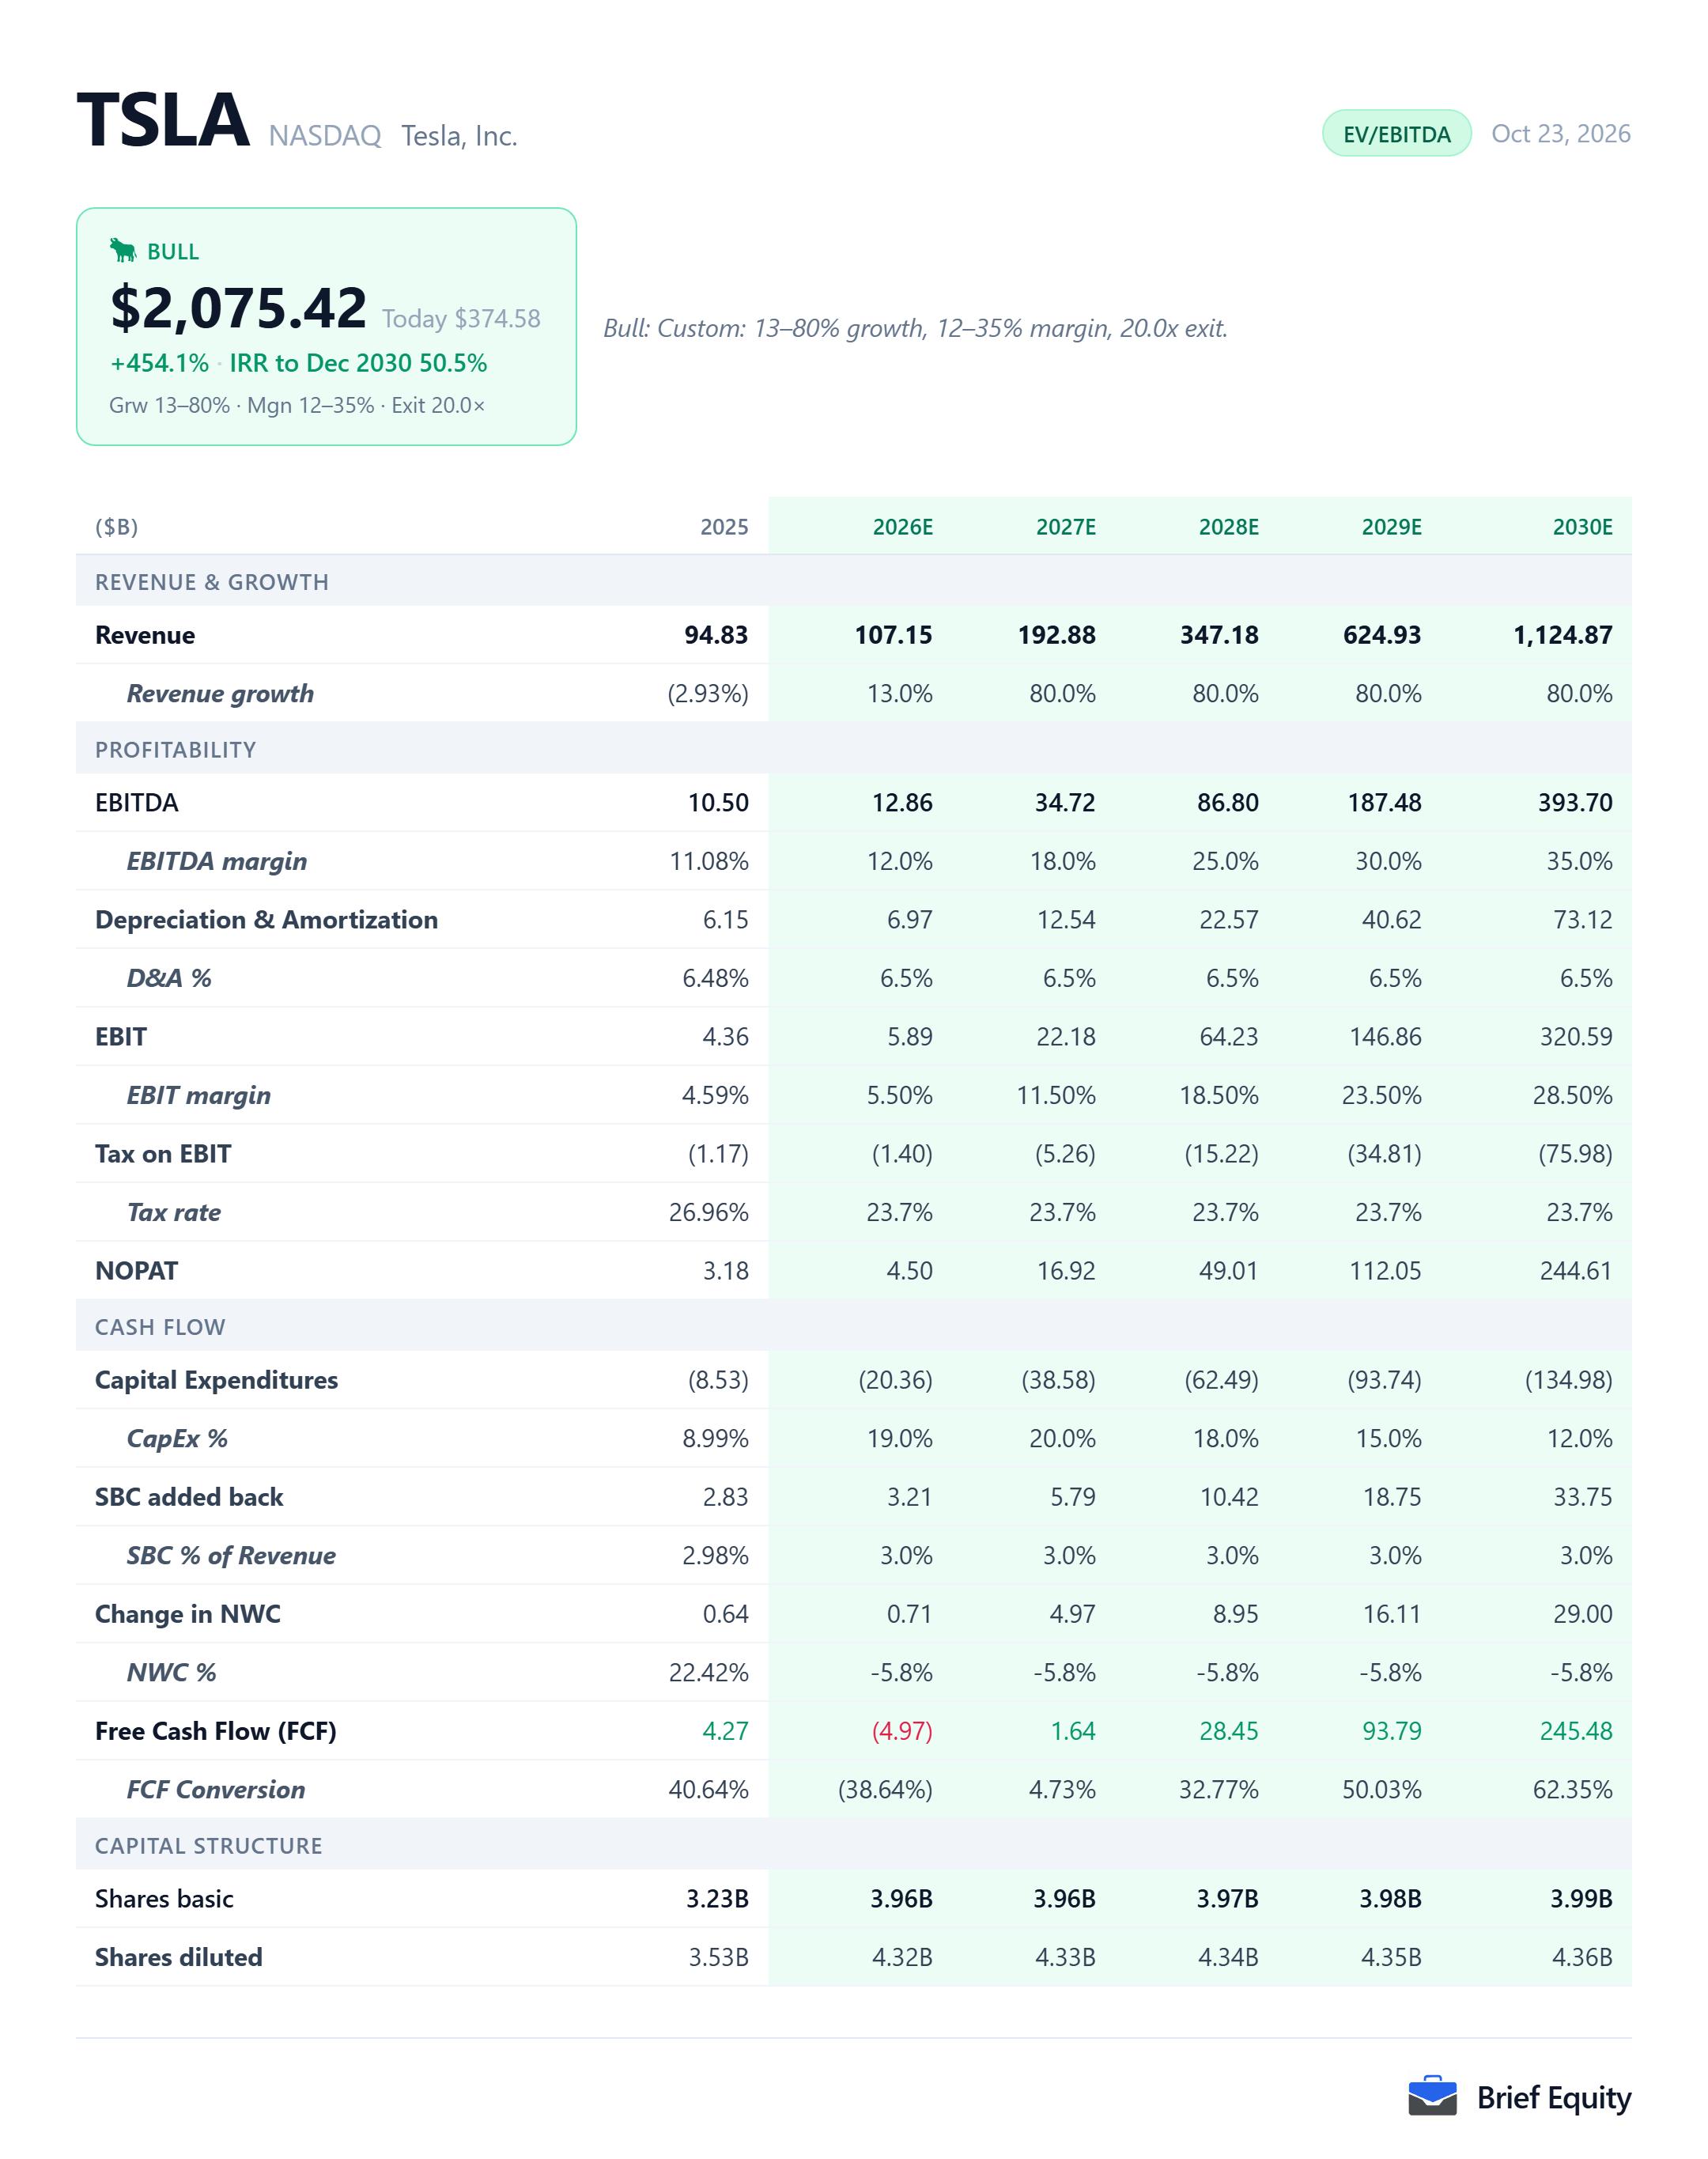
The model's assumptions for Tesla
Tesla's fiscal year is the calendar year. The figures below come from a quick model, built on a small set of stated assumptions and projected to 2030. Analyst consensus revenue is shown beside the model's revenue for the three years it covers.
| 2026 | 2027 | 2028 | 2029 | 2030 | |
|---|---|---|---|---|---|
| Revenue, model | 107.15 | 192.88 | 347.18 | 624.93 | 1,124.87 |
| Revenue growth, model | 13.0% | 80.0% | 80.0% | 80.0% | 80.0% |
| EBITDA, model | 12.86 | 34.72 | 86.80 | 187.48 | 393.70 |
| EBITDA margin, model | 12.0% | 18.0% | 25.0% | 30.0% | 35.0% |
| 2026 | 2027 | 2028 | |
|---|---|---|---|
| Revenue, model | 107.15 | 192.88 | 347.18 |
| Revenue, analyst consensus | 107.26 | 122.11 | 144.88 |
Why Tesla looks undervalued
Brief Equity's quick model of Tesla is deliberately speculative and loosely based on its chief executive's 2025 performance award. On it, Tesla looks cheap at a share price in the 370s if the company reaches every operational target in that award.
Tesla's 2025 performance award for Elon Musk sets operational milestones of 20 million vehicles delivered, 10 million active FSD subscriptions, 1 million bots delivered, 1 million Robotaxis in commercial operation and $400 billion of Adjusted EBITDA.
Tesla's chief executive added two targets on the company's earnings calls. On the third-quarter 2026 call Musk said Tesla is aiming for 5 million vehicles a year by approximately 2030, and on the second-quarter call he described production of the fourth version of its Optimus robot in these terms.
“So sort of aspirationally 10 million units a year versus 1 million units a year of Optimus 3.”
Elon Musk, Chief Executive Officer, Tesla second-quarter 2026 earnings call, July 22, 2026
With those targets typed in, the model has revenue growing 80.0% a year from 2027 to 2030, reaching $1,124.87 billion, with the EBITDA margin rising from 12.0% to 35.0%. Valuing the company at 20 times its EBITDA of $393.70 billion in 2030 gives about $2,075 a share.
Tesla's income from operations in the third quarter of 2026 was $718 million, against $1,624 million a year earlier.
Tesla's next-generation Roadster plays no part in the model. Tesla's third-quarter update lists it as in design development, and NBC News reported that Musk said production would not begin until 2028.
What has to be true, and what would break it
Tesla looks cheap on this model only if a few things hold, and the view fails if they do not.
What has to be true
- Tesla sells robots, Robotaxi rides and vehicles at the scale its 2025 performance award sets out, by 2030.
- Revenue grows 80% a year from 2027 to 2030 and the EBITDA margin reaches 35%.
- Investors pay 20 times EBITDA for the company in 2030.
What would break it
- Optimus and Robotaxi revenue arrive later, or smaller, than management's timeline.
- Vehicle deliveries stay limited by battery supply.
- Spending on AI, robots and the chip fab runs ahead of the revenue it earns.
The parts of Tesla's business
Tesla reports its revenue in three lines. Cars are still nearly three quarters of it, and revenue fell in 2025, so no part's share of growth is shown.
| Share of revenue | |
|---|---|
| Total automotive | 73.3% |
| Energy generation and storage | 13.5% |
| Services and other | 13.2% |
Tesla beside its peers
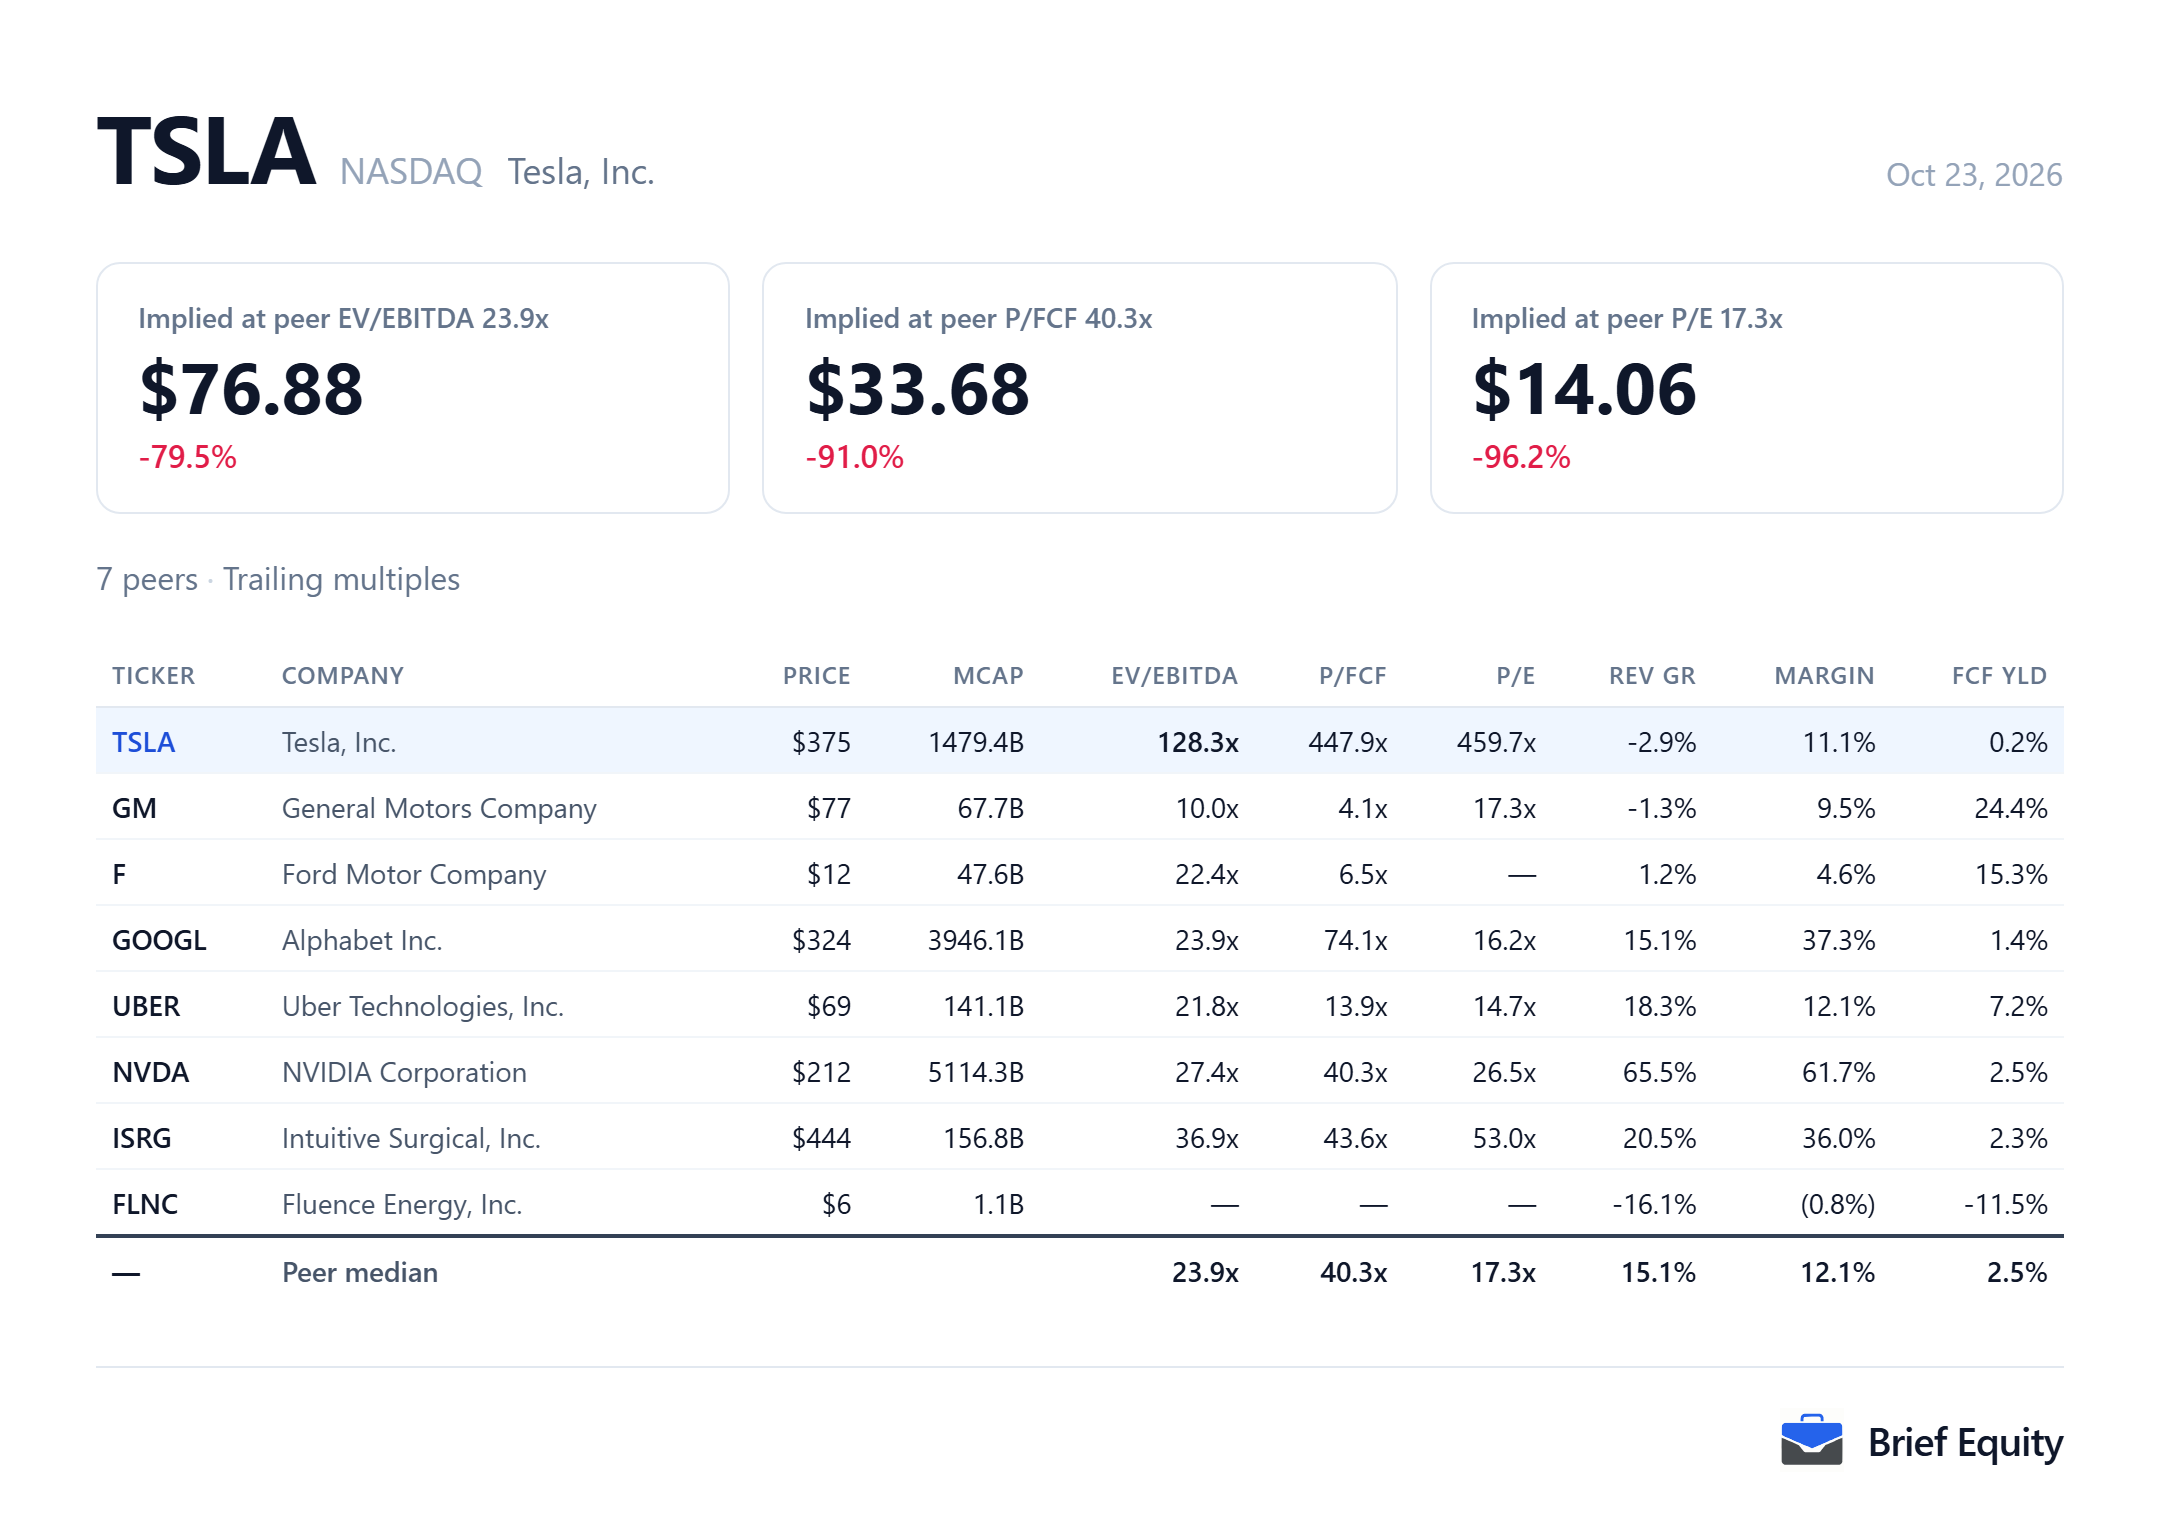
Tesla is compared here with seven companies, chosen to cover its cars and the businesses the model's growth rests on.
- GM: Cars, for automotive
- F: Cars, for automotive
- GOOGL: Waymo, for Robotaxi
- UBER: Ride-hailing, for Robotaxi
- NVDA: AI computing and autonomy
- ISRG: Robots sold at scale, for Optimus
- FLNC: Grid storage, for energy
How the estimate moves with its assumptions
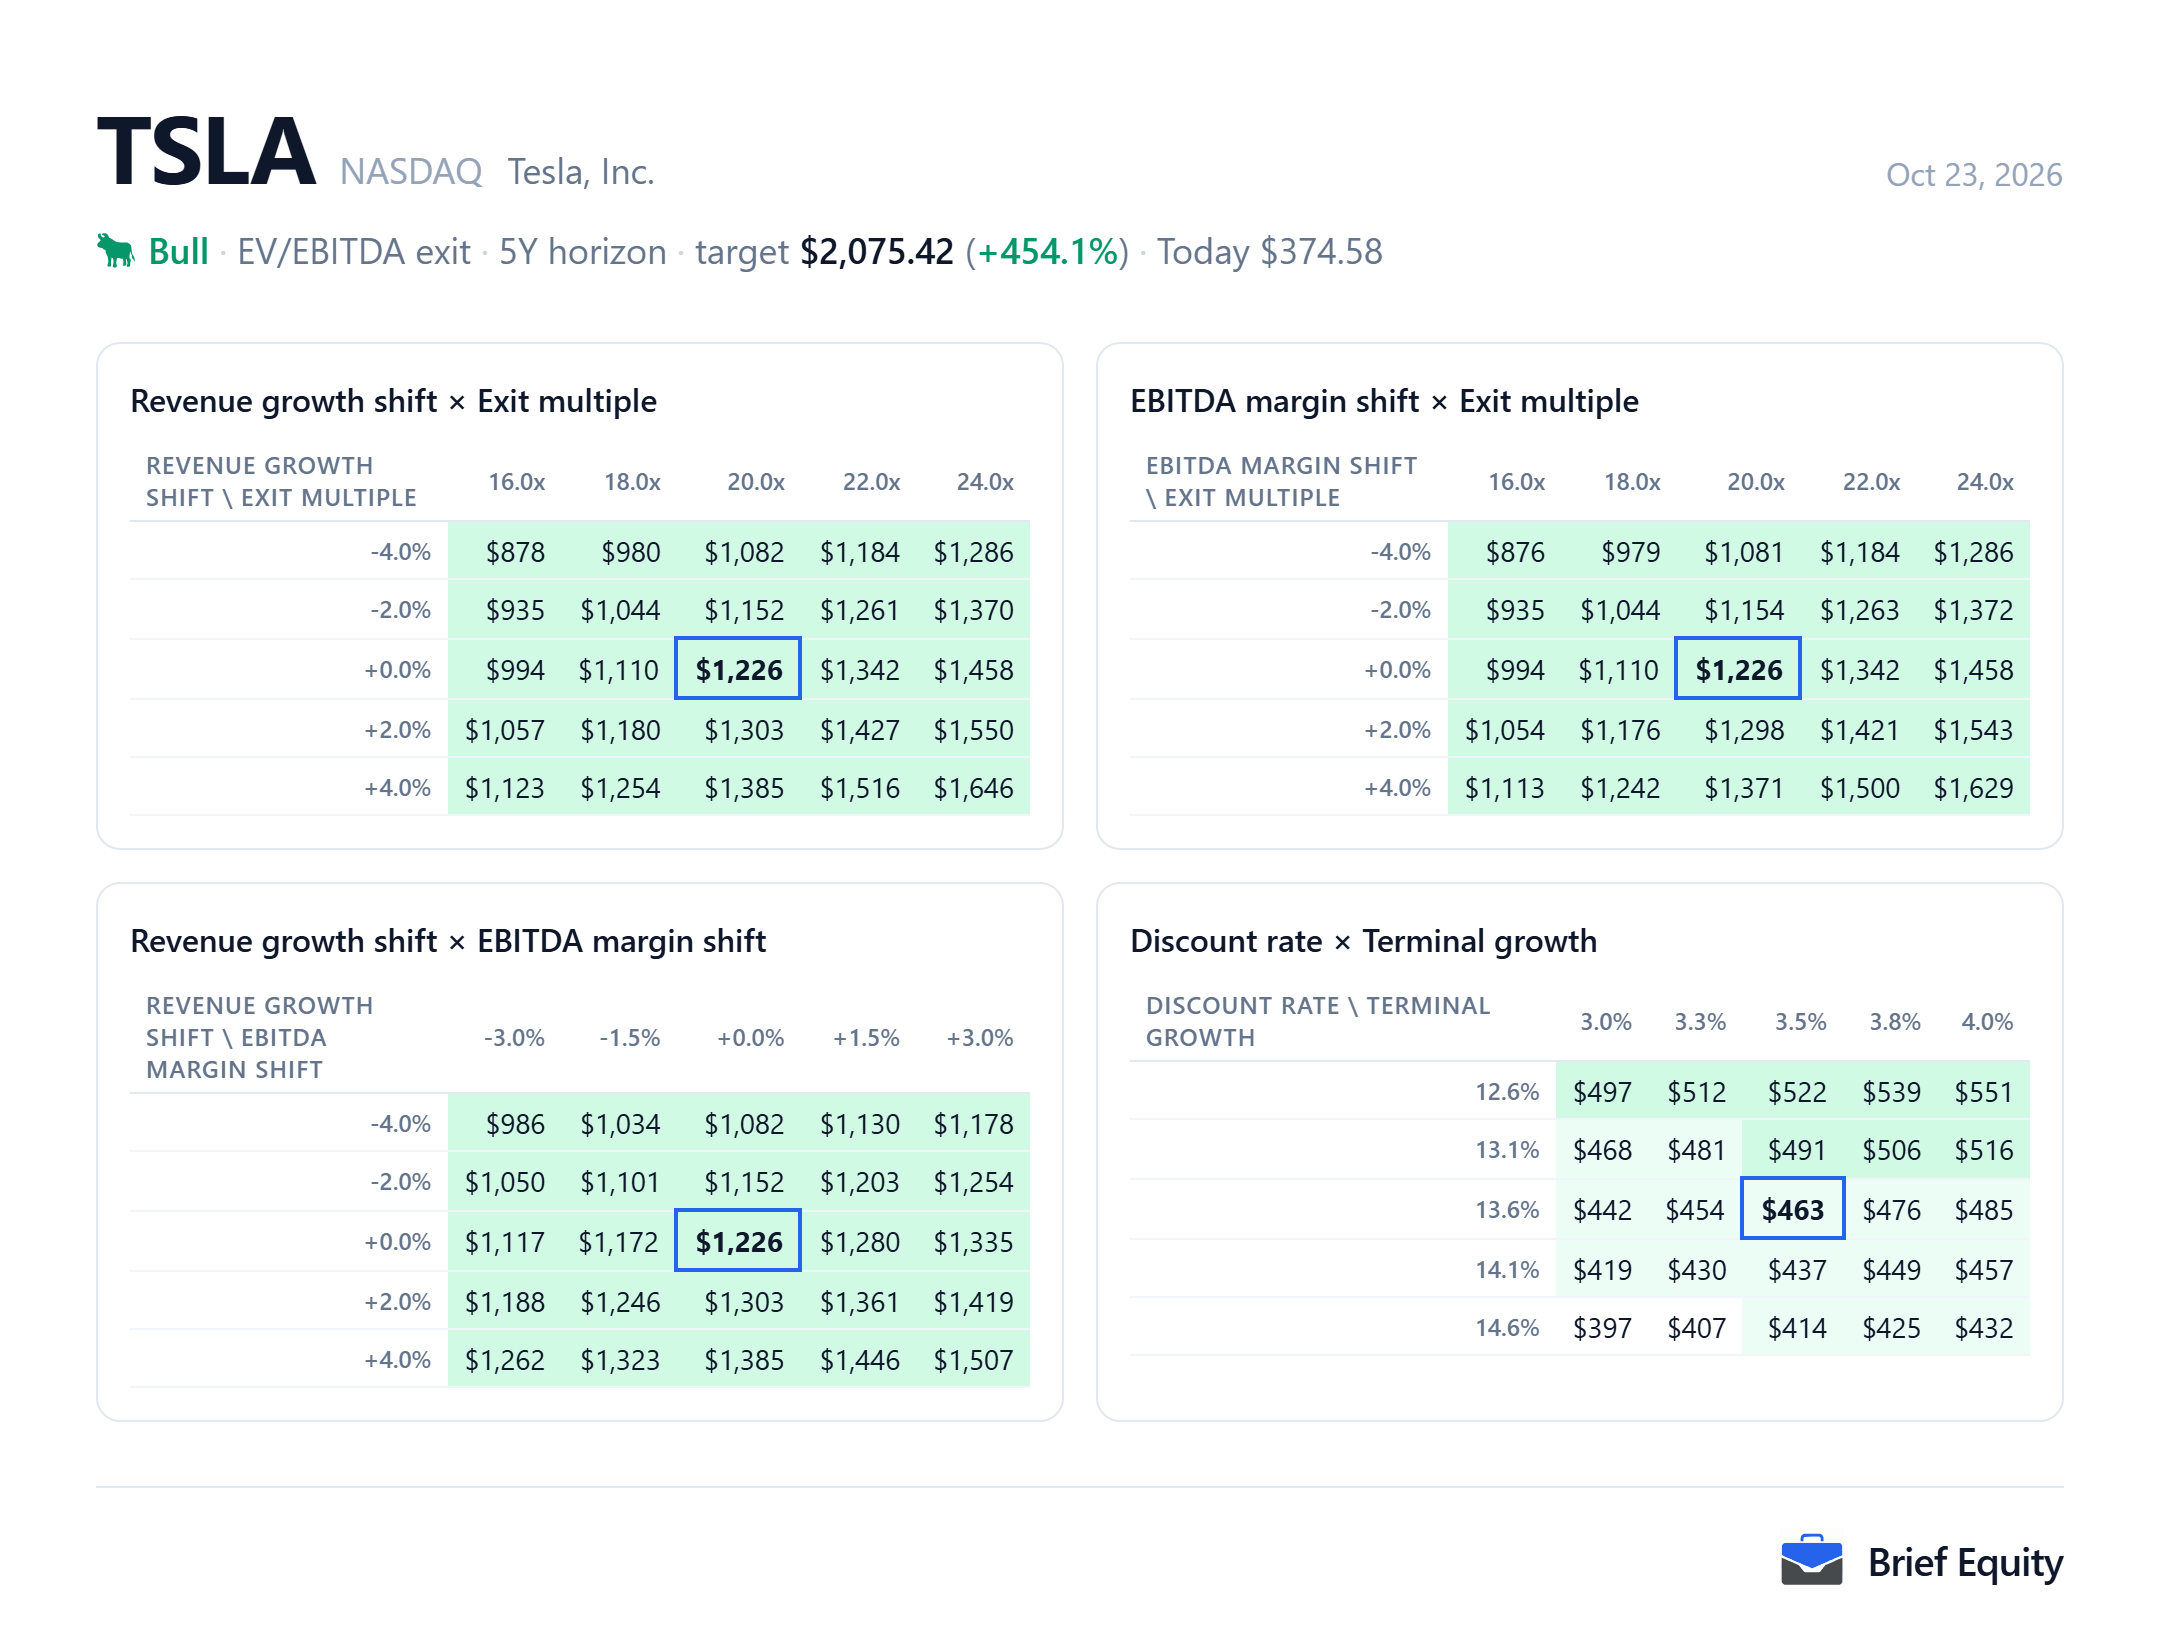
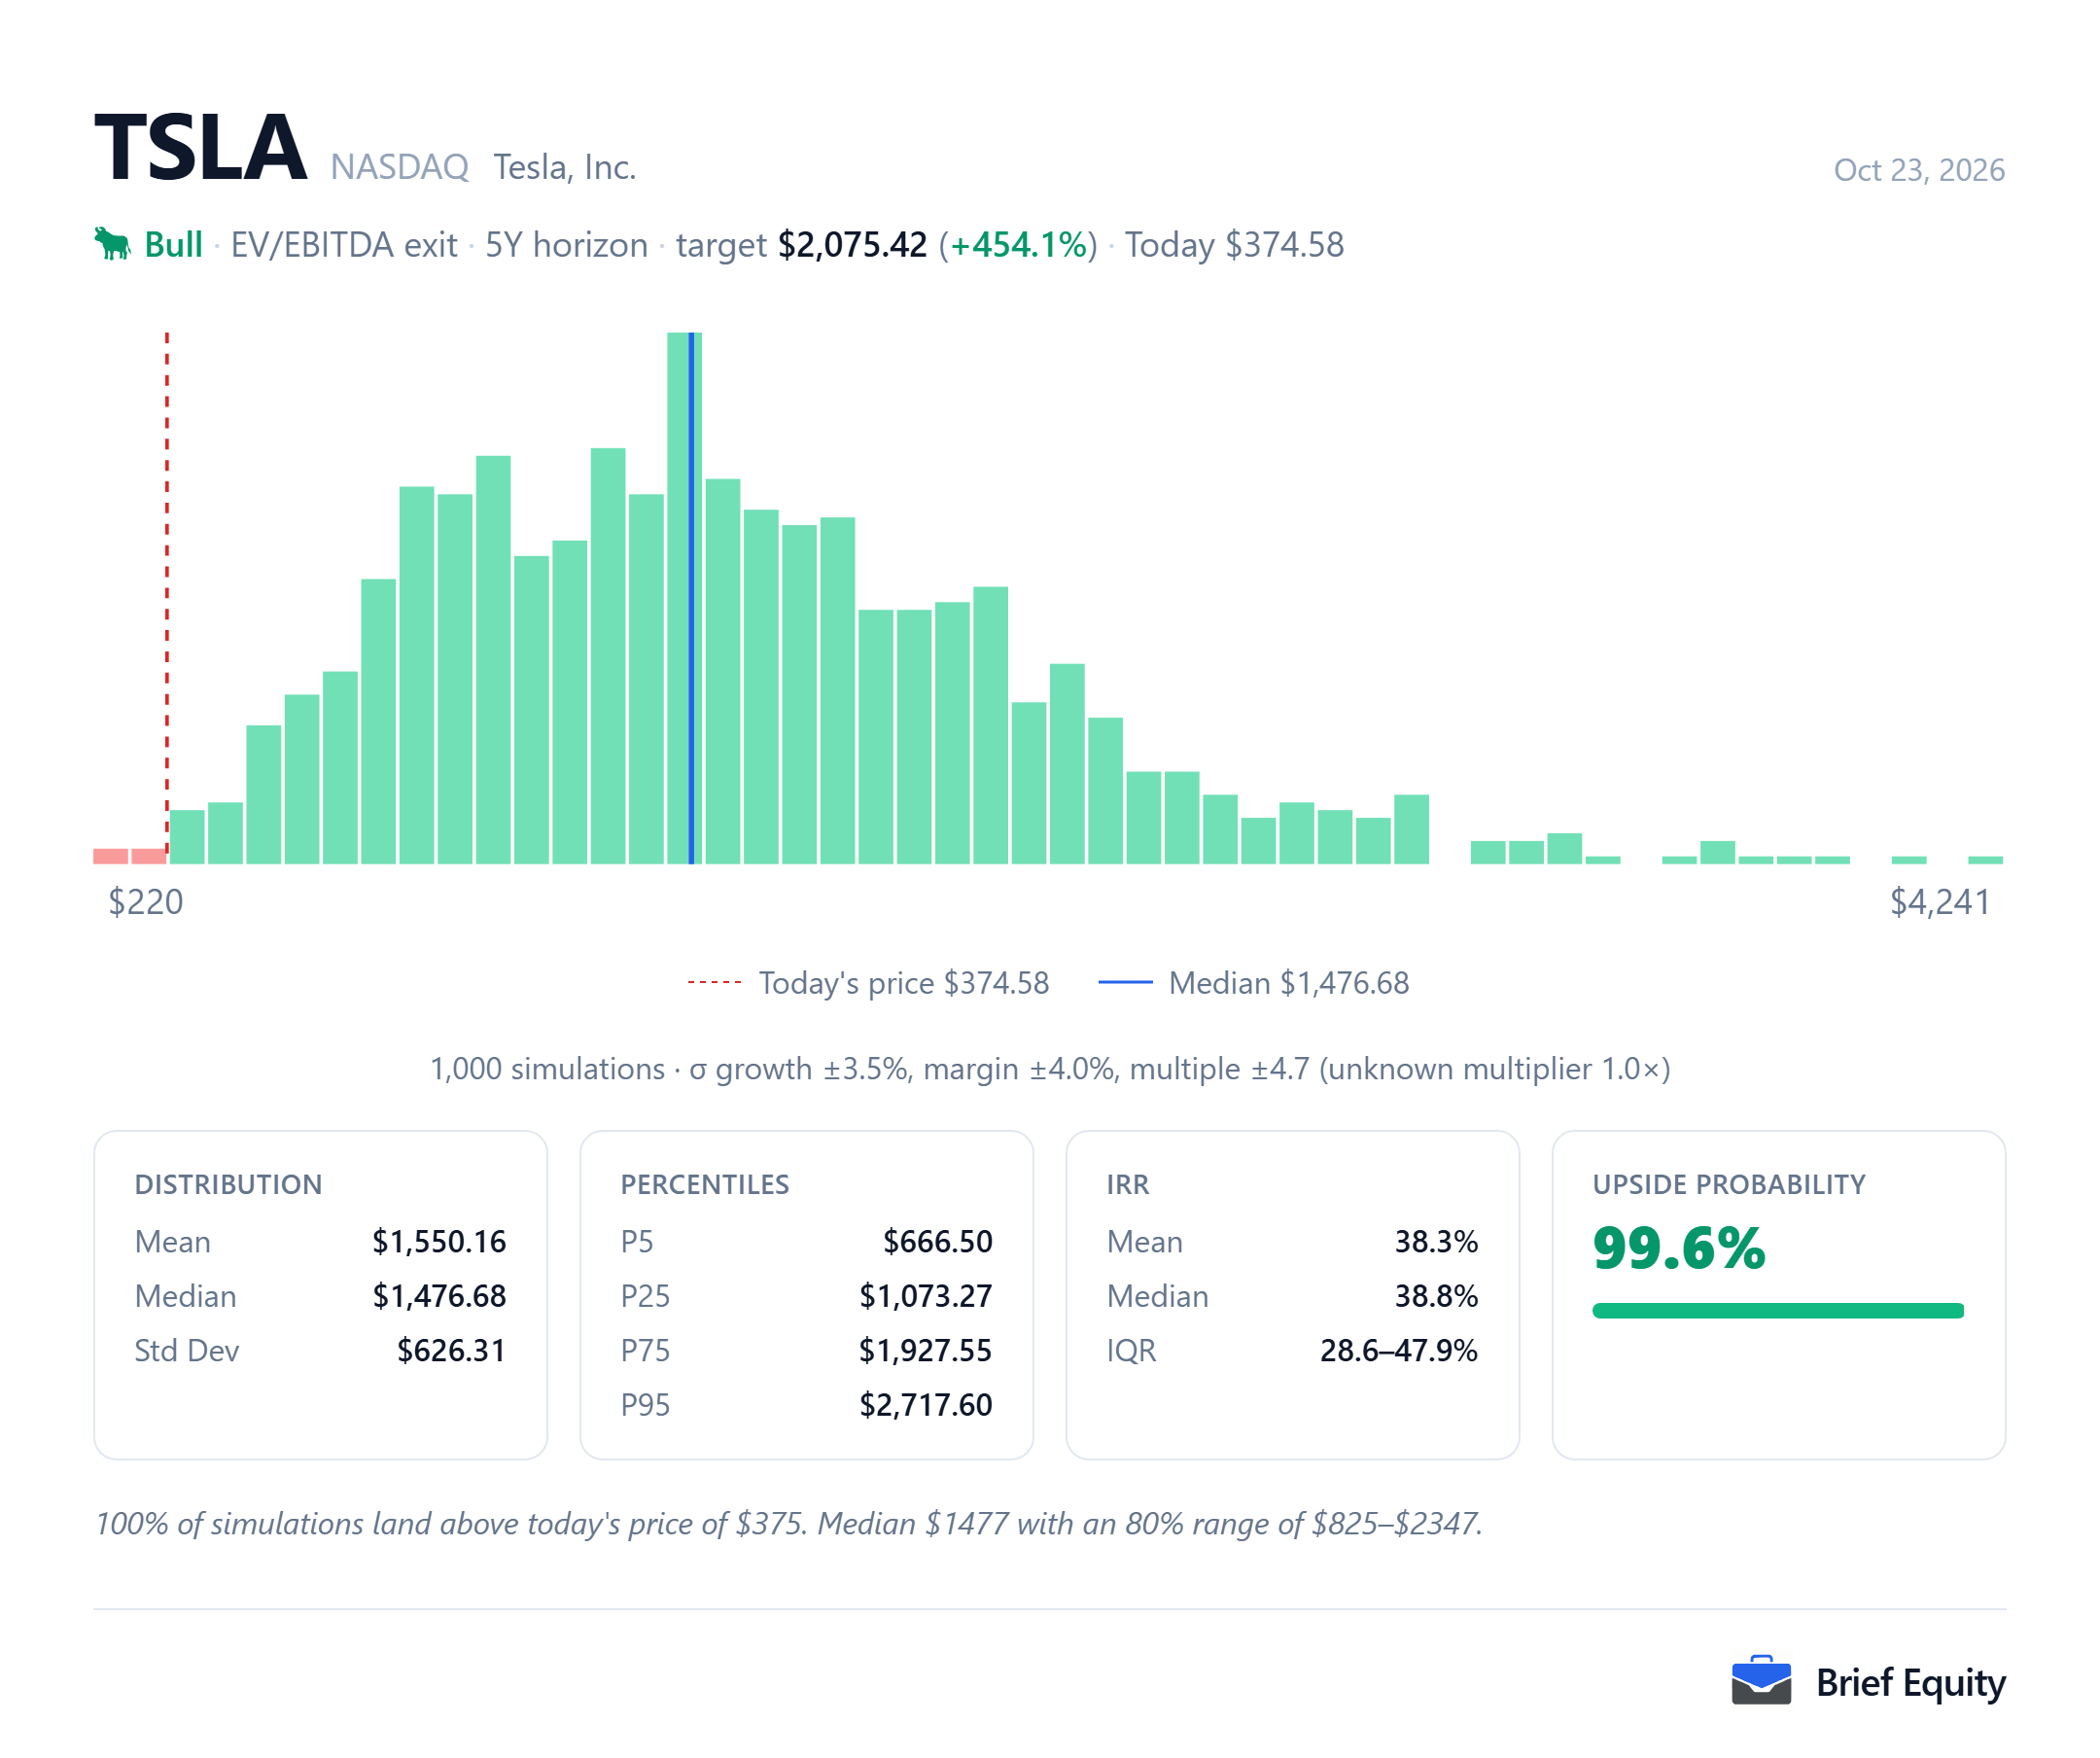
The estimate for Tesla depends on its assumptions, and the two pictures below show how far it moves when they change. The first varies two assumptions at a time. The second runs the model many times with growth, margin and the exit multiple varied at random.
Questions about Tesla
These questions about Tesla (TSLA) are answered from the documents listed under Sources.
- How much revenue did Tesla report for 2025?
- Tesla reported total revenues of $94,827 million for 2025, against $97,690 million in 2024.
- How many vehicles did Tesla deliver in the third quarter of 2026?
- Tesla delivered 486,532 vehicles in the third quarter of 2026, 2% fewer than a year earlier.
- How much cash does Tesla hold?
- Tesla reported cash, cash equivalents and short-term investments of $45.4 billion at the end of the third quarter of 2026.
- What capital expenditure does Tesla expect for 2026?
- On its third-quarter 2026 call Tesla revised its capital expenditure guidance for 2026 to approximately $20 billion.
Sources
The quotations and facts about Tesla (TSLA) on this page rest on the documents below.
- Tesla annual report (Form 10-K) for 2025, January 29, 2026
- Tesla quarterly report (Form 10-Q) for the quarter ended September 30, 2026, October 22, 2026
- Tesla third-quarter 2026 update, October 21, 2026
- Tesla third-quarter 2026 earnings call, October 21, 2026
- Tesla second-quarter 2026 earnings call, July 22, 2026
- Elon Musk shows off ‘flying’ Tesla Roadster after years of delays, October 16, 2026
About this page
Brief Equity and its team hold no position in Tesla (TSLA) as of October 23, 2026.
This page is research, not investment advice. It describes one model and the assumptions behind it, and market data is delayed. Read how these models are built and our editorial policy.
Related guides: EV/EBITDA explained, What is enterprise value (EV), How to build a DCF model (step by step).