Valuation · EV/EBITDA model
Is Starbucks (SBUX) stock overvalued?
On October 31, 2026, with the shares at $103.67, a quick EV/EBITDA model by Brief Equity valued Starbucks at about $114 for fiscal 2029. Starbucks looks overvalued on that model unless North America, 76.2% of its fiscal 2026 revenue, starts adding coffeehouses again: Starbucks plans only 90 to 100 net new there in fiscal 2027, and guides that year's revenue to decline by approximately 1% even with a 53rd week.
By The Brief Equity Team · Model dated · Published
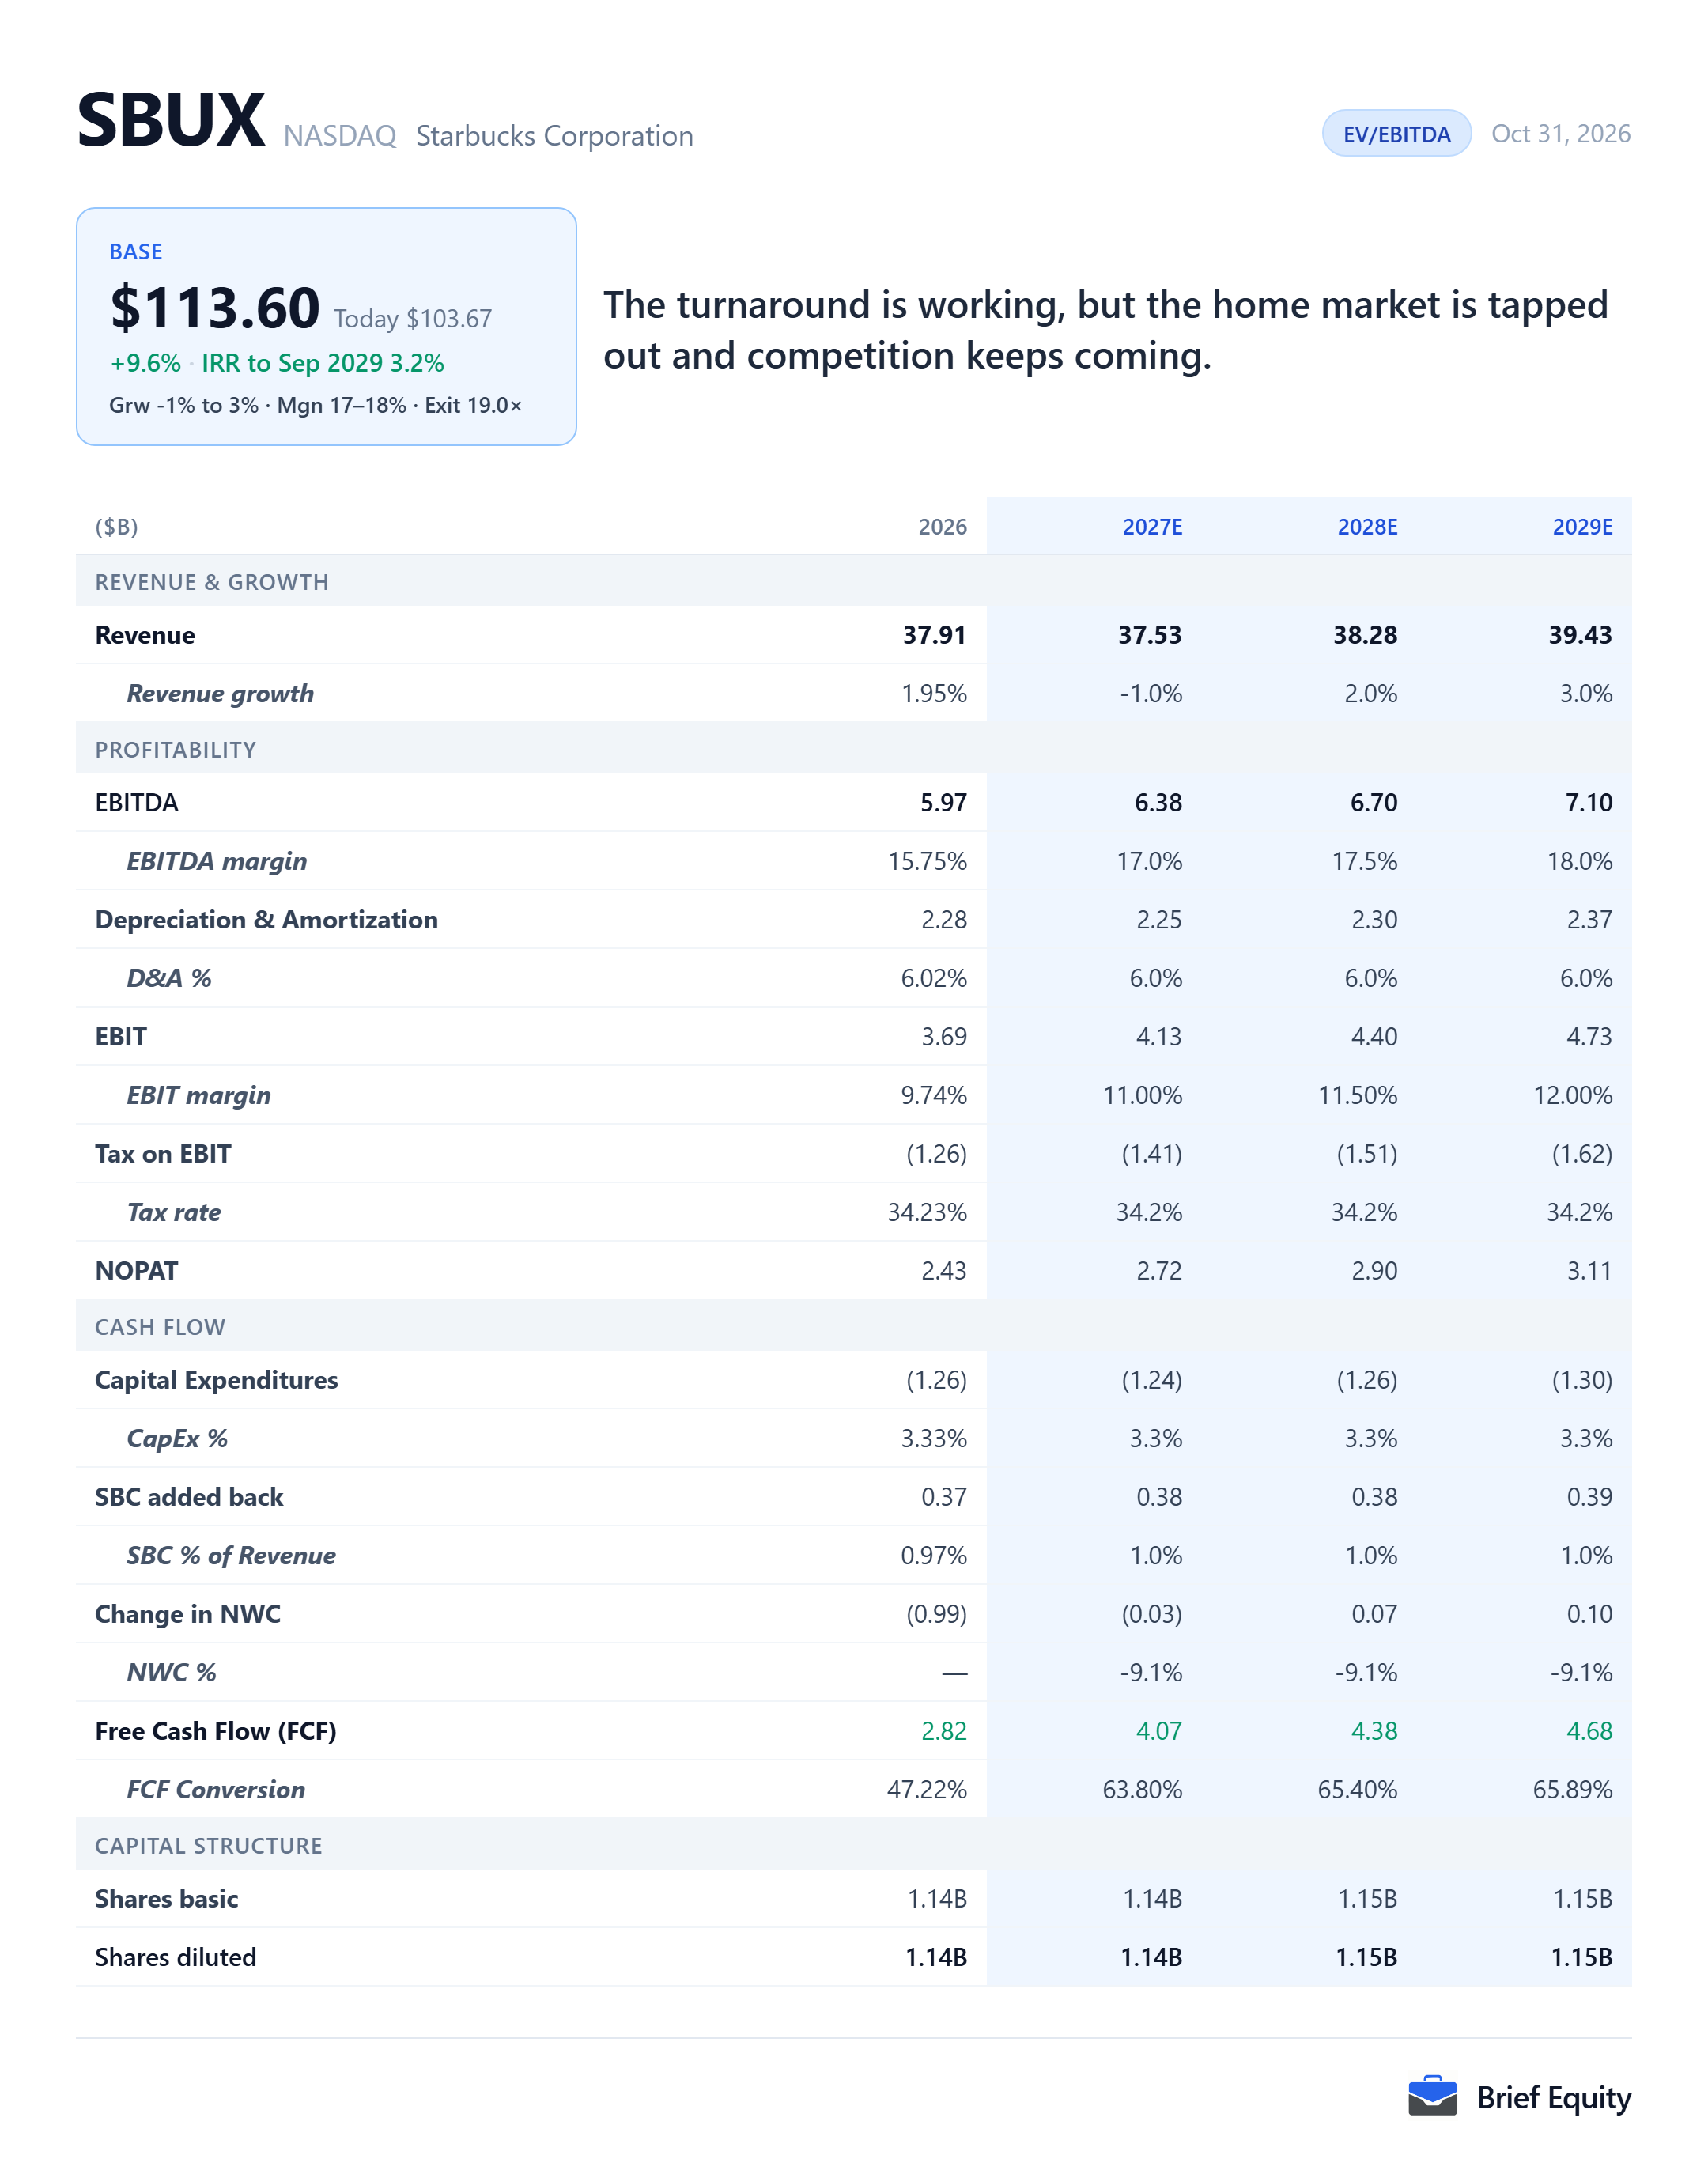
The model's assumptions for Starbucks
Starbucks' fiscal 2026 ended on September 27, 2026, and its fiscal 2027 runs 53 weeks rather than 52. The model runs three years, to fiscal 2029, and every row below is the model's own.
| Fiscal 2027 | Fiscal 2028 | Fiscal 2029 | |
|---|---|---|---|
| Revenue, model | 37.53 | 38.28 | 39.43 |
| Revenue growth, model | -1.0% | 2.0% | 3.0% |
| EBITDA, model | 6.38 | 6.70 | 7.10 |
| EBITDA margin, model | 17.0% | 17.5% | 18.0% |
Why Starbucks looks overvalued
Starbucks' chairman and chief executive, Brian Niccol, said with the company's fiscal 2026 results on October 29, 2026 that its Back to Starbucks plan had begun as a turnaround and had become its plan for growth.
“Back to Starbucks started as our turnaround plan. Now, it's our growth plan.”
Starbucks fourth-quarter and fiscal 2026 results release, October 29, 2026
The Starbucks turnaround shows in its results. North America comparable coffeehouse sales increased 7.9% in the fourth quarter of fiscal 2026, and the fiscal 2027 guidance of a 13.5% to 14.0% non-GAAP operating margin reaches the low end of the margin target for fiscal 2028 that the company set at its Investor Day, a year early. The shares are still below the $106.07 at which they closed October 2021.
Starbucks depends on North America, which was 76.2% of its fiscal 2026 revenue, and the segment's coffeehouse count fell 1% in the year. The company plans 90 to 100 net new coffeehouses in North America in fiscal 2027, against approximately 1,100 in its International segment. Beyond the company, the US population grew 0.5% between July 1, 2024 and July 1, 2025, according to the Census Bureau, while Dutch Bros had 1,225 shops at June 30, 2026, against 1,043 a year earlier.
The model has Starbucks' revenue growth at -1.0% in fiscal 2027, which is the company's guidance, reflecting the move of its retail business in China to a licensed joint venture and including a 53rd week, then 2.0% in fiscal 2028 and 3.0% in fiscal 2029. That compounds to 1.3% a year, against analyst consensus of 3.4% a year from 2026 to 2029.
With an exit multiple of 19 times EBITDA, the model values Starbucks at about $114 a share for fiscal 2029, about 10% above the share price.
What has to be true, and what would break it
Starbucks looks overvalued on this model as long as its growth stays close to what the company itself plans.
What has to be true
- North America, 76.2% of Starbucks' fiscal 2026 revenue, keeps adding few net new coffeehouses.
- Revenue growth stays in low single digits once the change to a licensed model in China has been lapped.
- Competitors such as Dutch Bros keep adding shops in the United States.
What would break it
- US transactions keep growing, as they did when they rose 2.4% in the fourth quarter of fiscal 2026.
- Starbucks reopens its US pipeline, as its aim of more than 300 new US units in fiscal 2028 describes.
- The operating margin runs past the top of the 13.5%-15% target for fiscal 2028.
The parts of Starbucks's business
Starbucks reports three segments, and North America was 76.2% of its fiscal 2026 revenue. International's revenue fell in fiscal 2026 because Starbucks' retail business in China became a licensed joint venture, so no segment's share of growth is shown.
| Share of revenue | |
|---|---|
| North America | 76.2% |
| International | 17.8% |
| Channel Development | 5.7% |
Starbucks beside its peers
Starbucks is compared here with eight US-listed companies, chosen to cover its mature home market, its coffee competitors and its licensed and packaged businesses.
- MCD: A mature US chain with a saturated home market
- BROS: The US coffee competitor adding shops fastest
- QSR: Tim Hortons, a coffee-led franchisor
- YUM: A global franchisor, like the licensed International business
- YUMC: A restaurant operator in China, beside the China joint venture
- CMG: A US chain still growing its units
- DPZ: A mature US franchise
- KDP: At-home coffee, beside Channel Development
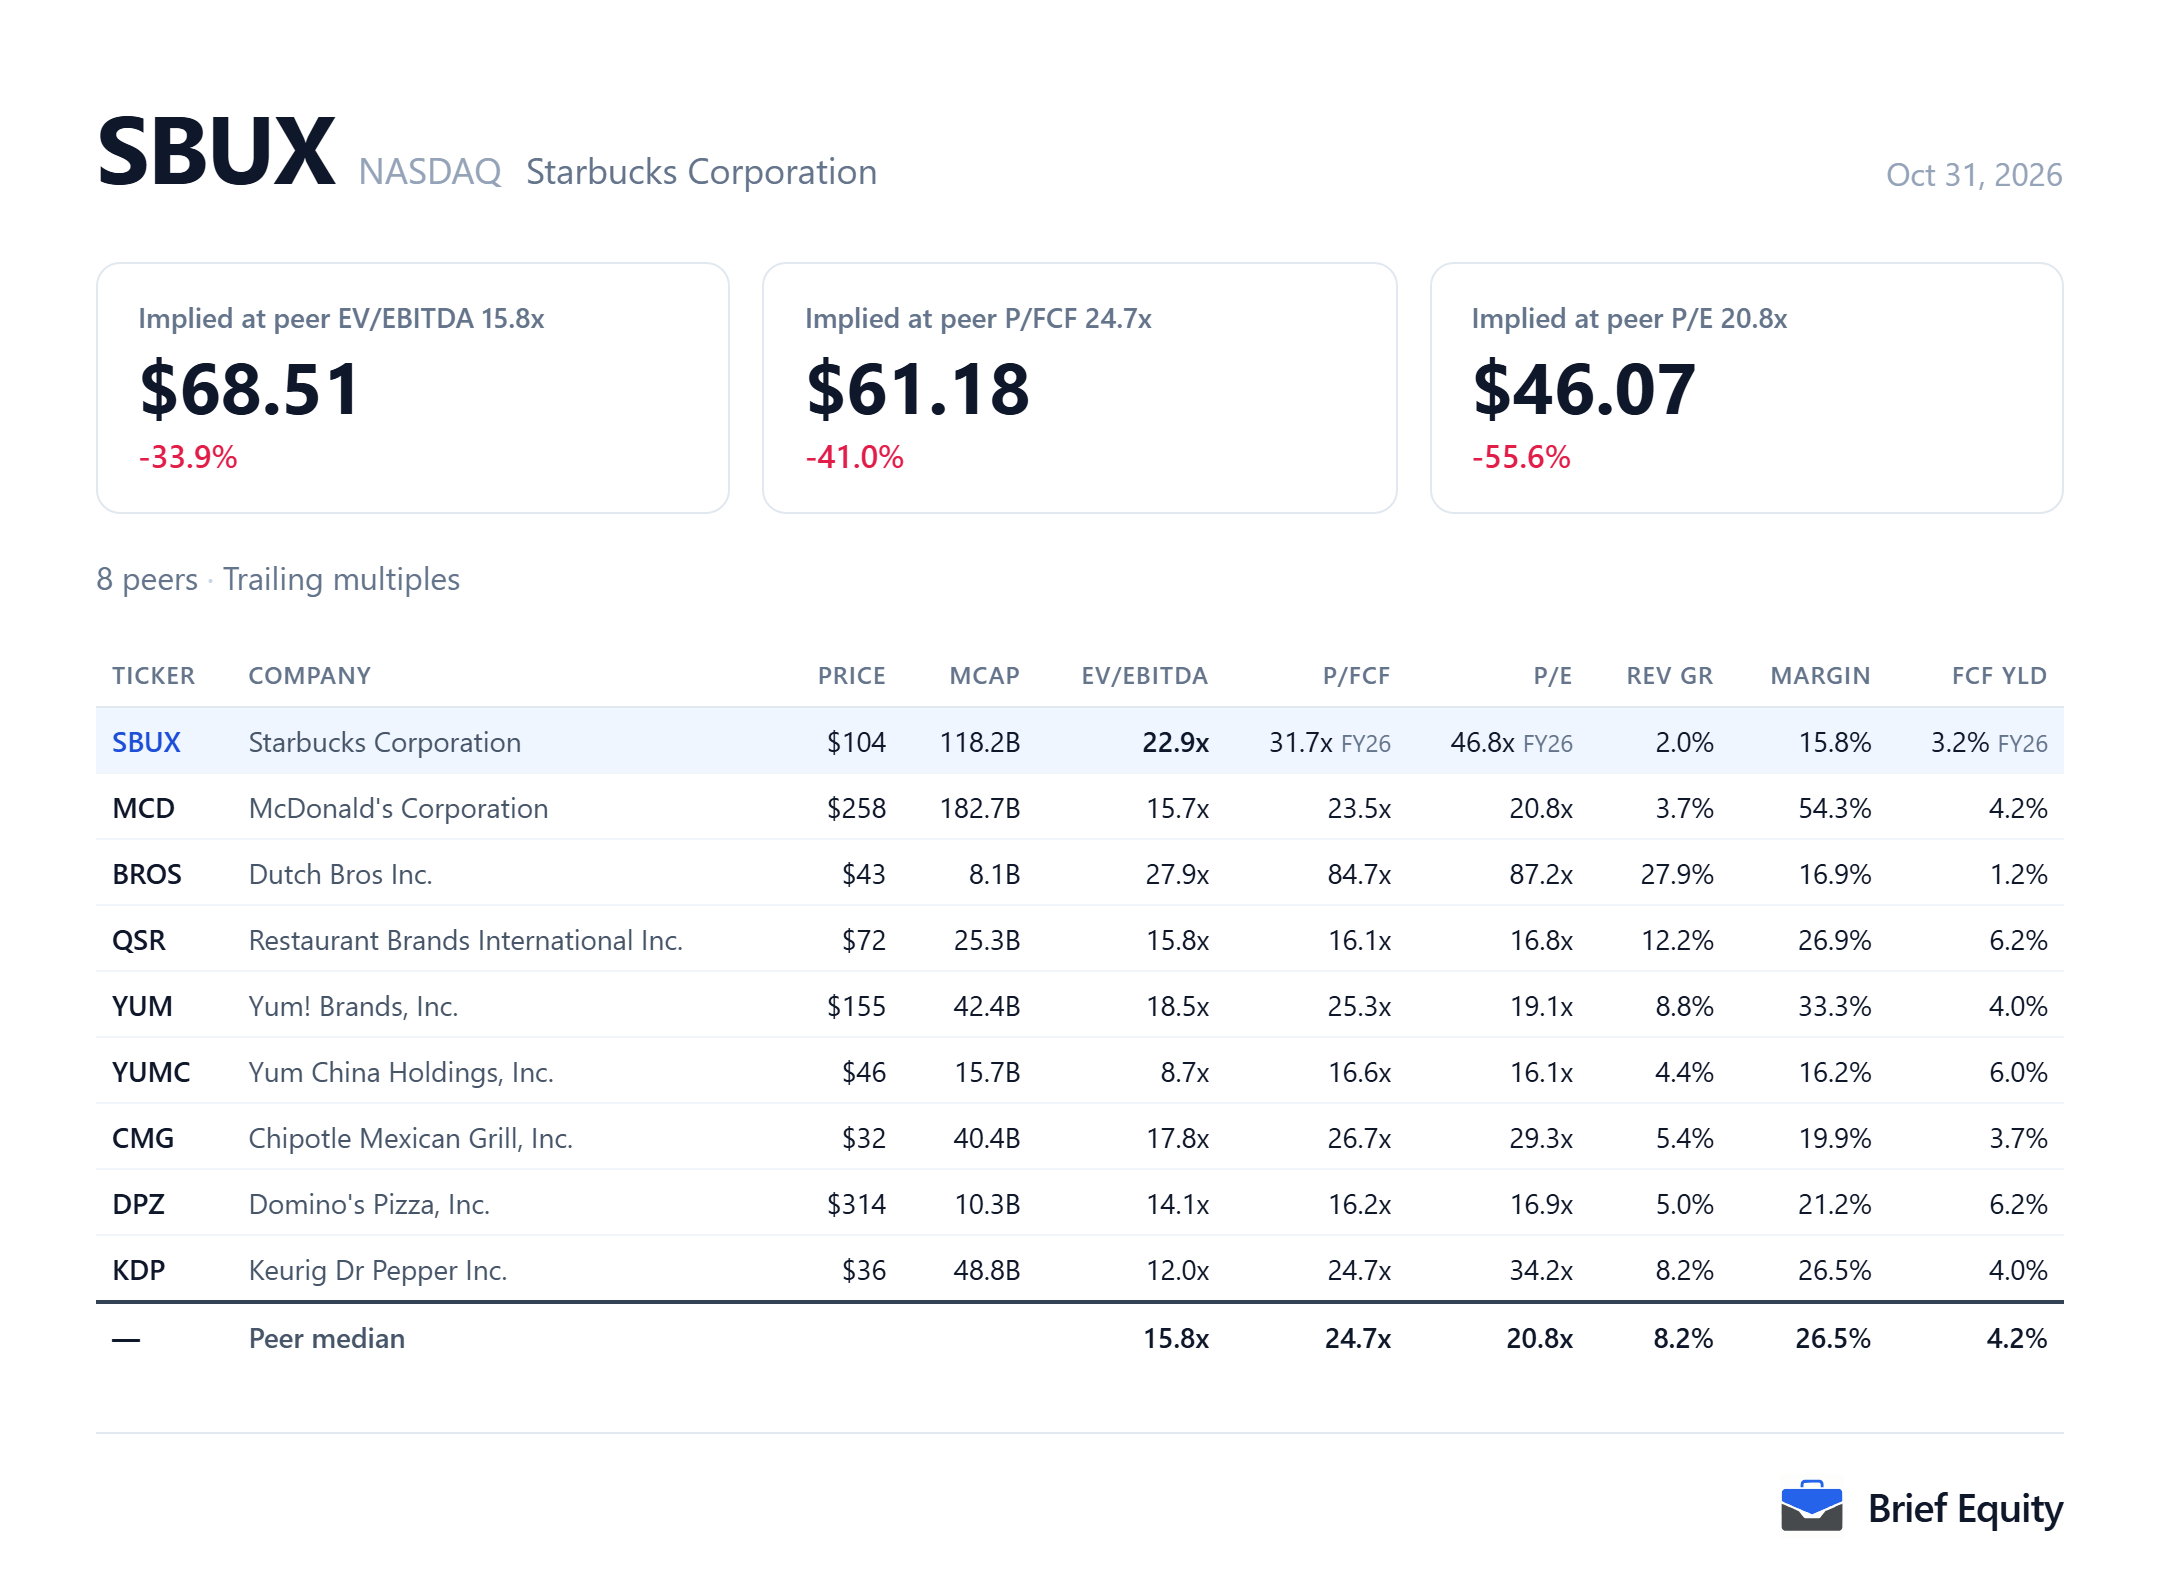
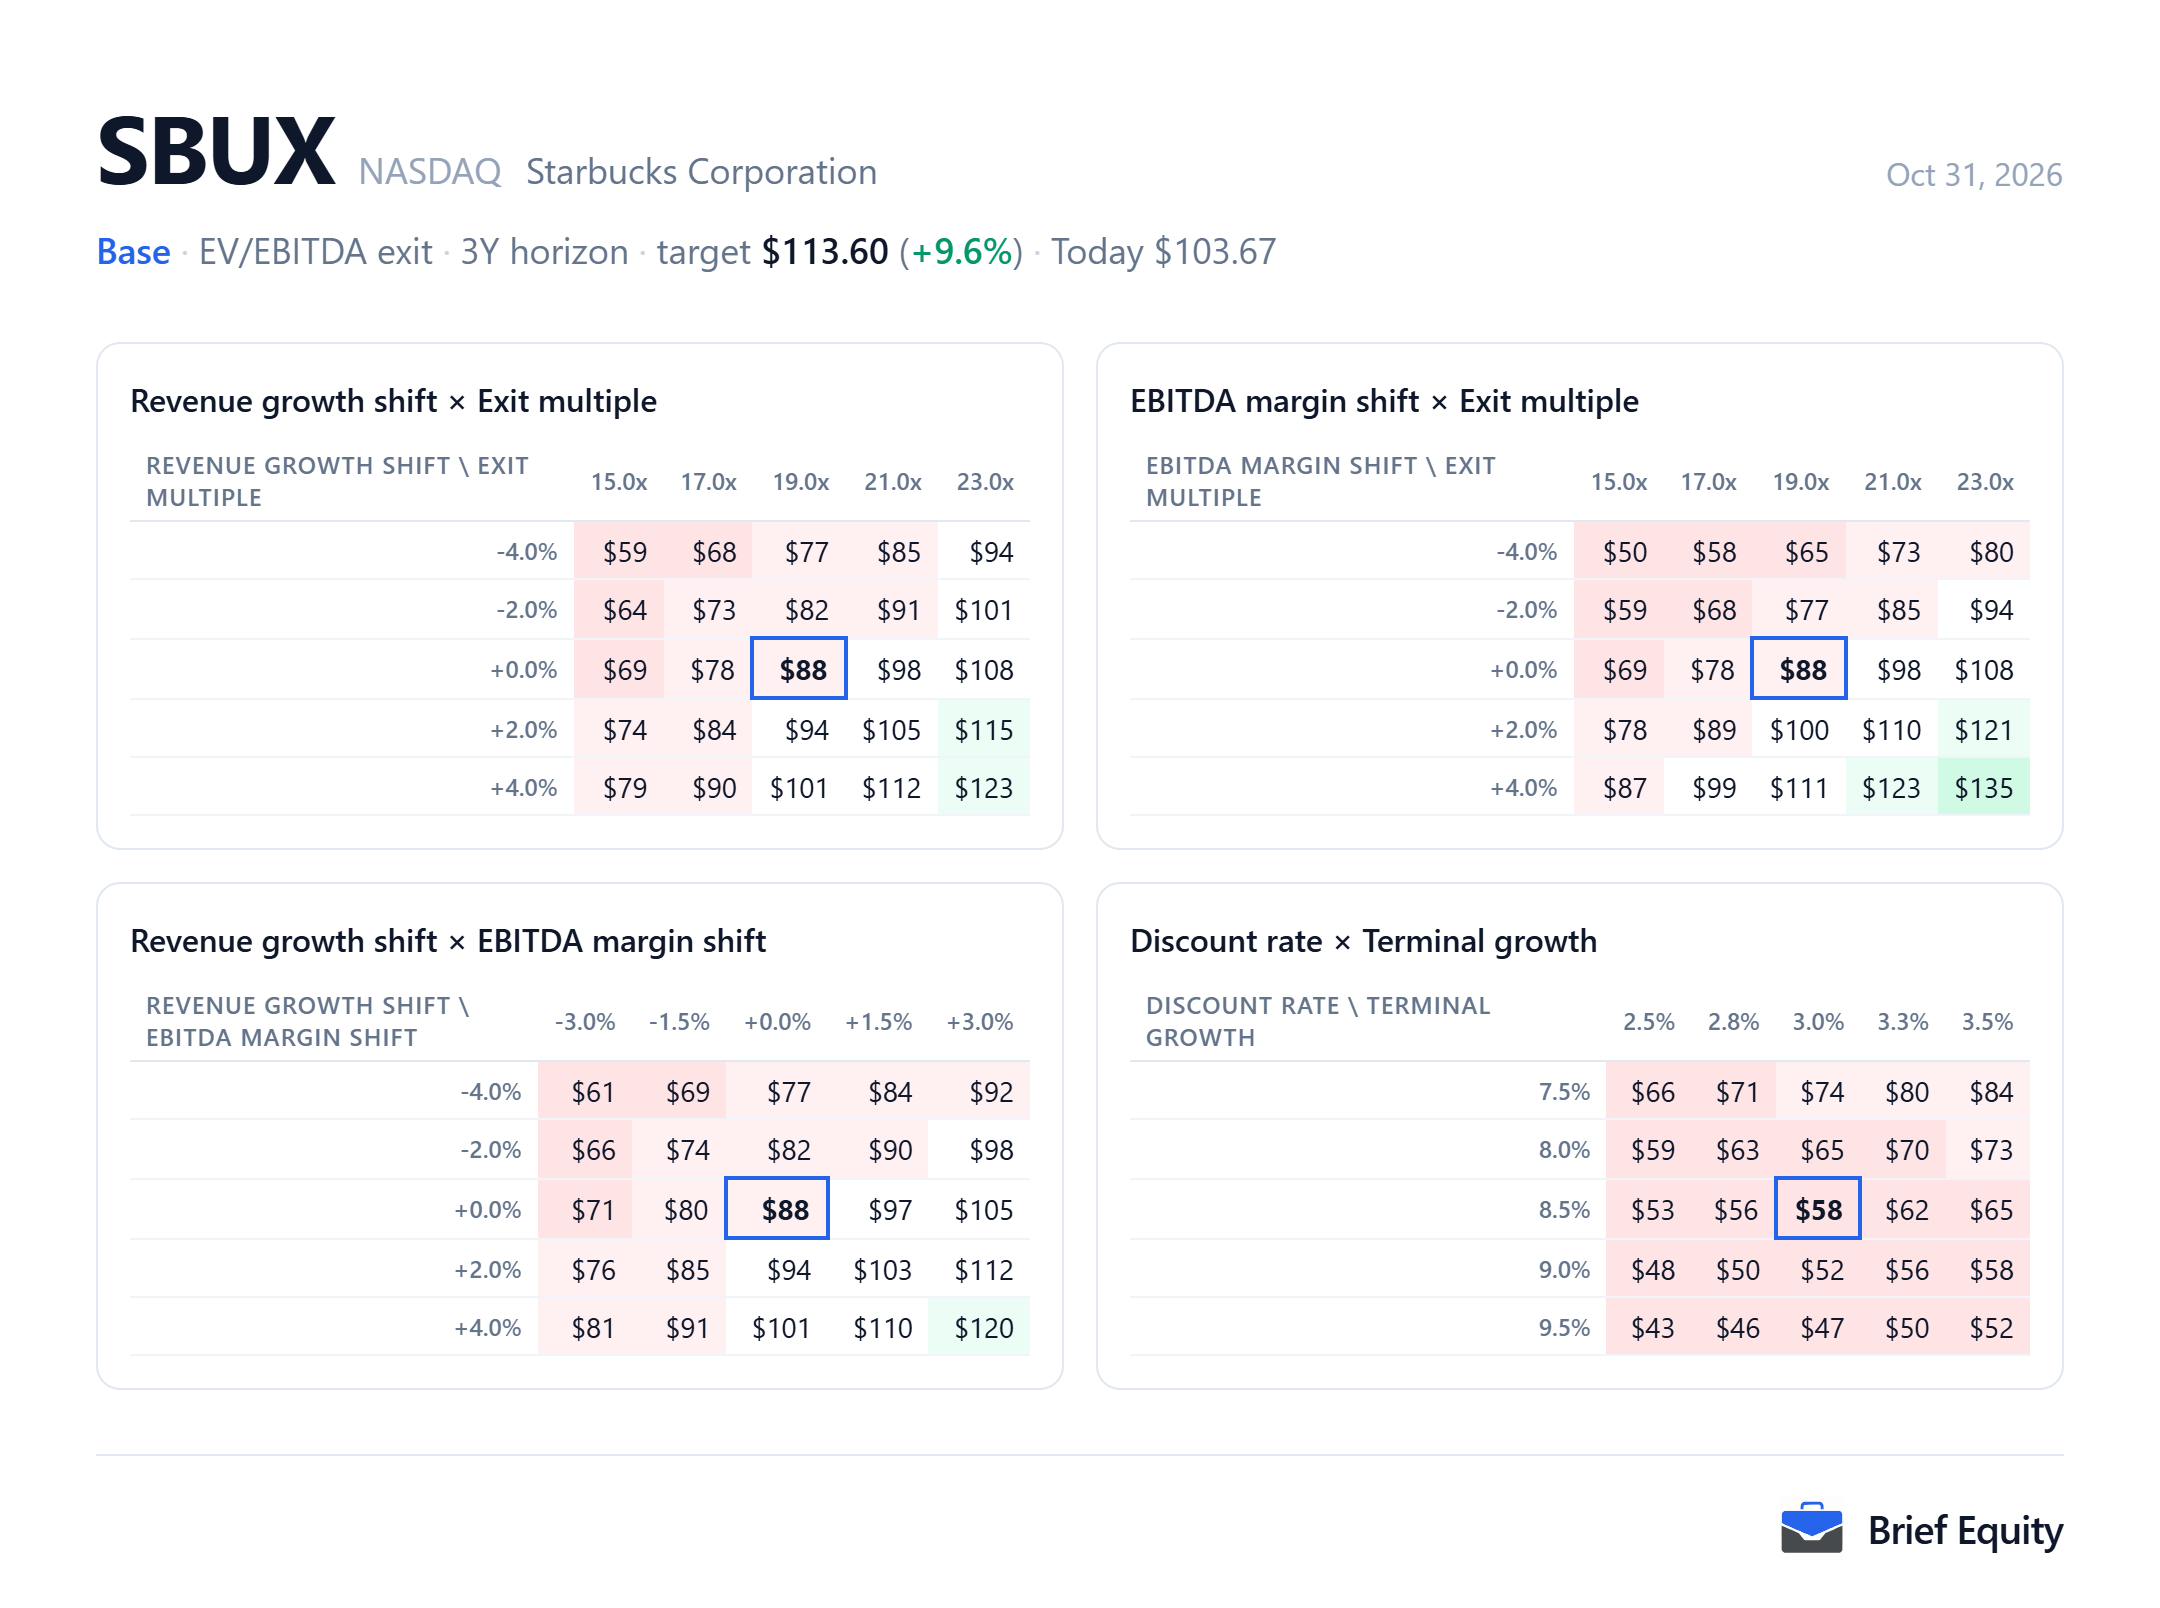
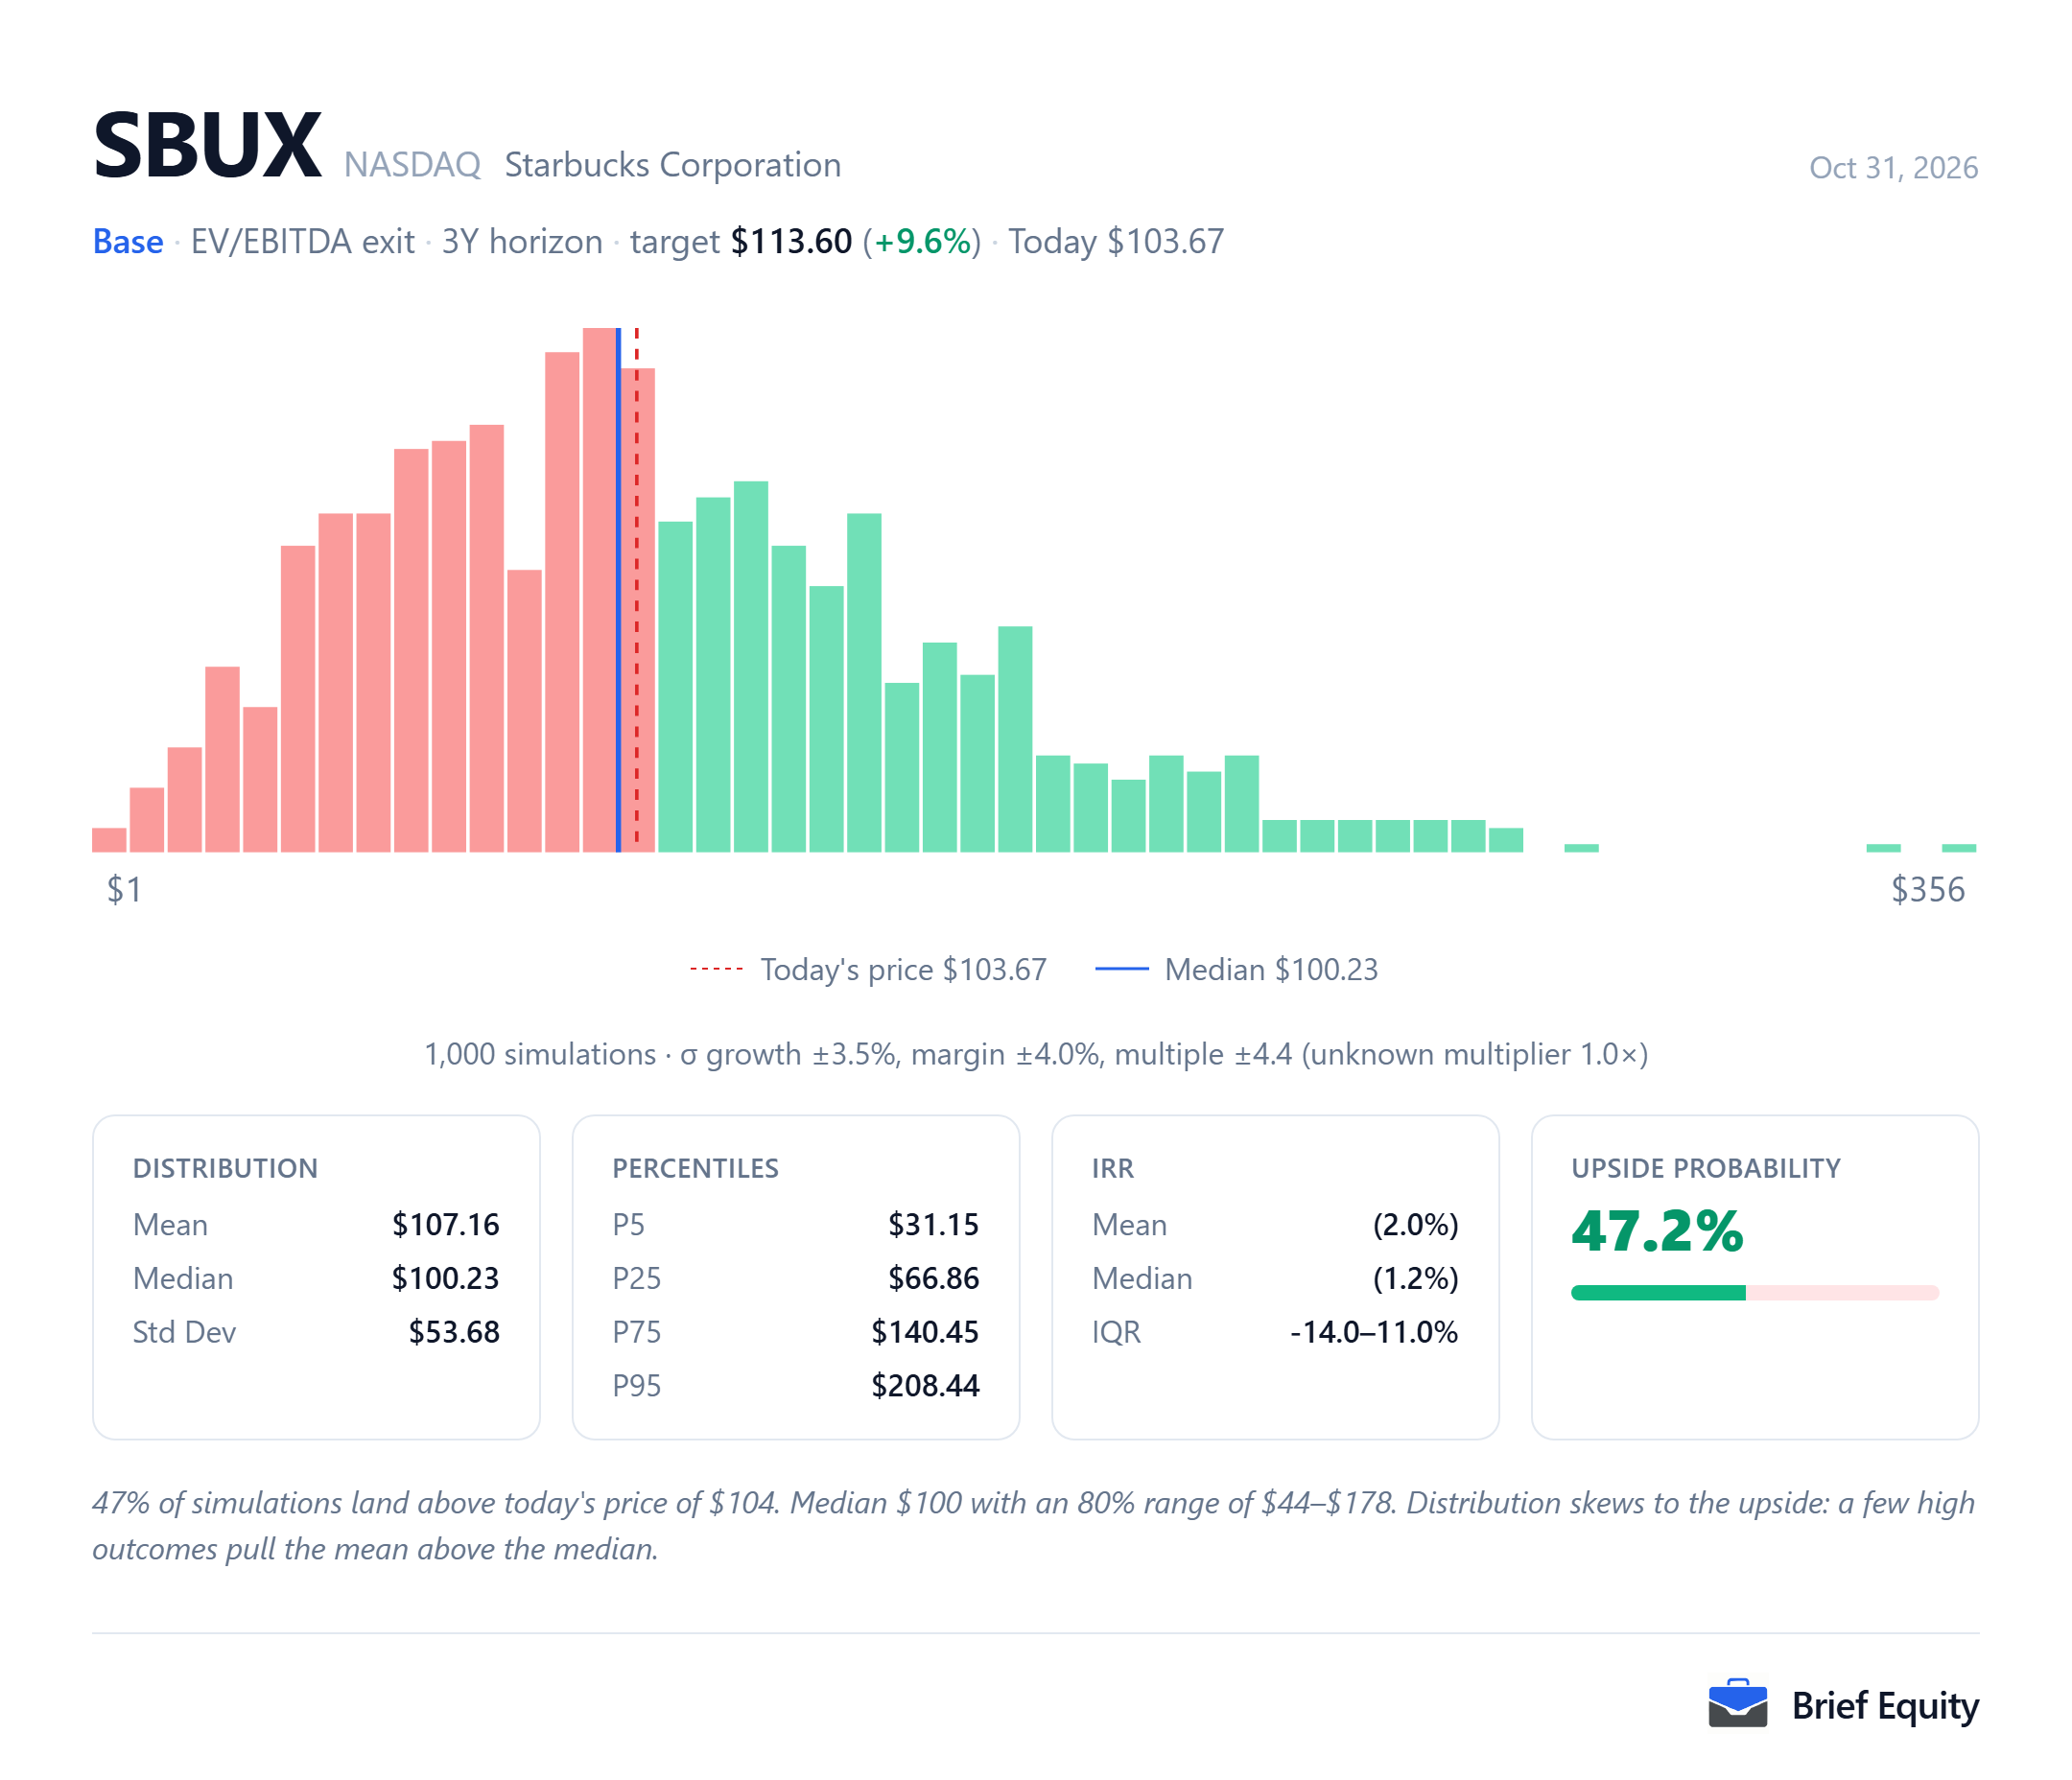
How the estimate moves with its assumptions
The two Starbucks cards below test the estimate: the sensitivity grids move two assumptions at a time, and the Monte Carlo card reruns the model many times with growth, margin and the exit multiple drawn at random.
Questions about Starbucks
These questions about Starbucks (SBUX) are answered from the documents listed under Sources.
- What earnings does Starbucks expect for fiscal 2027?
- On October 29, 2026, Starbucks guided fiscal 2027 non-GAAP earnings per share of $3.15 to $3.25, including slightly more than ten cents related to the 53rd week.
- How many coffeehouses does Starbucks have?
- Starbucks ended fiscal 2026, on September 27, 2026, with 41,607 coffeehouses, 32% company-operated and 68% licensed.
- What did Starbucks gain on selling control of its China retail business?
- The divestiture of Starbucks' retail operations in China in the third quarter of fiscal 2026 resulted in a pre-tax gain of $536.3 million.
- Does Starbucks plan to buy back shares?
- On October 29, 2026, Starbucks' chief financial officer said the company plans to resume share repurchases in fiscal 2027.
Sources
The quotations and facts about Starbucks (SBUX) on this page rest on the documents below.
- Starbucks fourth-quarter and fiscal 2026 results release, October 29, 2026
- Starbucks fourth-quarter fiscal 2026 earnings call, October 29, 2026
- Starbucks Investor Day 2026 release, January 29, 2026
- US Census Bureau Vintage 2025 population estimates, January 27, 2026
- Dutch Bros second-quarter 2026 results release, August 5, 2026
- Monthly share prices for Starbucks, October 31, 2026
About this page
Brief Equity and its team hold no position in Starbucks (SBUX) as of October 31, 2026.
This page is research, not investment advice. It describes one model and the assumptions behind it, and market data is delayed. Read how these models are built and our editorial policy.
Related guides: How to value a stock yourself (without Excel), How to write an investment thesis.