Valuation · EV/EBITDA model
Is Quest Diagnostics (DGX) stock undervalued?
Brief Equity's EV/EBITDA model of Quest Diagnostics, built on October 25, 2026 with the shares at $241.89, reaches a target of about $355 for 2028. On that model the stock looks undervalued, provided demand from an aging population and from new tests keeps revenue growing at 5.5% to 6.5% a year after 2026, once the boost from two large partnerships is lapped.
By The Brief Equity Team · Model dated · Published
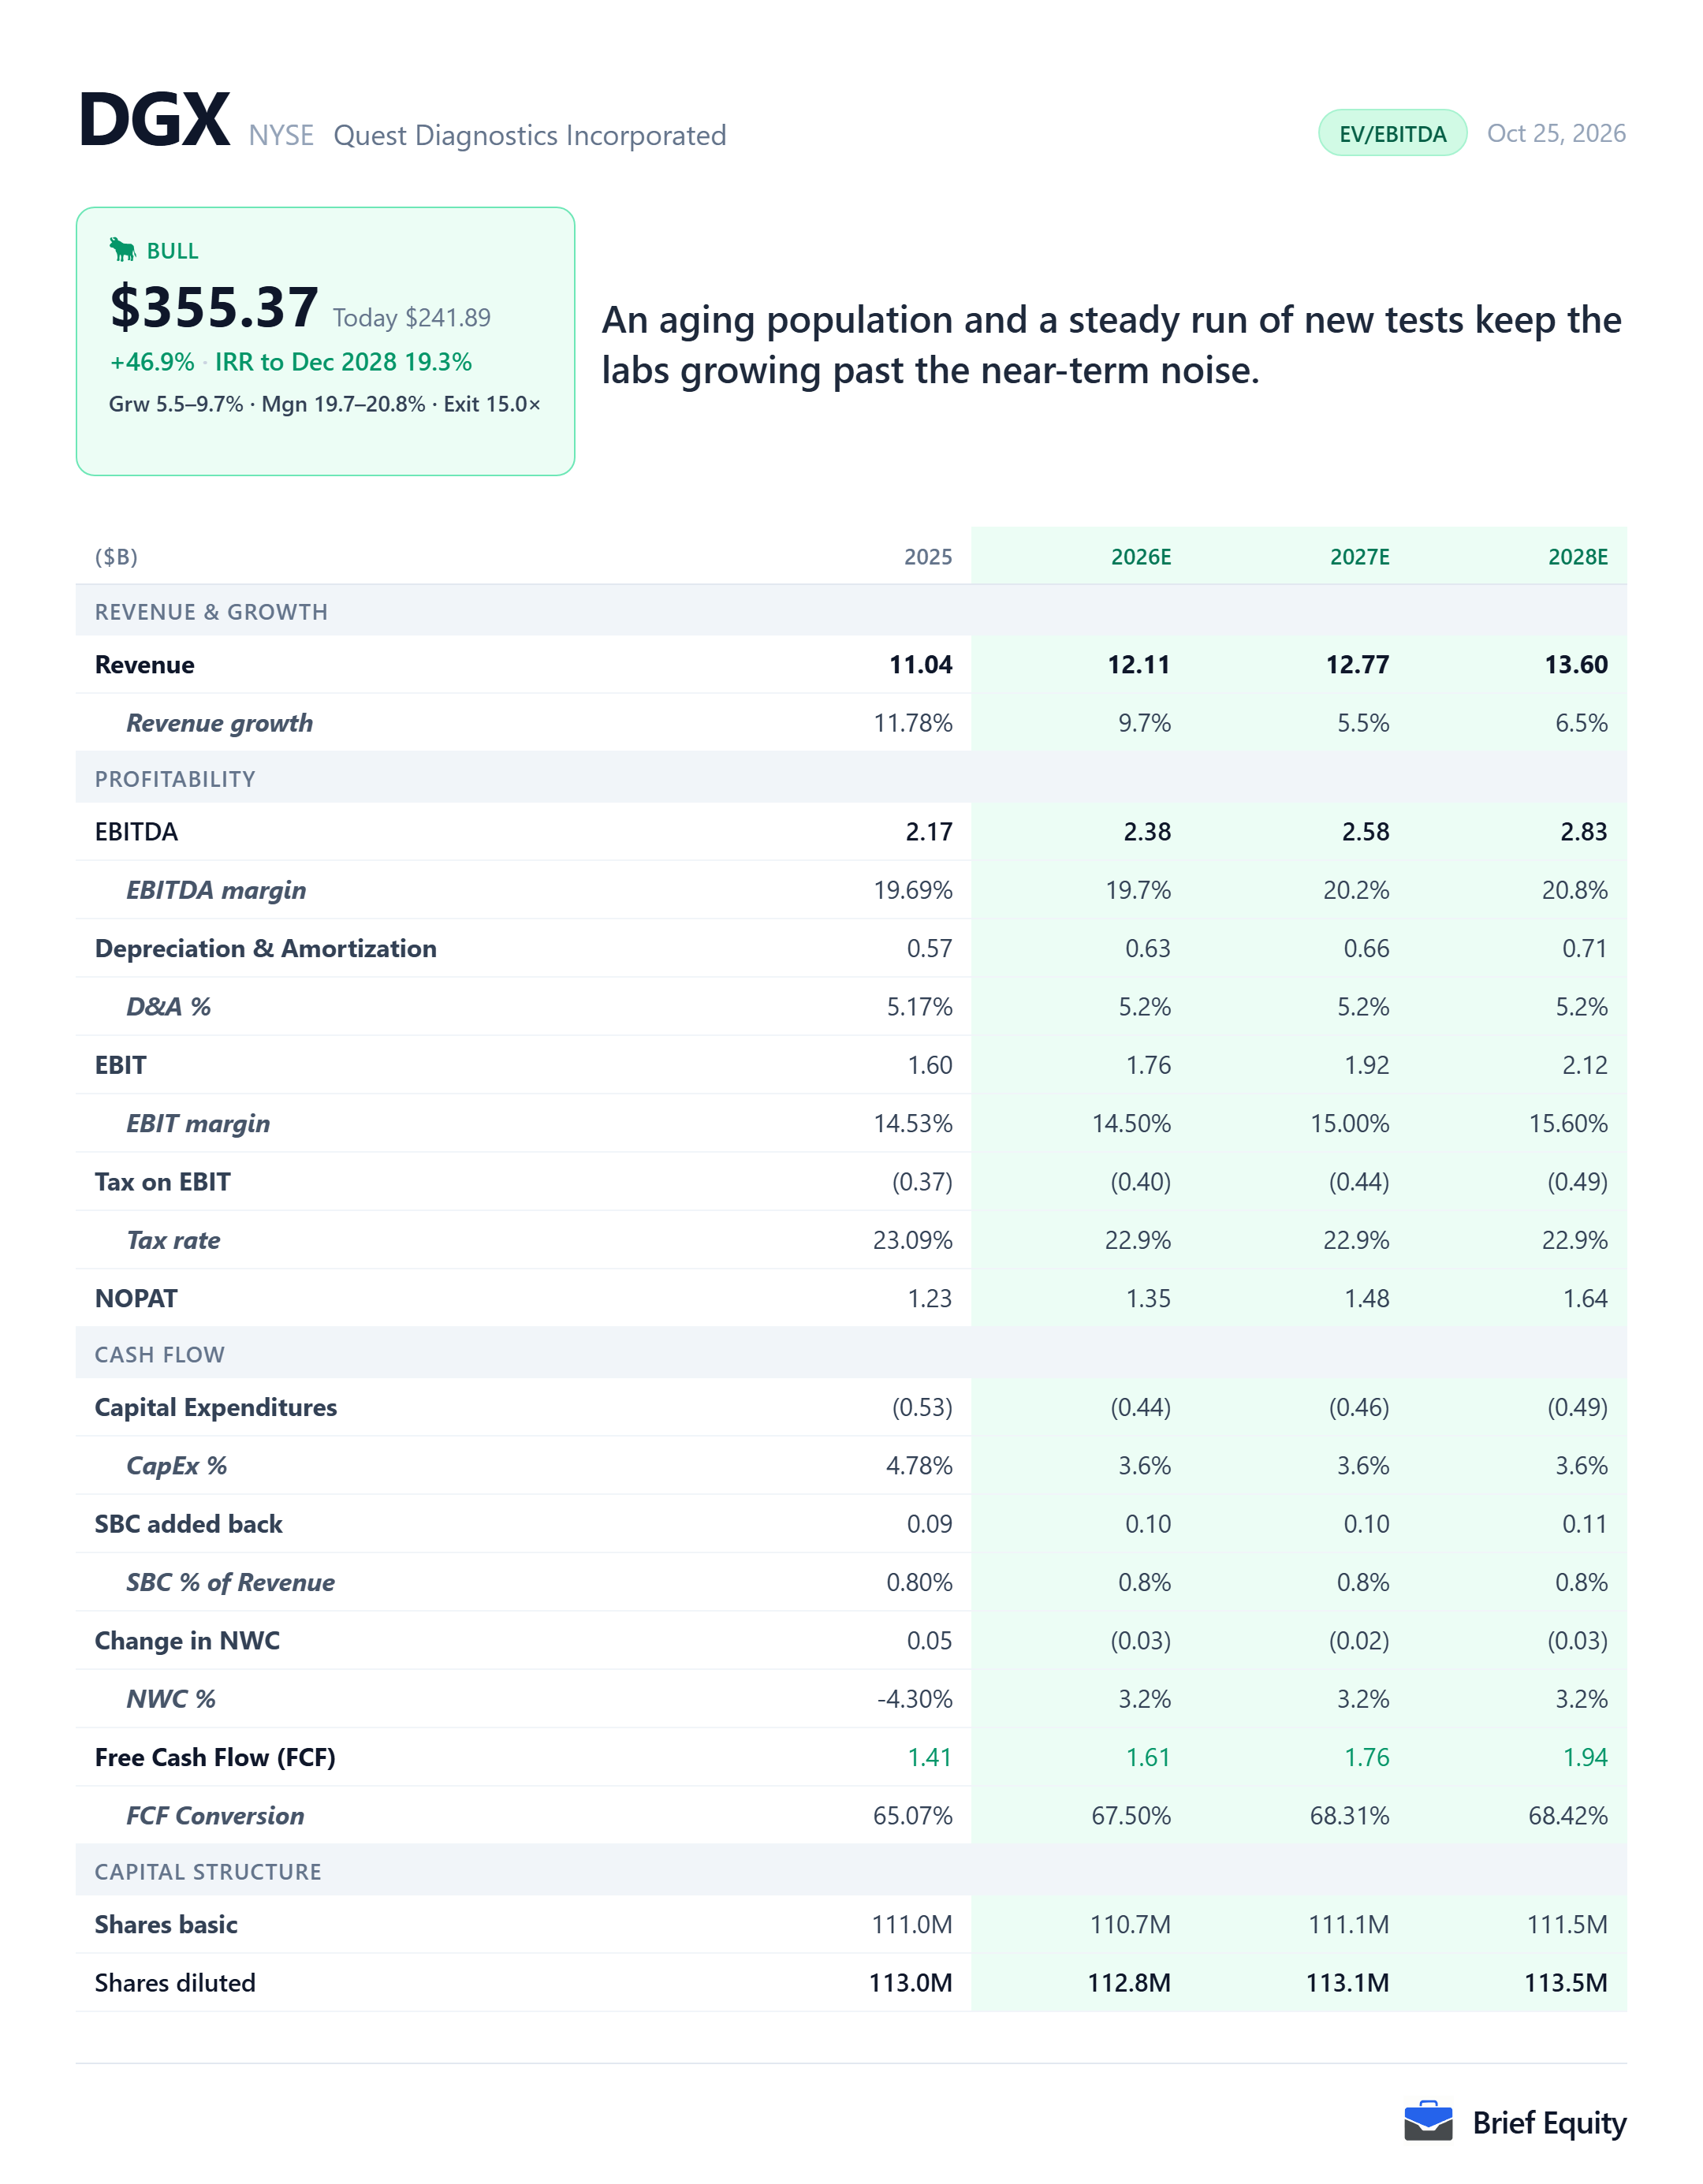
The model's assumptions for Quest Diagnostics
Quest Diagnostics is valued here with a quick model that projects 2026 to 2028 and applies 15 times EBITDA at the end of 2028. The first table holds the model's revenue and EBITDA, and the second sets its revenue beside the analyst consensus.
| 2026 | 2027 | 2028 | |
|---|---|---|---|
| Revenue, model | 12.11 | 12.77 | 13.60 |
| Revenue growth, model | 9.7% | 5.5% | 6.5% |
| EBITDA, model | 2.38 | 2.58 | 2.83 |
| EBITDA margin, model | 19.7% | 20.2% | 20.8% |
| 2026 | 2027 | 2028 | |
|---|---|---|---|
| Revenue, model | 12.11 | 12.77 | 13.60 |
| Revenue, analyst consensus | 12.08 | 12.62 | 13.15 |
Why Quest Diagnostics looks undervalued
Quest Diagnostics ties its organic growth to the care needs of an aging population and to the growing number of people focused on prevention and wellness, as its chief executive said on the third-quarter 2026 earnings call.
“Our robust organic revenue growth demonstrates that our solutions are fulfilling the expanding clinical care needs of an aging population, as well as the increasing number of people focused on prevention and wellness.”
Jim Davis, Chairman, Chief Executive Officer and President, Quest Diagnostics third-quarter 2026 earnings call, October 22, 2026
Quest Diagnostics' newer tests already show in its revenue. A group of its specialty tests in five clinical areas, among them brain health, cardiometabolic and oncology, generated over $1 billion of revenue in 2025 on double-digit growth, and the chief financial officer said each requisition now carries about 4.5 tests, against 3.5 to 4 before COVID.
Quest Diagnostics' brain health tests were growing at high double-digit rates in mid-2026, and the chief executive said most of its Alzheimer's testing is for patients above 60. The Census Bureau's main projection, released in November 2023, has people aged 65 or older outnumbering those under 18 from 2029.
Quest Diagnostics also grows through acquisitions. In 2024 it acquired LifeLabs in Canada and the outreach laboratory businesses of Allina Health, OhioHealth and University Hospitals, and in 2025 recent acquisitions added approximately 6.7 percentage points to the 12.2% revenue growth of Diagnostic Information Services, its laboratory testing business. On the third-quarter call the chief executive said that serving half of the nation's hospitals each year fuels a pipeline of potential collaborations and outreach acquisitions, and Quest Diagnostics expects to close a purchase of outreach laboratory assets from a health system in the Northeastern United States later in 2026.
Quest Diagnostics guides 2026 revenue growth of 9.3% to 9.7%, and the company puts roughly 3 points of it down to its Corewell Health and Fresenius partnerships, and without them third-quarter volume grew 5%. The model's growth is 5.5% in 2027 and 6.5% in 2028, against analyst consensus of 4.5% and 4.2%, with the EBITDA margin rising from 19.7% to 20.8%. At 15 times EBITDA that gives a target of about $355 for 2028, about 47% above the price on the model's date.
Quest Diagnostics faces short-term risks. It estimates the Medicare laboratory fee reset at about 1% of its 2027 revenue unless Congress delays it again, it expects more spending on its laboratory systems overhaul in 2027, and it found unauthorized access to one of its test-ordering systems on October 21, 2026 that affected patient records, with no count yet given.
What has to be true, and what would break it
Quest Diagnostics' target rests on demand that keeps growing after 2026, and on margins that keep rising while it does.
What has to be true
- Volume outside the Corewell Health and Fresenius partnerships keeps growing near the 5% Quest Diagnostics reported for the third quarter of 2026 once those partnerships are lapped.
- Specialty tests, the brain health tests among them, keep growing at double-digit rates.
- The EBITDA margin rises from 19.7% in 2026 to 20.8% in 2028.
- Buyers pay 15 times EBITDA for the business at the end of 2028.
What would break it
- Growth after 2026 settles at the 4.5% and 4.2% of the analyst consensus.
- The Medicare laboratory fee reset takes effect in 2027 with little offset.
- Spending on the laboratory systems overhaul in 2027 holds the margin down.
- The October 2026 breach of a test-ordering system turns out to be large.
The parts of Quest Diagnostics's business
Quest Diagnostics' revenue is nearly all Diagnostic Information Services, its laboratory testing business and its one reportable segment, which also accounted for all of its 2025 growth. Diagnostic Solutions is the rest.
| Share of revenue | Share of revenue growth | |
|---|---|---|
| Diagnostic Information Services | 97.7% | 100.7% |
| Diagnostic Solutions | 2.3% |
Quest Diagnostics beside its peers
Quest Diagnostics is compared here with five companies: its closest laboratory rival, three makers of newer specialty tests, and an outpatient imaging business.
- LH: The same laboratory testing business, for physicians, hospitals and health plans
- NTRA: Newer tests: prenatal screening and cancer recurrence
- GH: Newer tests: cancer blood tests and screening
- VCYT: Newer tests: specialty cancer diagnostics
- RDNT: Outpatient diagnostic imaging, a diagnostic services business beside laboratory testing
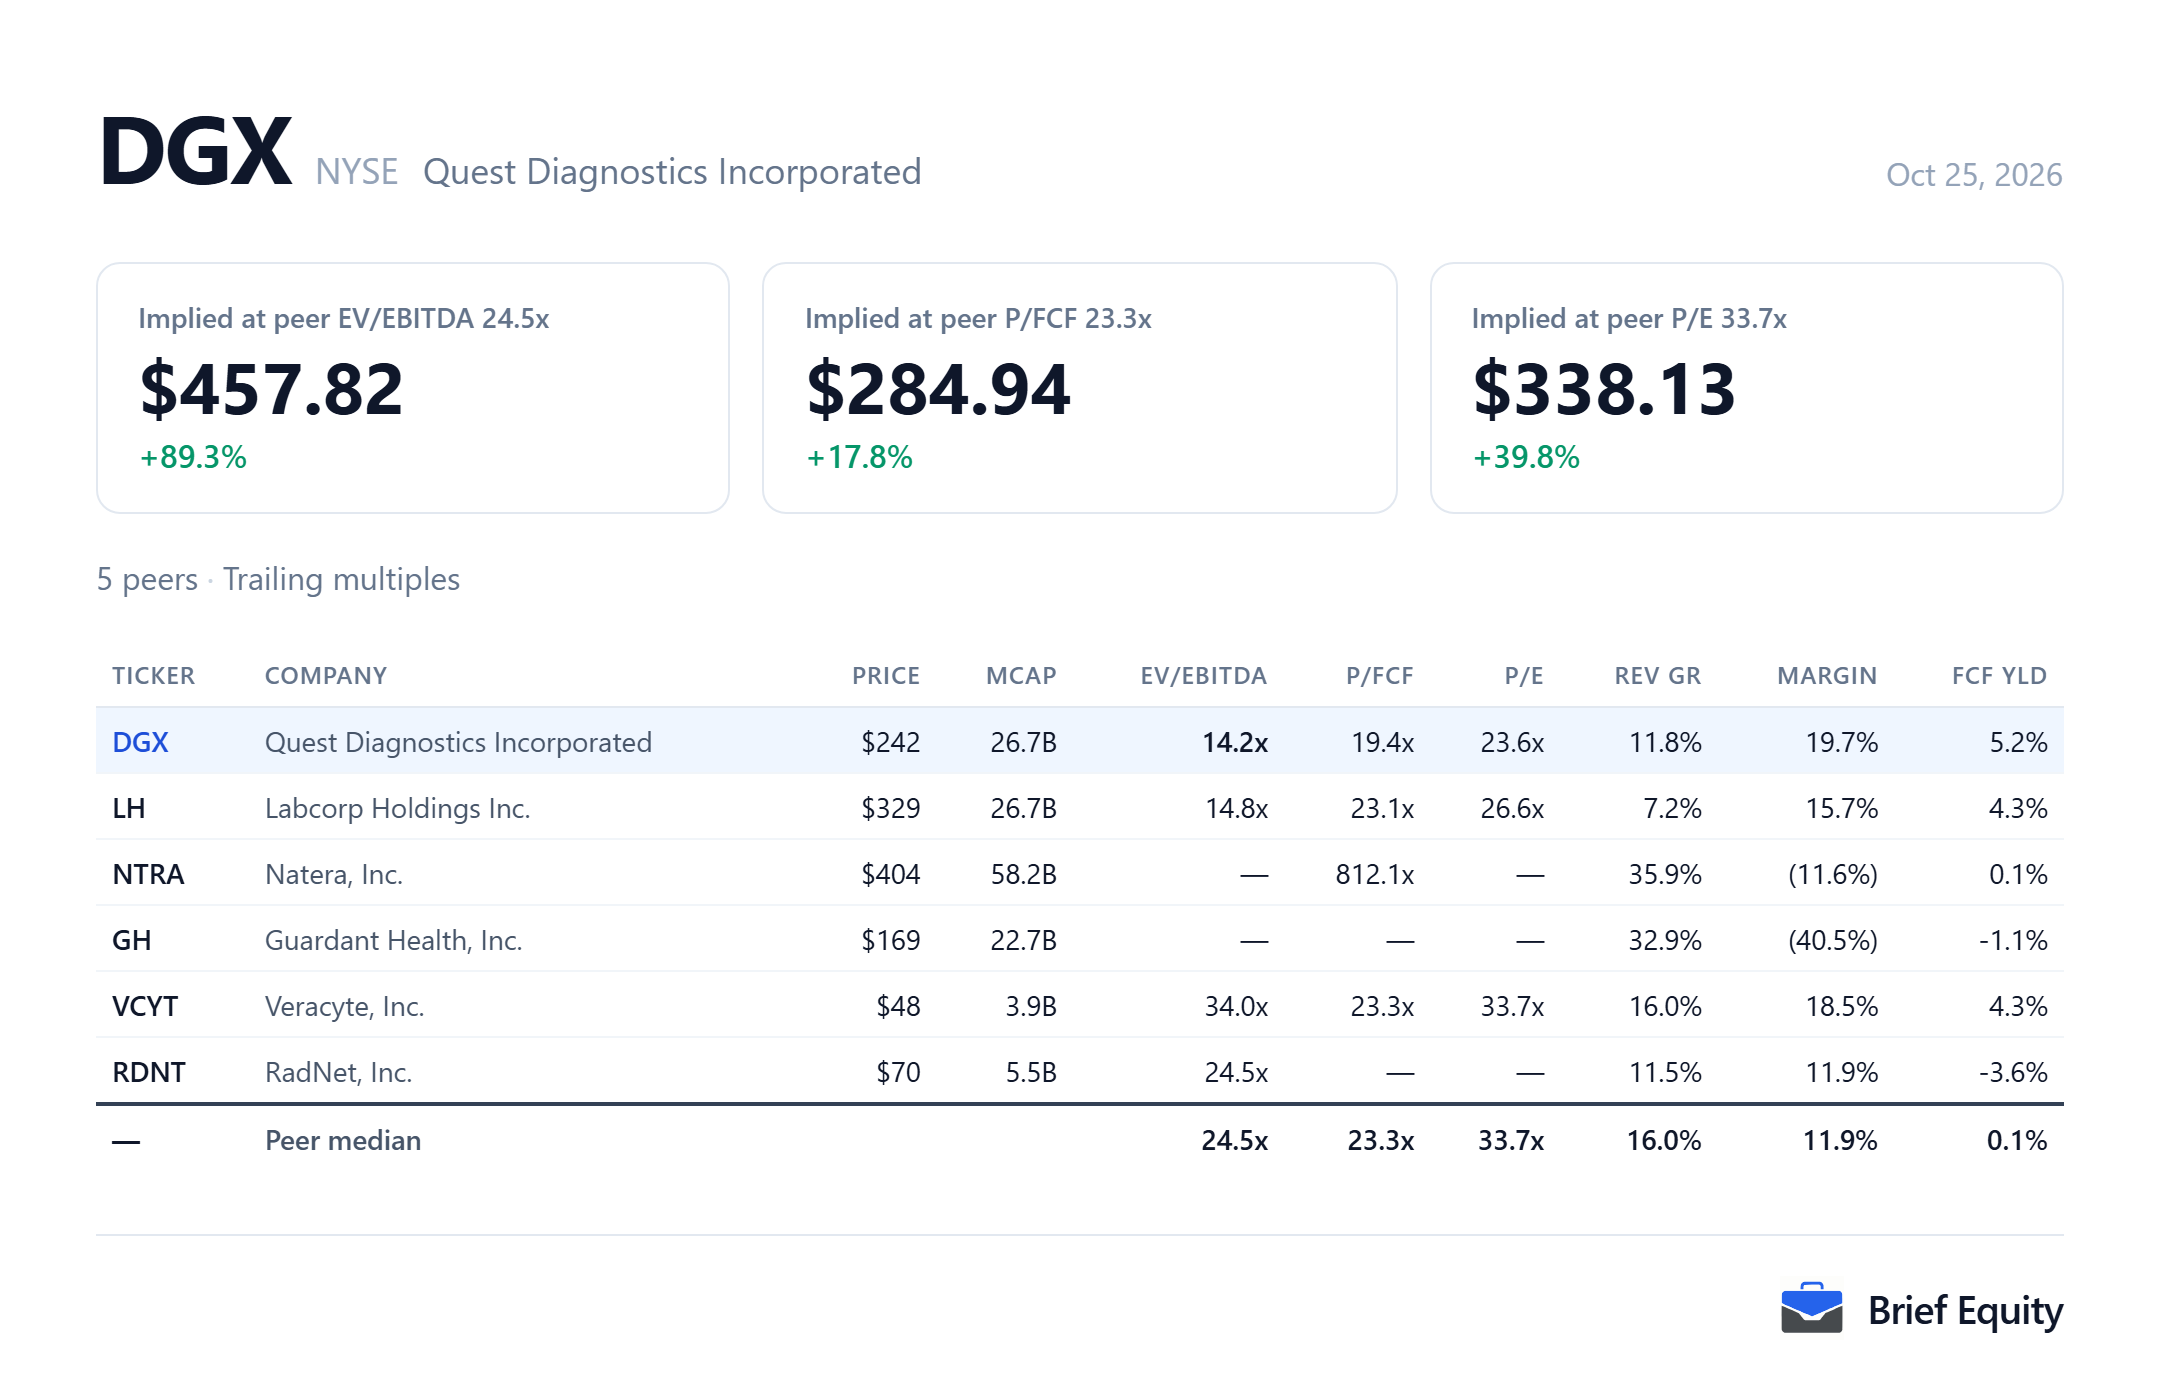
How the estimate moves with its assumptions
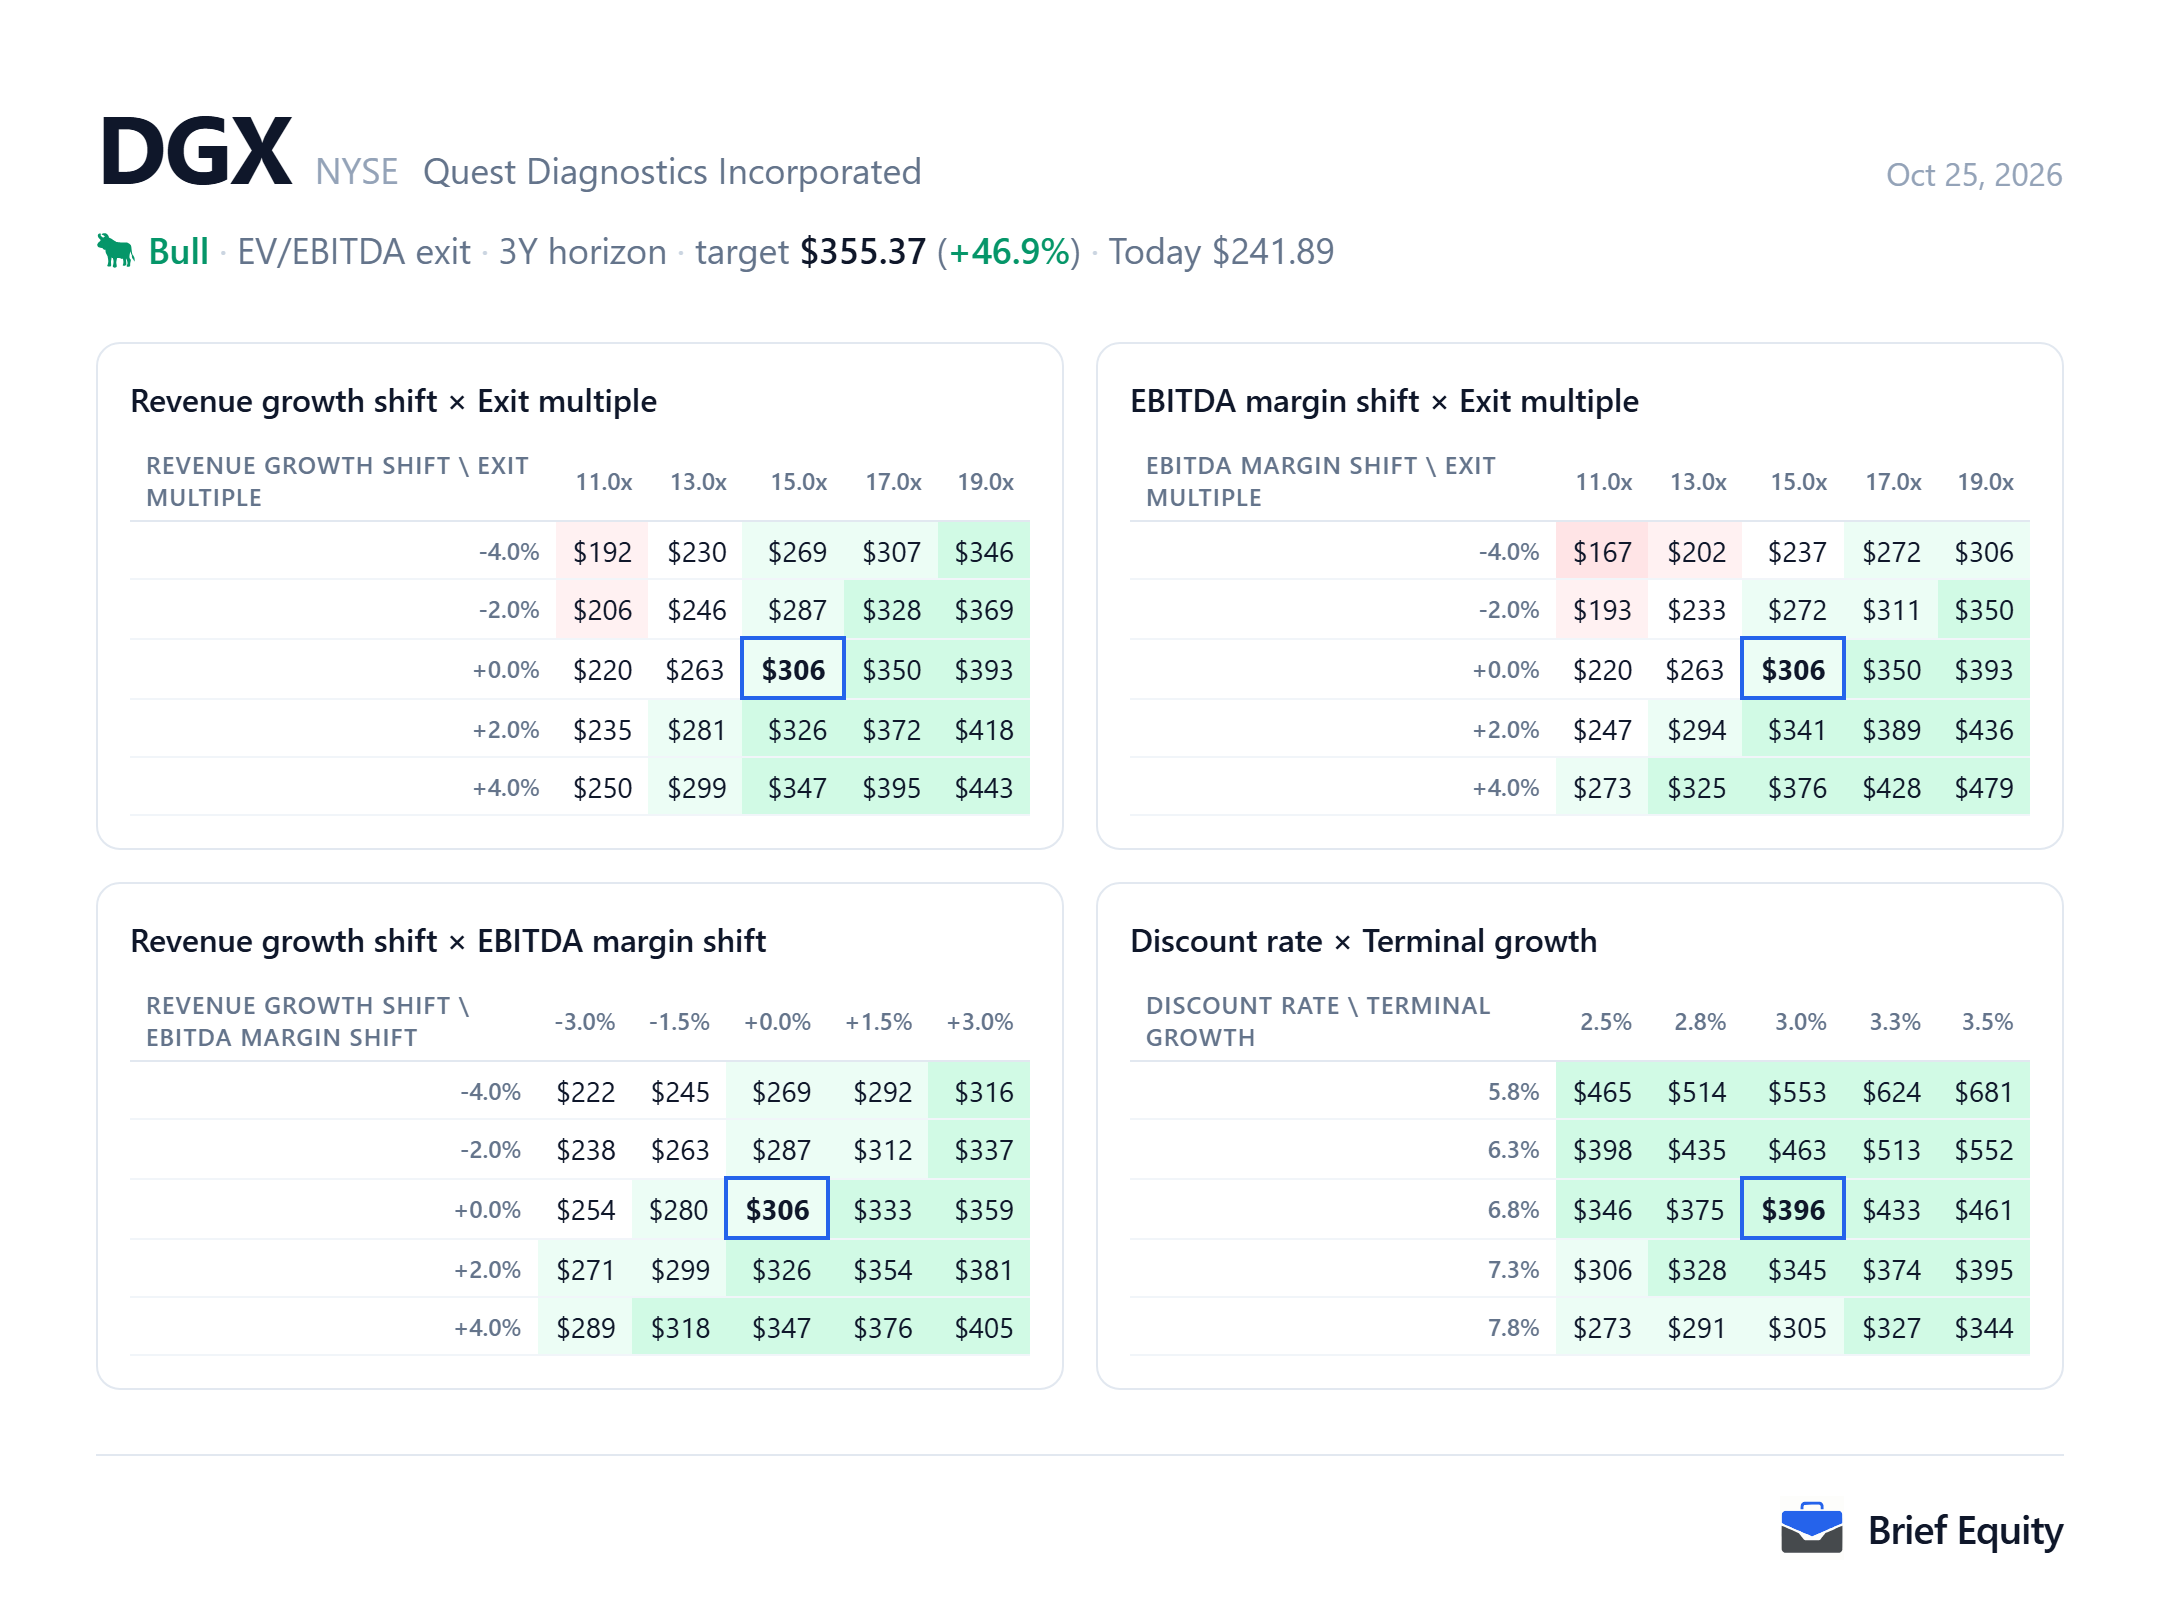
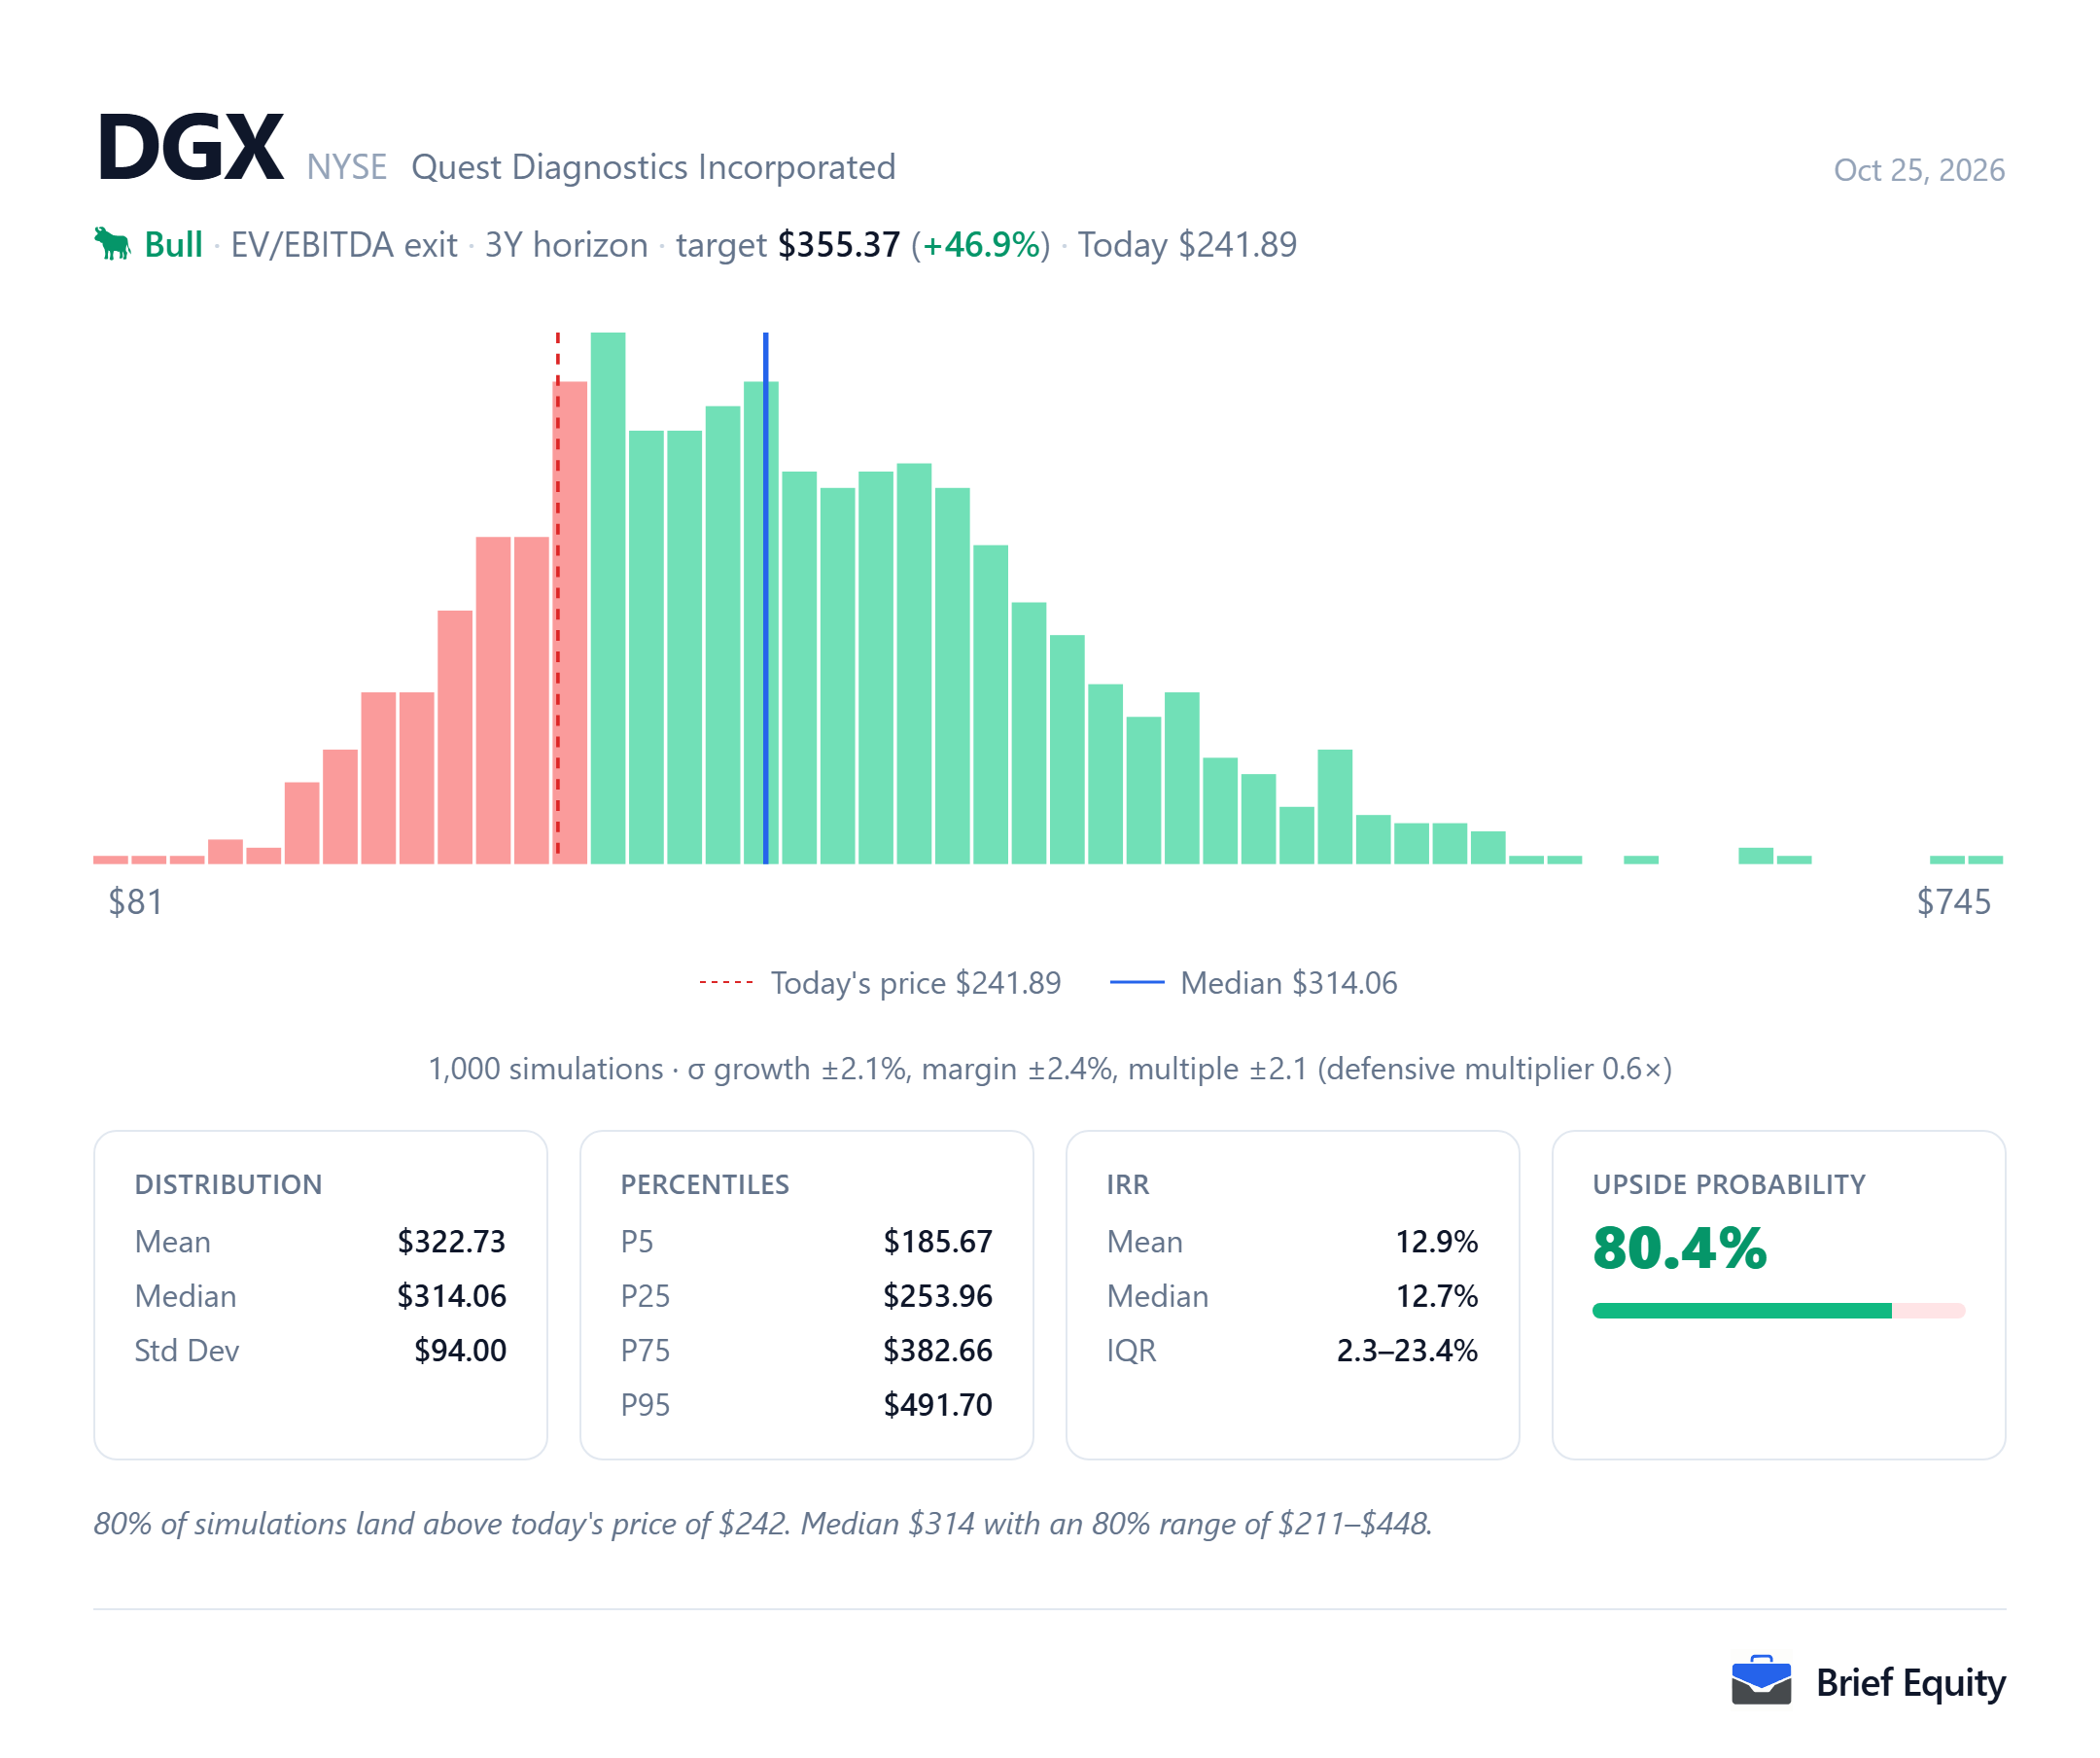
Quest Diagnostics' estimate moves when its assumptions do, and the two pictures below show by how much. One changes two assumptions at a time, and the other runs the model many times with its main inputs drawn at random.
Questions about Quest Diagnostics
These questions about Quest Diagnostics (DGX) are answered from the documents listed under Sources.
- How much of Quest Diagnostics' 2025 revenue growth was organic?
- Quest Diagnostics' net revenues rose 11.8% in 2025, and organic growth was 5.3%.
- Does Quest Diagnostics have preferred stock outstanding?
- As of its 2025 annual report, Quest Diagnostics could issue up to 10 million preferred shares and had none outstanding.
- How much cash does Quest Diagnostics expect to generate from operations in 2026?
- In October 2026 Quest Diagnostics raised its 2026 guide for cash provided by operations to approximately $1.90 billion, from approximately $1.80 billion.
- What is Project Nova?
- Project Nova is Quest Diagnostics' rebuild of its order-to-cash systems, which its 2025 annual report put at approximately $250 million to $310 million of cash with the final phases in 2031 to 2032.
- How much of Quest Diagnostics' revenue comes from Medicaid and ACA exchange plans?
- Medicaid and managed Medicaid were approximately 8% of Quest Diagnostics' 2025 revenue, and ACA exchange plans less than 5%.
Sources
The quotations and facts about Quest Diagnostics (DGX) on this page rest on the documents below.
- Quest Diagnostics annual report (Form 10-K) for 2025, February 26, 2026
- Quest Diagnostics third-quarter 2026 earnings release, October 22, 2026
- Quest Diagnostics third-quarter 2026 earnings call, October 22, 2026
- Quest Diagnostics second-quarter 2026 earnings call, July 23, 2026
- U.S. Census Bureau, 2023 National Population Projections, November 9, 2023
- MedTech Dive on the RESULTS Act and the 2027 PAMA cuts, September 25, 2026
- Quest Diagnostics current report (Form 8-K) on the Quanum LSM incident, October 22, 2026
- Quest Diagnostics notice on the Quanum LSM security incident, October 23, 2026
About this page
Brief Equity and its team hold no position in Quest Diagnostics (DGX) as of October 25, 2026.
This page is research, not investment advice. It describes one model and the assumptions behind it, and market data is delayed. Read how these models are built and our editorial policy.
Related guides: EV/EBITDA explained, What is enterprise value (EV), DCF explained (discounted cash flow).