Valuation · EV/EBITDA model
Is Generac (GNRC) stock undervalued?
On October 30, 2026, with the shares at $194.55, a quick EV/EBITDA model by Brief Equity valued Generac at about $463 for 2028. Generac looks undervalued on that model if its data center backlog turns into revenue as planned: the backlog reached approximately $4.5 billion on its third-quarter 2026 call, and some of its data center contracts carry cancellation rights.
By The Brief Equity Team · Model dated · Published
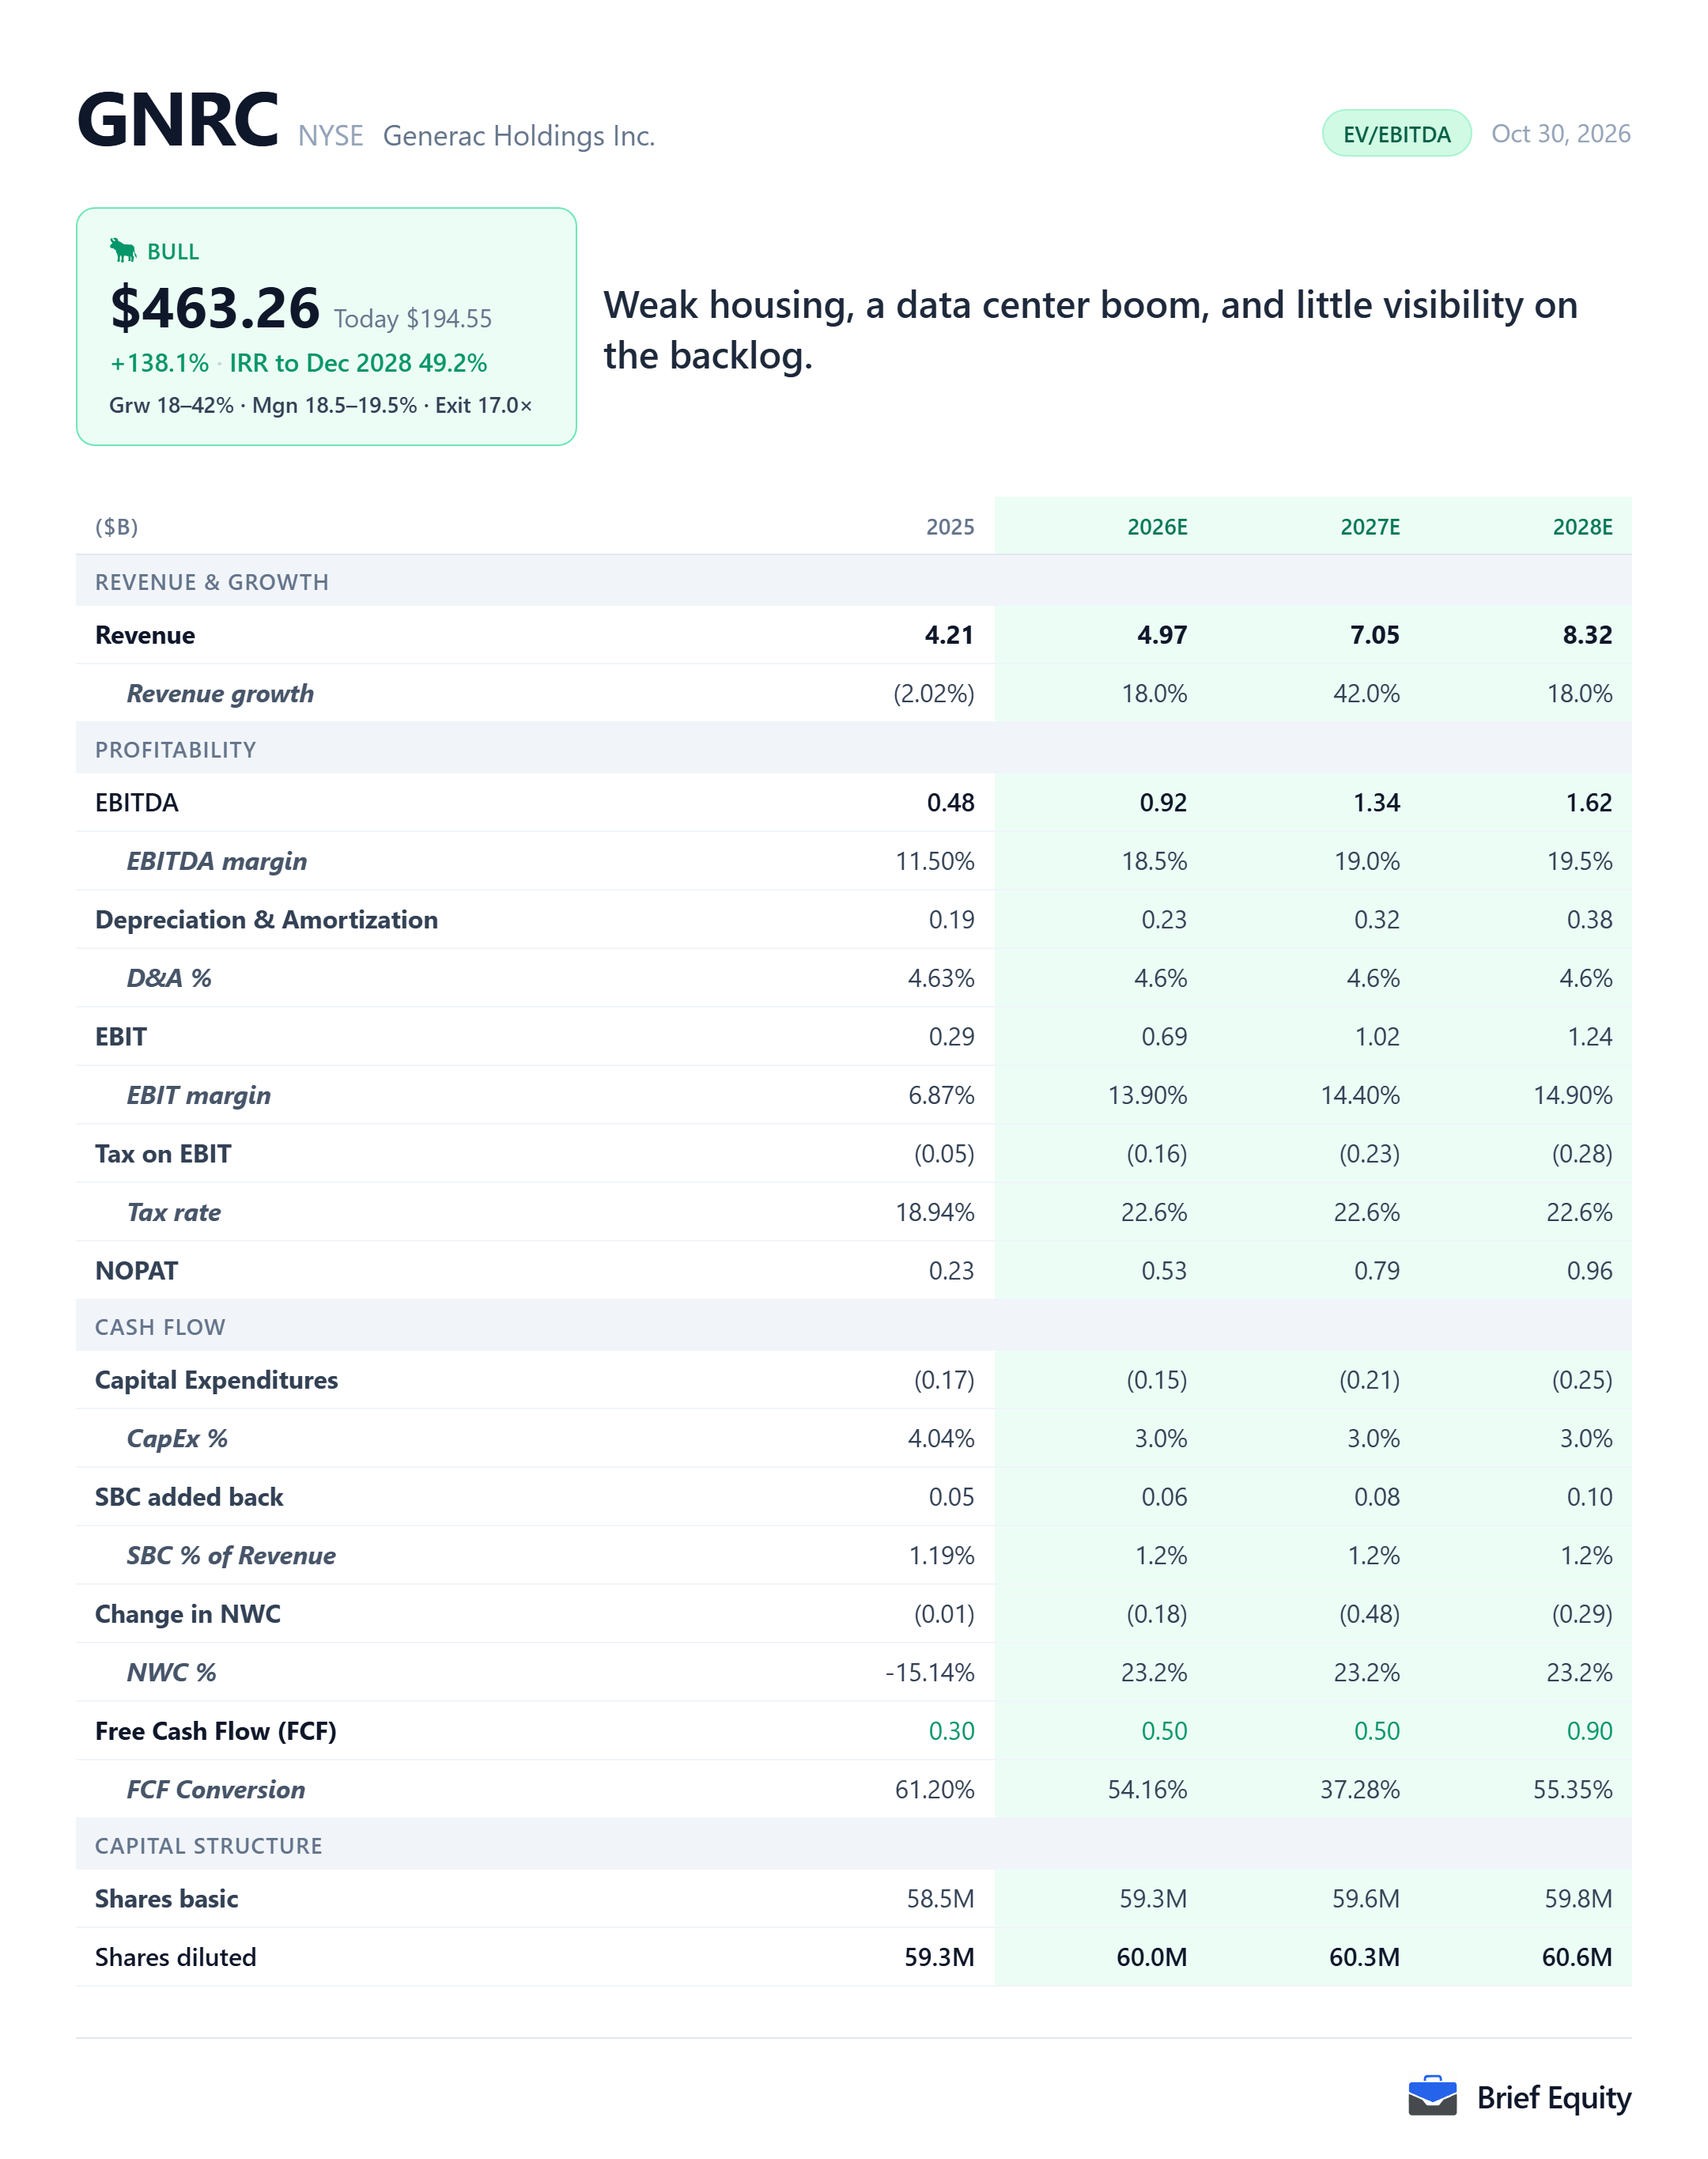
The model's assumptions for Generac
Generac's fiscal year is the calendar year, so each column below is one of the company's own years. The model runs three years, to 2028, and every row is the model's own except the analyst consensus revenue.
| 2026 | 2027 | 2028 | |
|---|---|---|---|
| Revenue, model | 4.97 | 7.05 | 8.32 |
| Revenue, analyst consensus | 4.93 | 6.86 | 8.01 |
| Revenue growth, model | 18.0% | 42.0% | 18.0% |
| EBITDA, model | 0.92 | 1.34 | 1.62 |
| EBITDA margin, model | 18.5% | 19.0% | 19.5% |
Why Generac looks undervalued
Generac's residential business leans on housing and on the weather: its 10-Q says residential housing starts can affect demand for its residential products. Its residential segment sales decreased approximately 2% to $621 million in the second quarter of 2026, when power outages were more than 30% below the long-term baseline average, and on that quarter's call the chief executive described fatigue among consumers.
“And when it comes to large ticket purchases, we're seeing softness in other parts of the economy.”
Aaron P. Jagdfeld, President and Chief Executive Officer, Generac second-quarter 2026 earnings call, July 29, 2026
Generac's residential segment sales then increased approximately 9% to $744 million in the third quarter of 2026, which the company attributed to more normalized outage activity.
Generac's data center business moves the other way. Its backlog for products sold to the data center market reached approximately $4.5 billion by the third-quarter 2026 call, from $1.6 billion 90 days earlier, after a supply agreement with Amazon whose initial deliveries are expected to total $2.4 billion in 2027 and 2028. That backlog is larger than Generac's 2025 net sales of $4.21 billion.
“that puts us kind of at a $7 billion clip for top line for net sales for next year as a company.”
Aaron Jagdfeld, President and Chief Executive Officer, Generac third-quarter 2026 earnings call, October 28, 2026
Brief Equity's model of Generac is a quick one, and it largely follows that framework. Revenue grows 18.0% in 2026, at the high end of Generac's guidance for growth in the mid-to-high teens percent, then 42.0% in 2027 and 18.0% in 2028, against 39.3% and 16.8% for analyst consensus in those years. At 17 times 2028 EBITDA, the model reaches about $463 a share for 2028.
Visibility into Generac's backlog is limited. Its 10-Q put the revenue it expects to recognize on remaining performance obligations at approximately $143 million as of June 30, 2026, against the $1.6 billion backlog management described on the second-quarter call, and its third-quarter release lists cancellation rights among the contract risks with certain data center customers. On the third-quarter call, the chief executive said the backlog holds nothing yet for its first hyperscale customer in 2028.
What has to be true, and what would break it
Generac looks undervalued on this model only if its data center backlog turns into revenue on the schedule management describes, while the residential business holds up.
What has to be true
- The data center backlog ships largely as booked in 2027 and 2028, without material cancellations.
- Generac's capacity for large generators grows as planned through 2027.
- New data center orders arrive in time to fill the larger capacity in 2028.
What would break it
- Data center customers cancel or delay orders under the rights their contracts carry.
- Residential sales fall again on weak outage activity and softer large purchases by households.
- The stock's multiple falls below 17 times EBITDA.
The parts of Generac's business
Generac reported its 2025 net sales by product class. In 2025 residential products were 53.9% of Generac's net sales; its revenue fell that year, so no part's share of growth is shown.
| Share of revenue | |
|---|---|
| Residential products | 53.9% |
| Commercial & Industrial products | 34.6% |
| Other products and services | 11.5% |
Generac beside its peers
Generac is compared here with eight US-listed companies, chosen to cover both its data center business and its residential business.
- CAT: Data center generators, the largest incumbent
- CMI: Standby generators, a direct competitor
- VRT: Data center power equipment
- ETN: Data center electrical equipment
- LII: Residential equipment tied to housing
- AOS: Residential replacement equipment
- WHR: Large household purchases
- PNR: Residential pool and water equipment
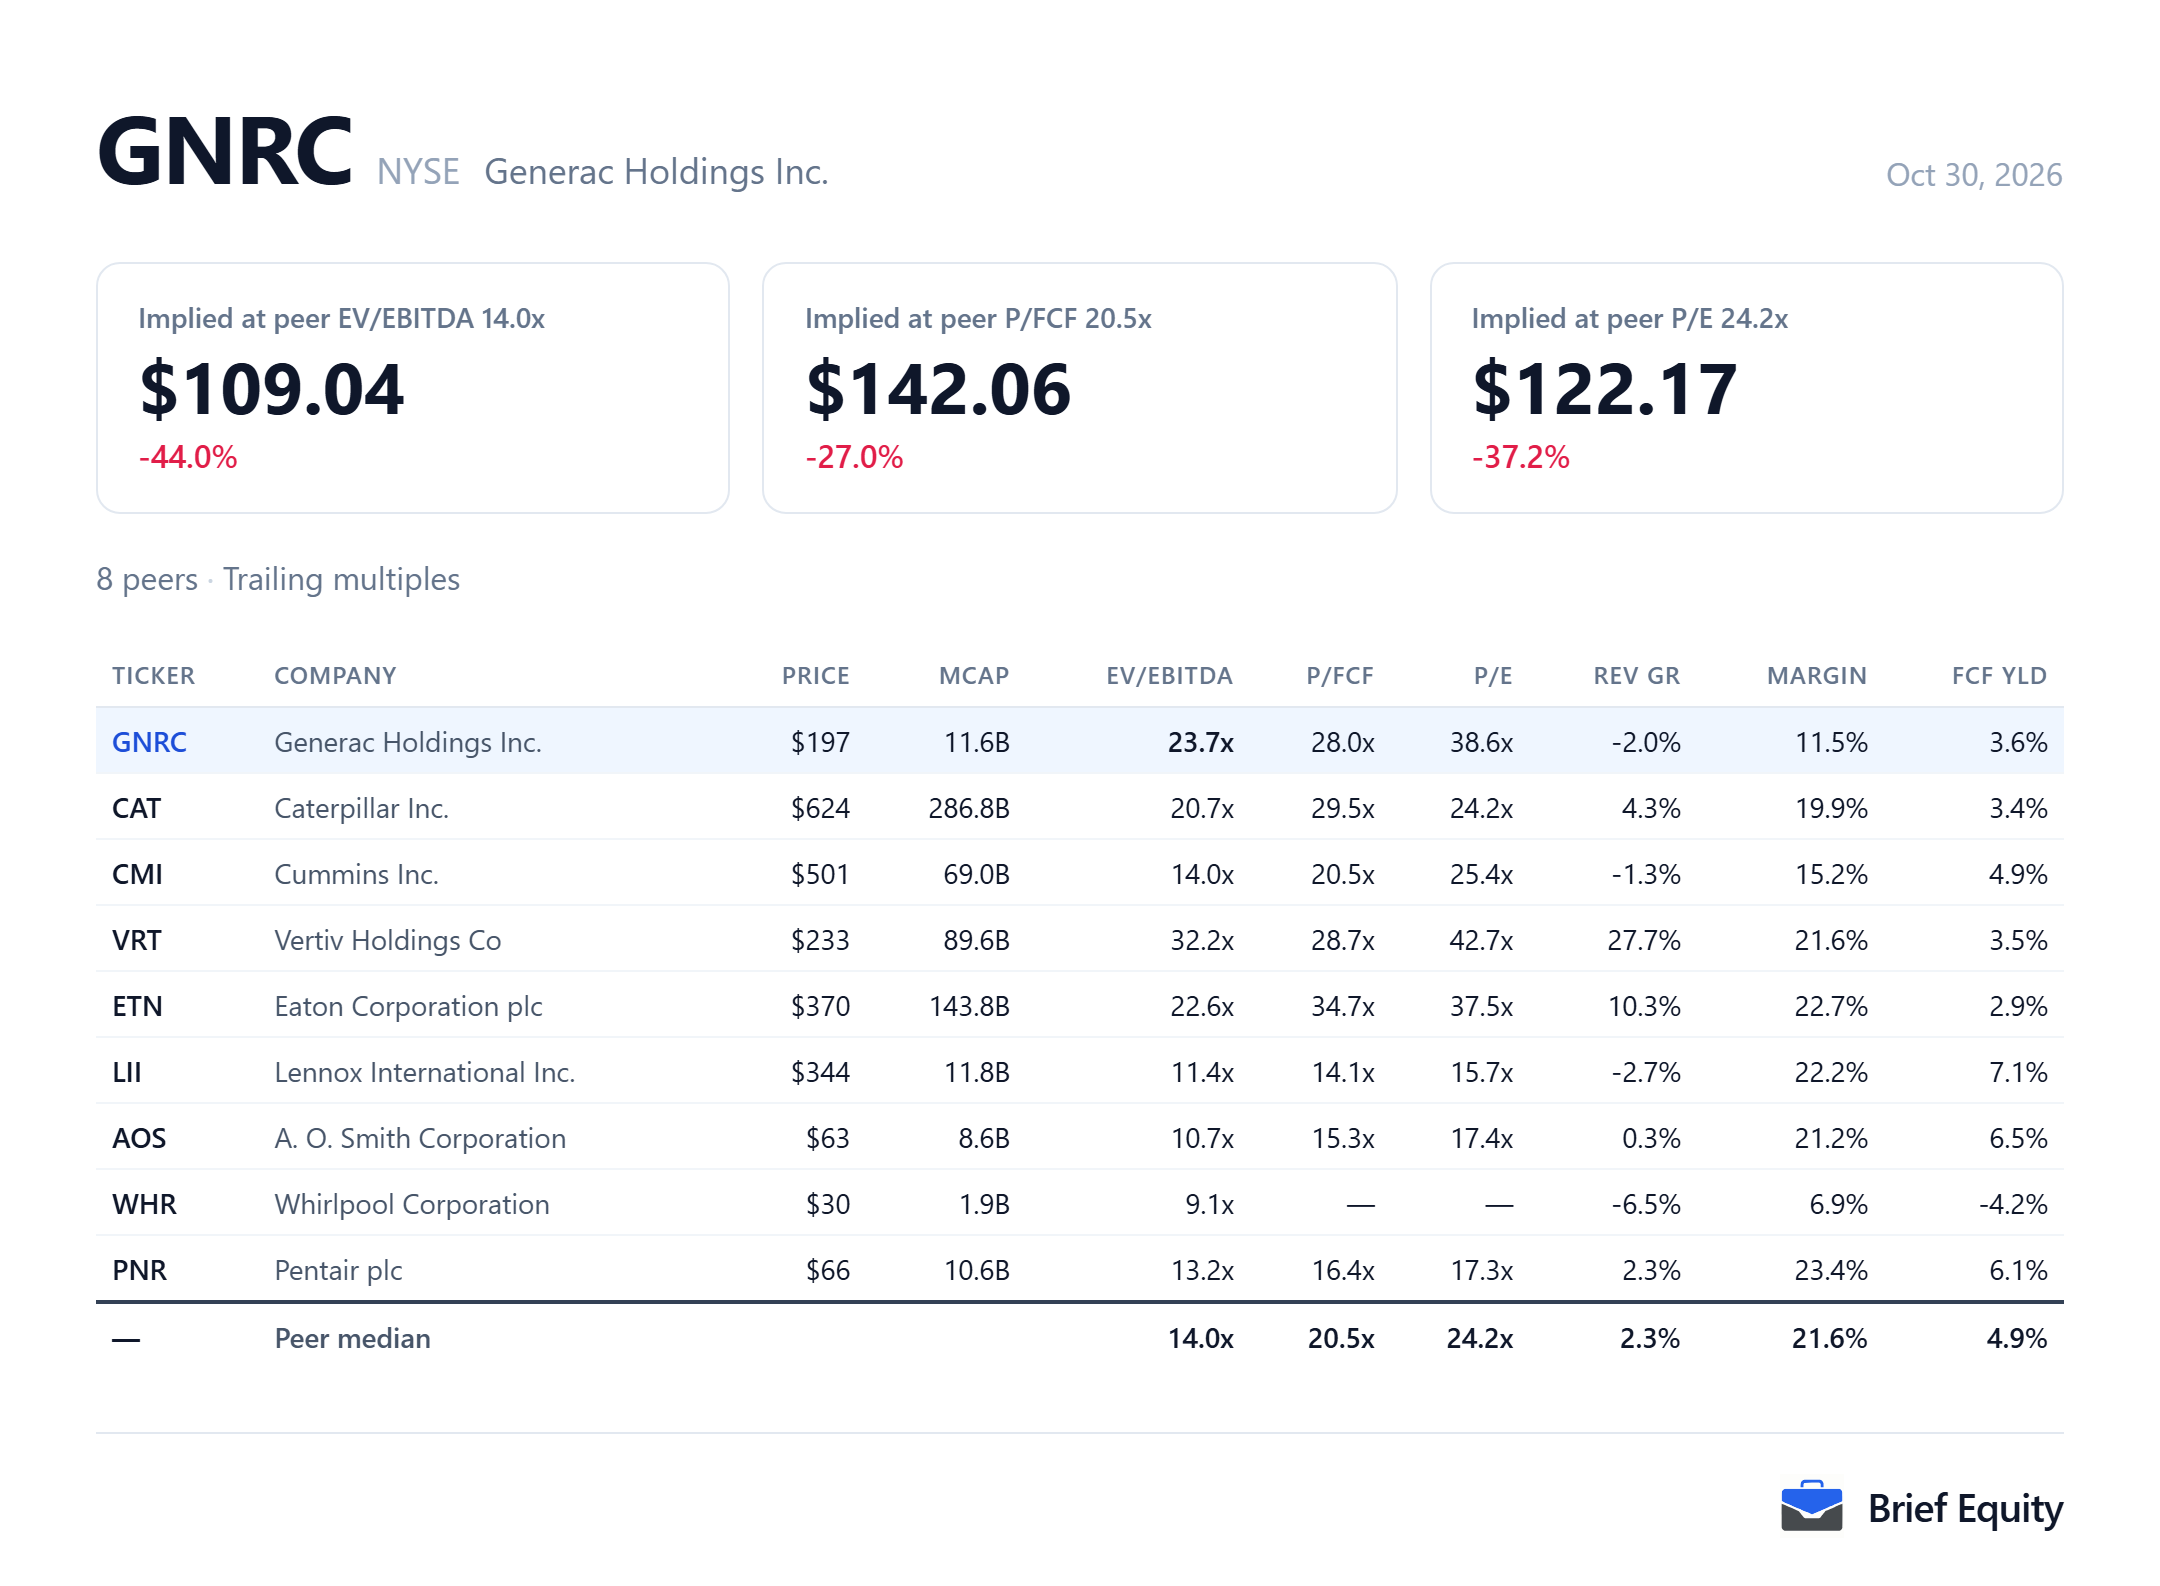
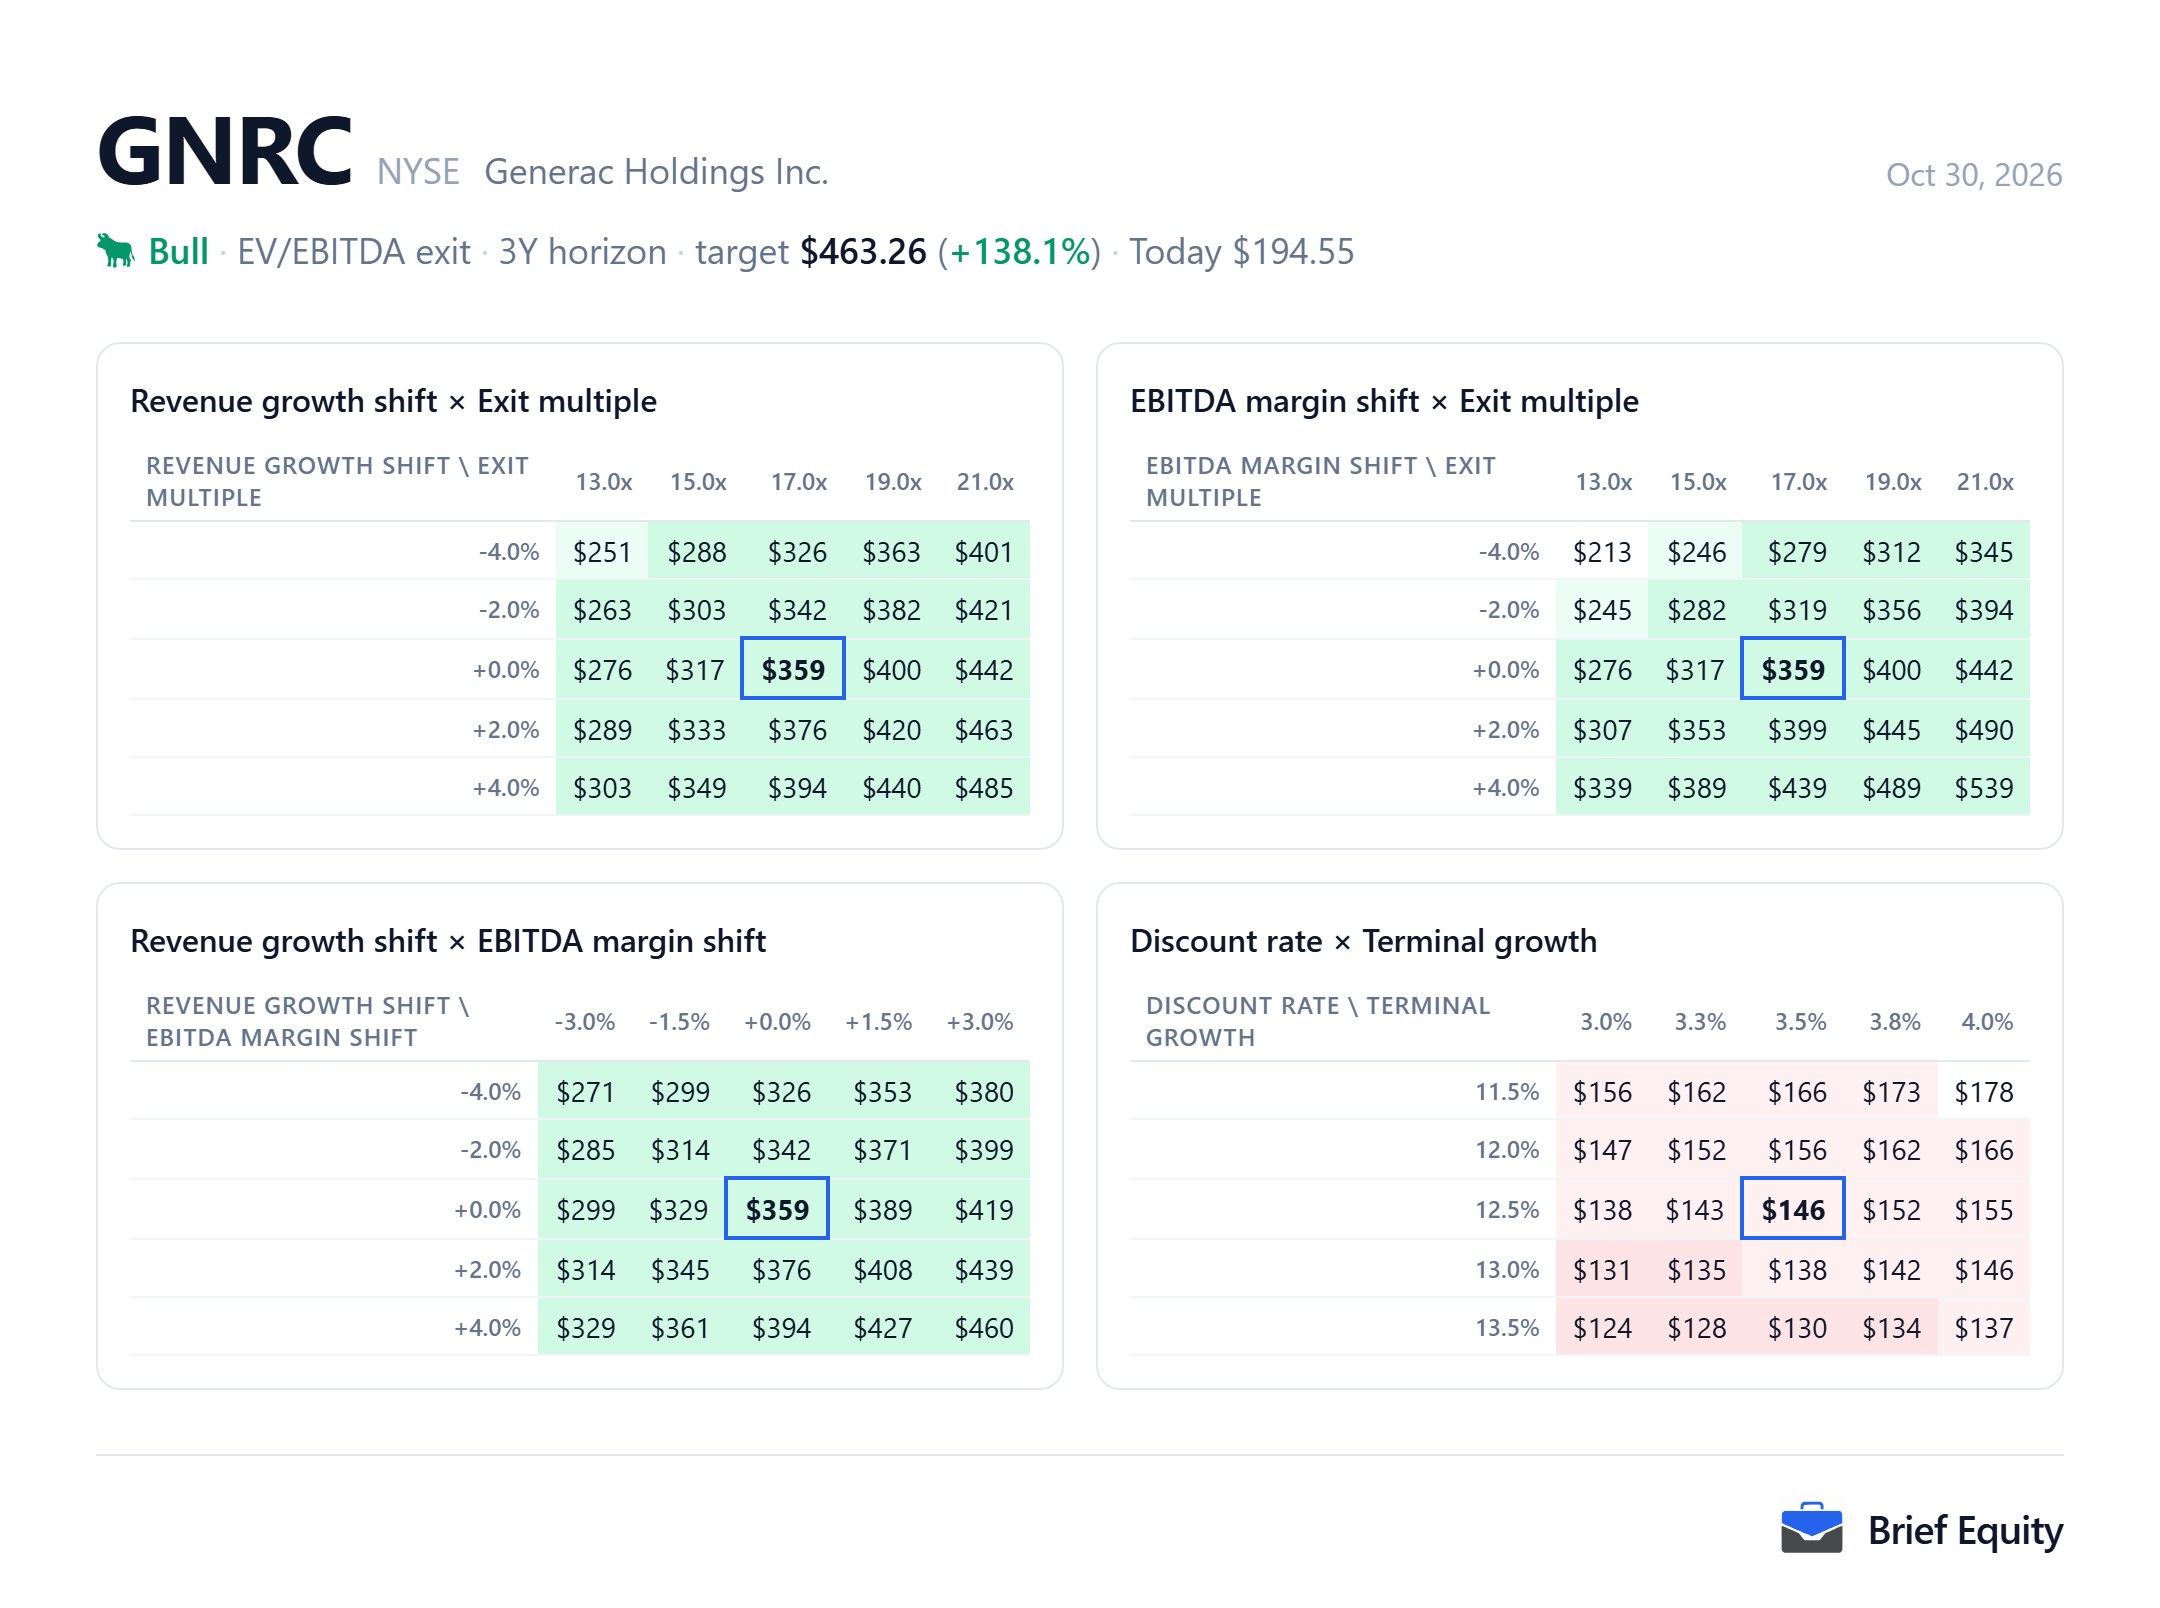
How the estimate moves with its assumptions
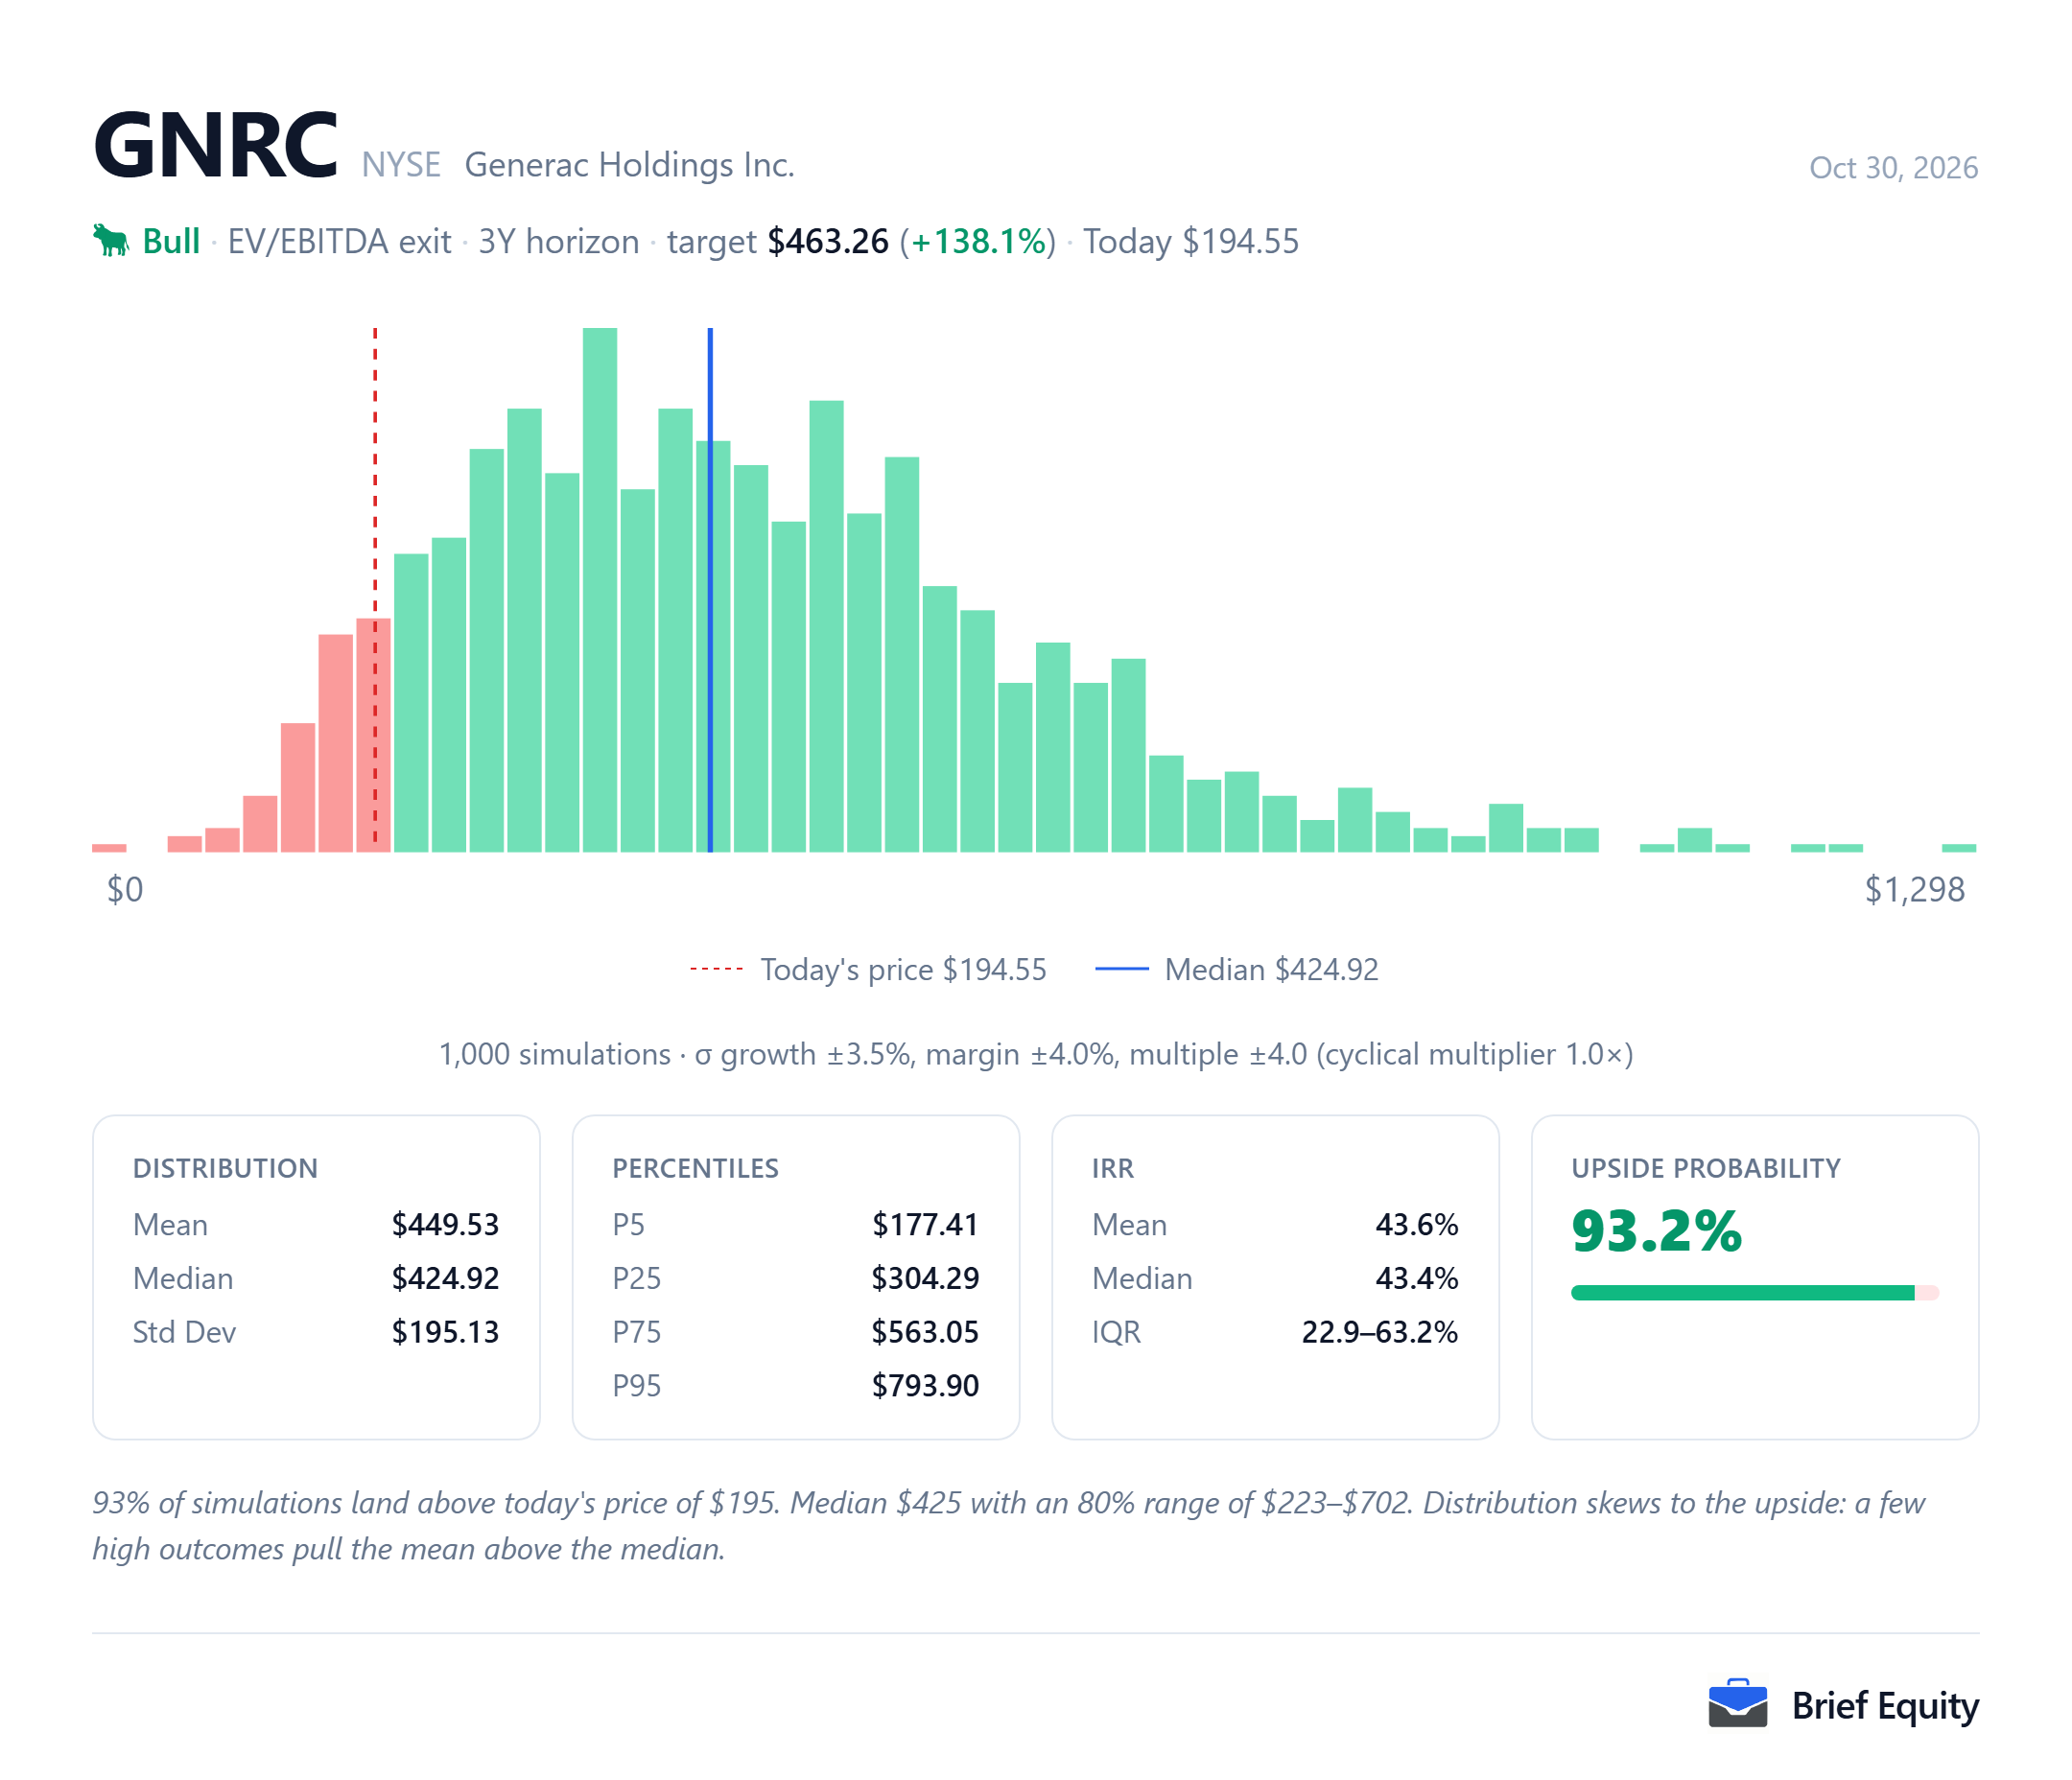
The two pictures below show how far the Generac estimate moves when its assumptions change: one moves two assumptions at a time, and the other runs the model many times with growth, margin and the exit multiple drawn at random.
Questions about Generac
These questions about Generac (GNRC) are answered from the documents listed under Sources.
- What sales growth does Generac expect for 2026?
- On October 28, 2026, Generac maintained its guidance for full-year 2026 net sales growth in the mid-to-high teens percent range, including an approximate 2% favorable impact from foreign currency, acquisitions and divestitures.
- How much free cash flow does Generac expect for 2026?
- On its third-quarter 2026 call, Generac said it expects free cash flow of approximately $450 million for the full year 2026, up from approximately $350 million on its second-quarter call.
- What warrant did Generac issue to Amazon?
- In September 2026 Generac issued Amazon a warrant to acquire up to 1,693,745 shares at an exercise price of $200.9266 per share, with 307,954 shares vesting immediately and the rest vesting against Amazon's payments for backup generators of up to $8 billion.
Sources
The quotations and facts about Generac (GNRC) on this page rest on the documents below.
- Generac third-quarter 2026 results release, October 28, 2026
- Generac third-quarter 2026 earnings call, October 28, 2026
- Generac second-quarter 2026 earnings call, July 29, 2026
- Generac Form 10-Q for the quarter ended June 30, 2026, August 4, 2026
- Generac Form 10-K for the year ended December 31, 2025, February 18, 2026
- Generac Form 8-K on its agreement with Amazon, September 16, 2026
About this page
Brief Equity and its team hold no position in Generac (GNRC) as of October 30, 2026.
This page is research, not investment advice. It describes one model and the assumptions behind it, and market data is delayed. Read how these models are built and our editorial policy.
Related guides: EV/EBITDA explained, What is enterprise value (EV).