Valuation · EV/EBITDA model
Is Dollarama (DOL.TO) stock overvalued?
Brief Equity's EV/EBITDA model of Dollarama (DOL.TO), dated October 19, 2026, values the shares at CAD 255 by fiscal 2029, about 24% above the CAD 205.32 share price on that date. Even so, the stock looks expensive if slower population growth in Canada starts to show up in Dollarama's store traffic.
By The Brief Equity Team · Model dated · Published
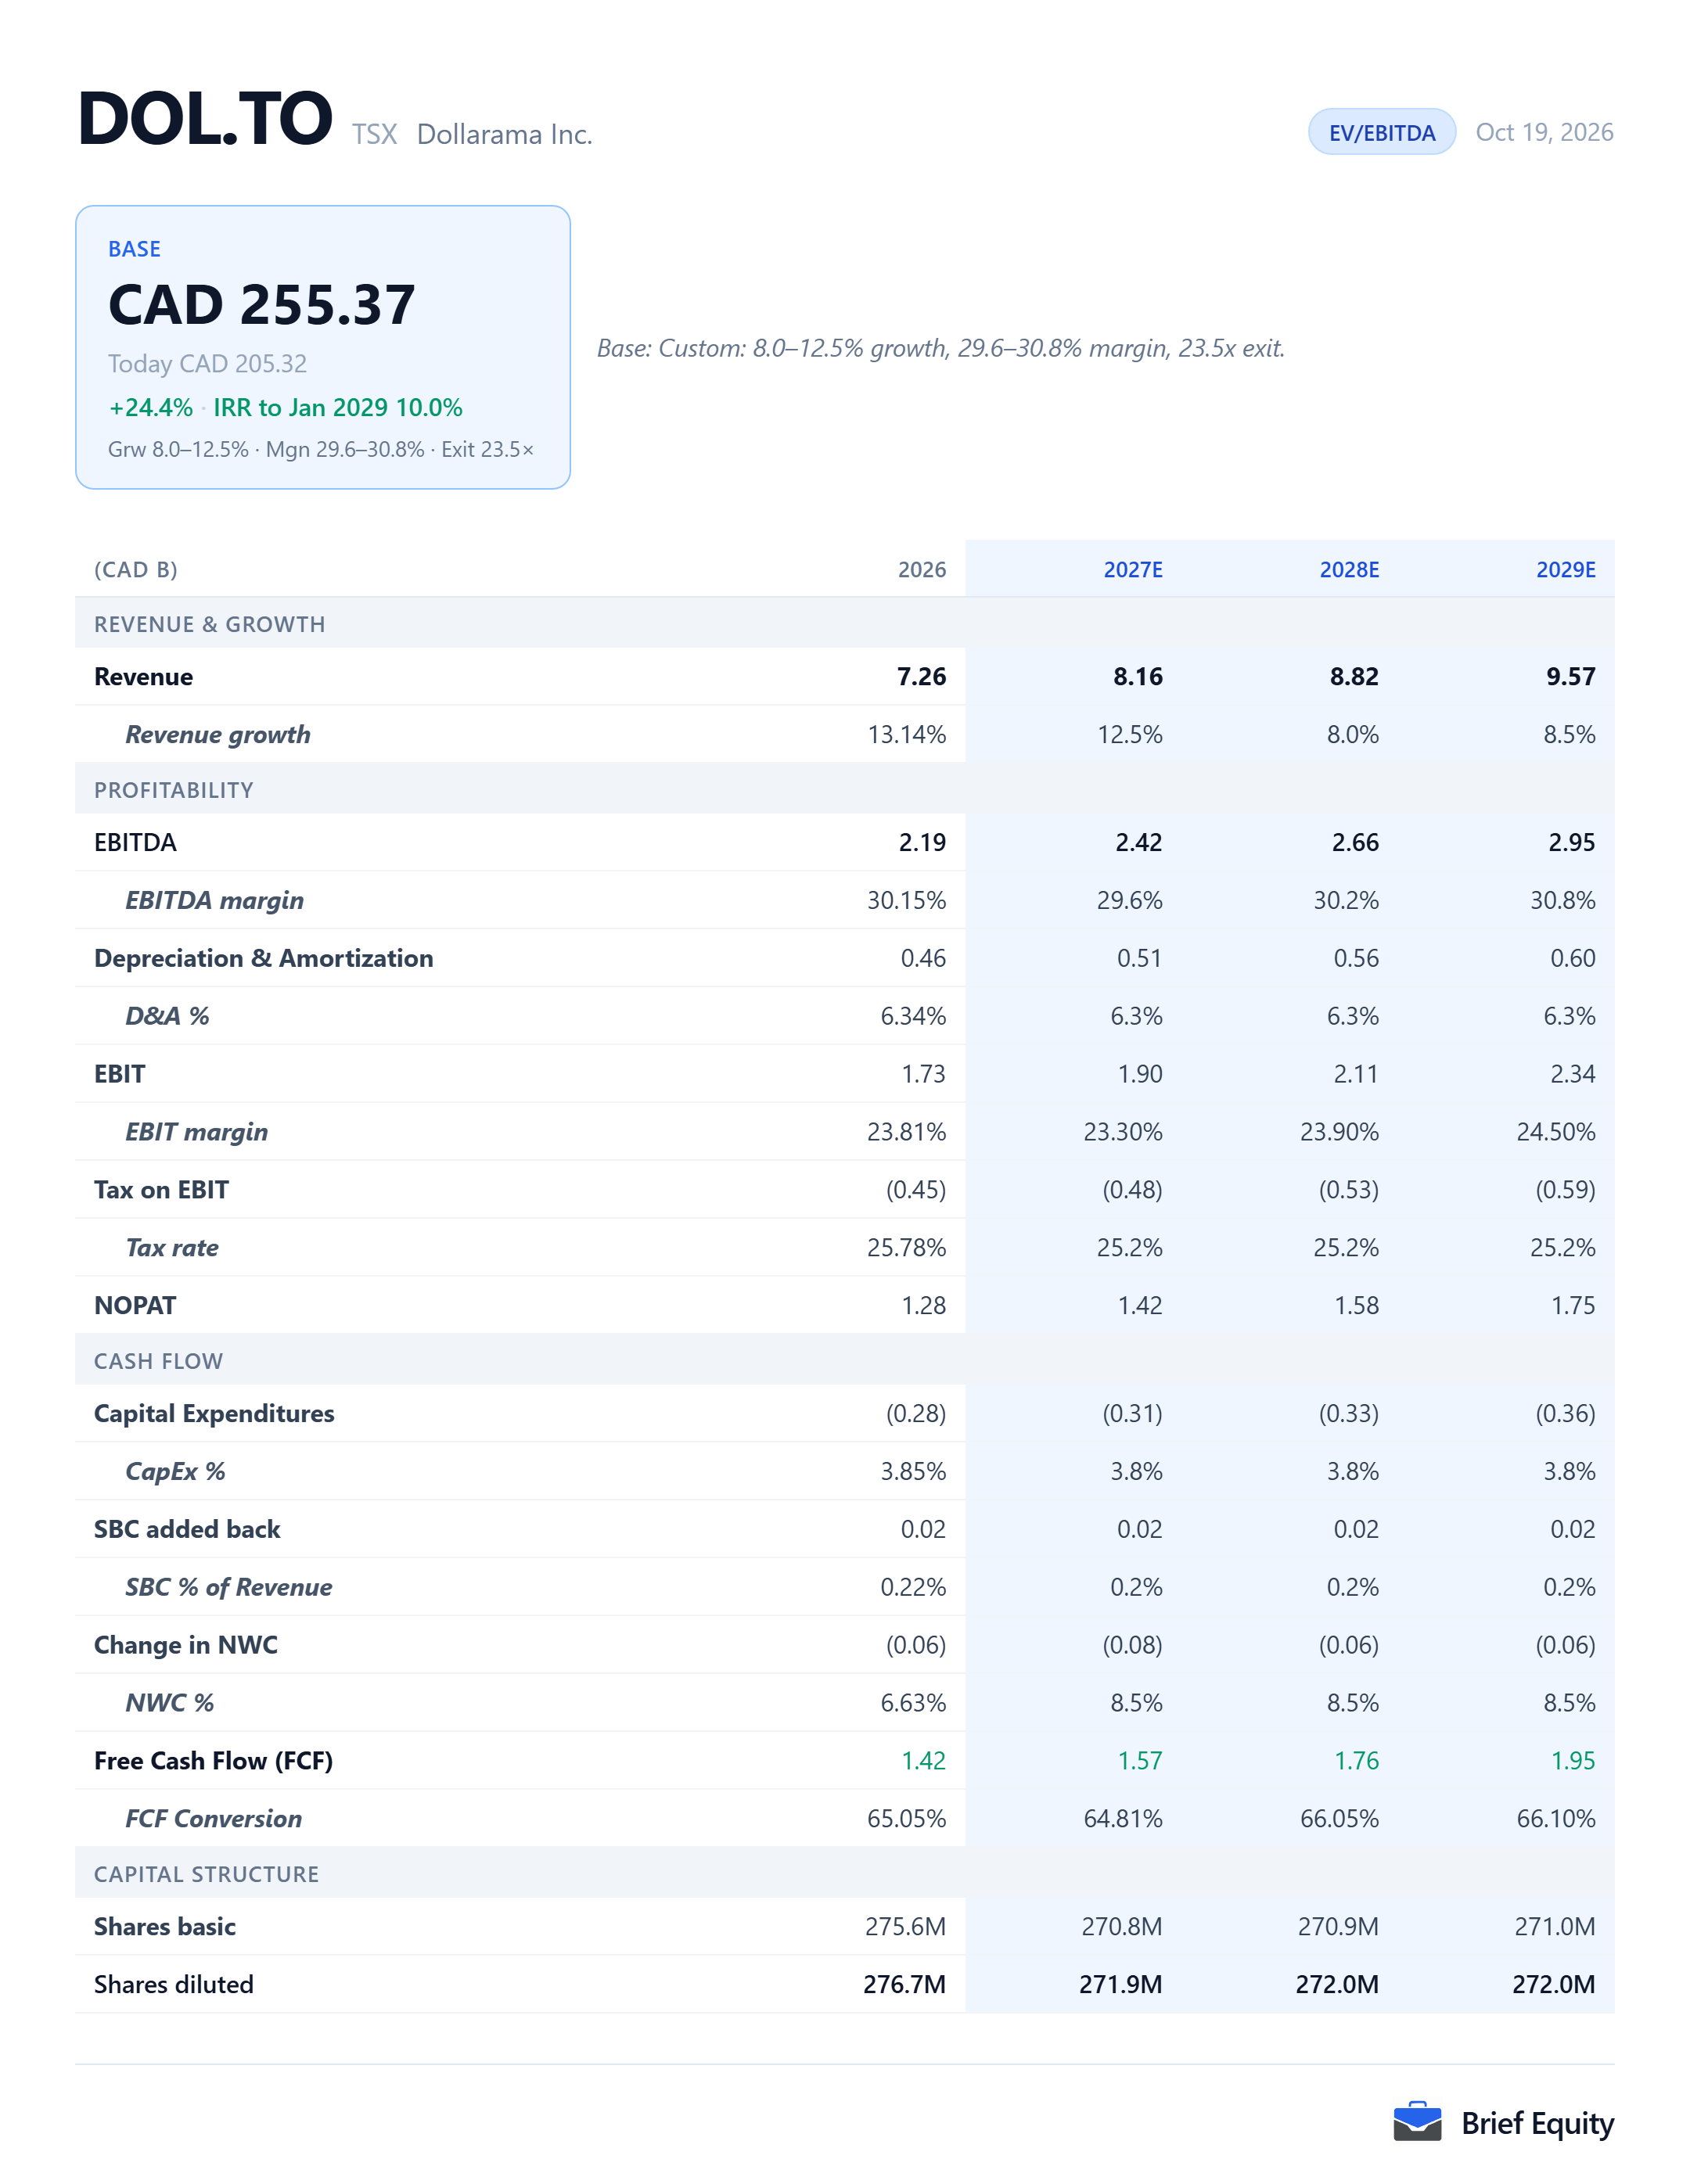
The model's assumptions for Dollarama
Dollarama's fiscal 2027 is the year ending January 31, 2027, and every figure in the model is in Canadian dollars. The model is a quick one: a few stated assumptions, carried forward three fiscal years. Analyst consensus revenue for the same years sits beside the model's own.
| Fiscal 2027 | Fiscal 2028 | Fiscal 2029 | |
|---|---|---|---|
| Revenue, model | 8.16 | 8.82 | 9.57 |
| Revenue, analyst consensus | 8.13 | 8.68 | 9.32 |
| Revenue growth, model | 12.5% | 8.0% | 8.5% |
| EBITDA, model | 2.42 | 2.66 | 2.95 |
| EBITDA margin, model | 29.6% | 30.2% | 30.8% |
Why Dollarama looks overvalued
Dollarama looks expensive at CAD 205.32 if slower population growth in Canada starts to show up in its store traffic. So far its traffic has held up. In the second quarter of fiscal 2027, which ended August 2, 2026, comparable store sales in Canada rose 5.4%, mostly from a 3.7% increase in the number of transactions.
“At a time when consumers are making careful spending decisions, customers are counting on Dollarama for dependable value.”
Neil Rossy, President and Chief Executive Officer, Dollarama fiscal 2027 second-quarter earnings call, September 16, 2026
Dollarama describes economic conditions in Canada as challenging, and it is still growing outside the country. It owns 60.1% of Dollarcity's business in Central and South America, and its share of the earnings from that business rose 39.7% in the quarter. In July 2025 it bought The Reject Shop in Australia, which had 414 stores on August 2, 2026, and it targets about 700 stores in Australia by 2034.
Dollarama expects its Australian segment to report a net loss in fiscal 2027 while it transforms the business there, so the model has the EBITDA margin at 29.6% in fiscal 2027, rising to 30.8% by fiscal 2029. Revenue grows 12.5% in fiscal 2027, against analyst consensus of 12.1% for that year, then 8.0% in fiscal 2028 and 8.5% in fiscal 2029.
On those assumptions the Dollarama model reaches CAD 255 a share by fiscal 2029, about 24% above the share price, provided Australia improves and the market values the shares at 23.5 times EBITDA in fiscal 2029.
Over the longer term, in Dollarama's home market, the federal government's 2026 to 2028 immigration levels plan holds permanent resident admissions at 380,000 a year, against a 2025 target of 395,000, and aims to bring non-permanent residents below 5% of the population by 2027. On Dollarama's call of September 16, 2026, an analyst raised slowing population growth, and the chief financial officer said the company does not track whether its traffic comes from new or repeat customers.
What has to be true, and what would break it
The Dollarama estimate holds only if the conditions below are met, and each of them can fail.
What has to be true
- Revenue grows 12.5% in fiscal 2027, 8.0% in fiscal 2028 and 8.5% in fiscal 2029.
- Australia moves out of its loss, so that the EBITDA margin rises from 29.6% in fiscal 2027 to 30.8% in fiscal 2029.
- Store traffic in Canada keeps growing while population growth slows.
- The shares are valued at 23.5 times EBITDA in fiscal 2029.
What would break it
- Slower population growth in Canada shows up as weaker store traffic.
- Australia's losses continue beyond fiscal 2027 and hold the margin down.
- The multiple applied in fiscal 2029 is lower than 23.5 times EBITDA.
The parts of Dollarama's business
Dollarama reports two segments, Canada and Australia, and has reported Australia since it acquired The Reject Shop on July 21, 2025. The table gives each segment's share of sales in the second quarter of fiscal 2027.
| Share of revenue | |
|---|---|
| Canada | 90.9% |
| Australia | 9.1% |
Dollarama beside its peers
Dollarama is compared with nine companies: three discount and closeout retailers in the United States, two large value retailers in the United States, a Canadian food and pharmacy retailer, the owner of Kmart in Australia, and two value retailers in Latin America.
- DG: a dollar-store chain in the United States
- DLTR: a dollar-store chain in the United States
- OLLI: a closeout value retailer in the United States
- COST: defensive value retail at scale
- WMT: defensive value retail at scale
- L.TO: defensive retail in Canada
- WES.AX: the Australian value market, through Kmart
- PSMT: value retail in Central America and the Caribbean, standing in for the unlisted Dollarcity
- WALMEX.MX: value retail in Mexico, where Dollarcity is opening stores
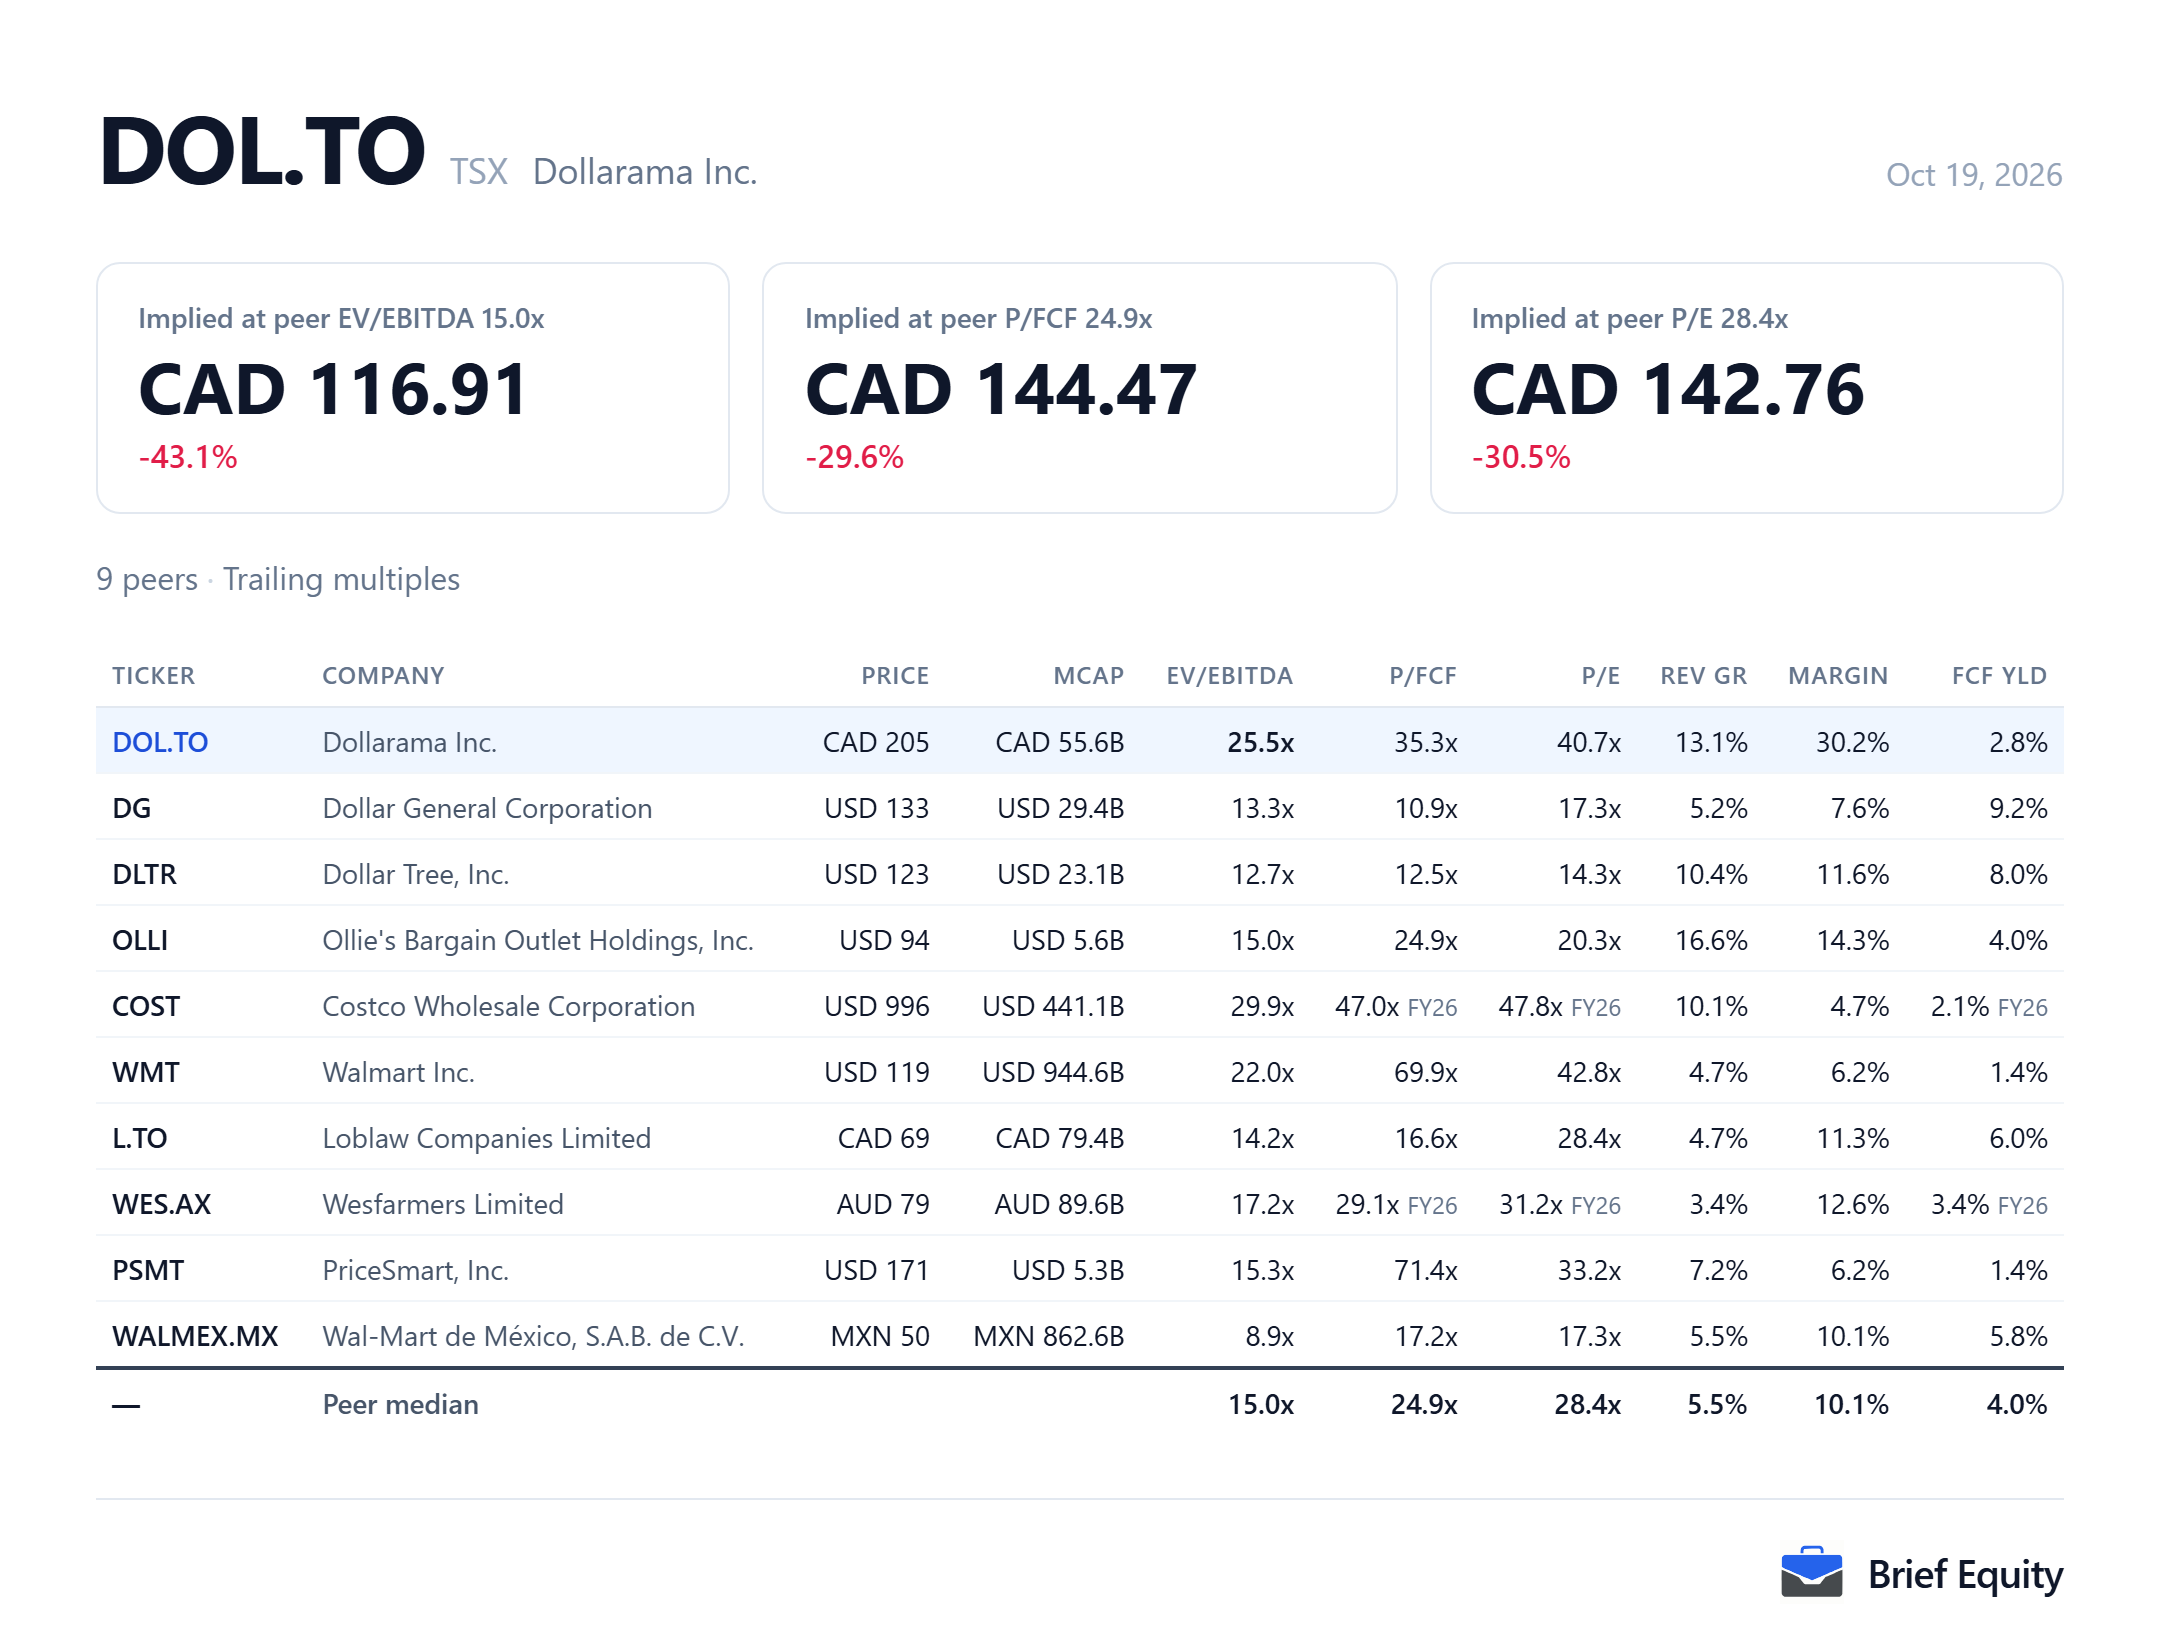
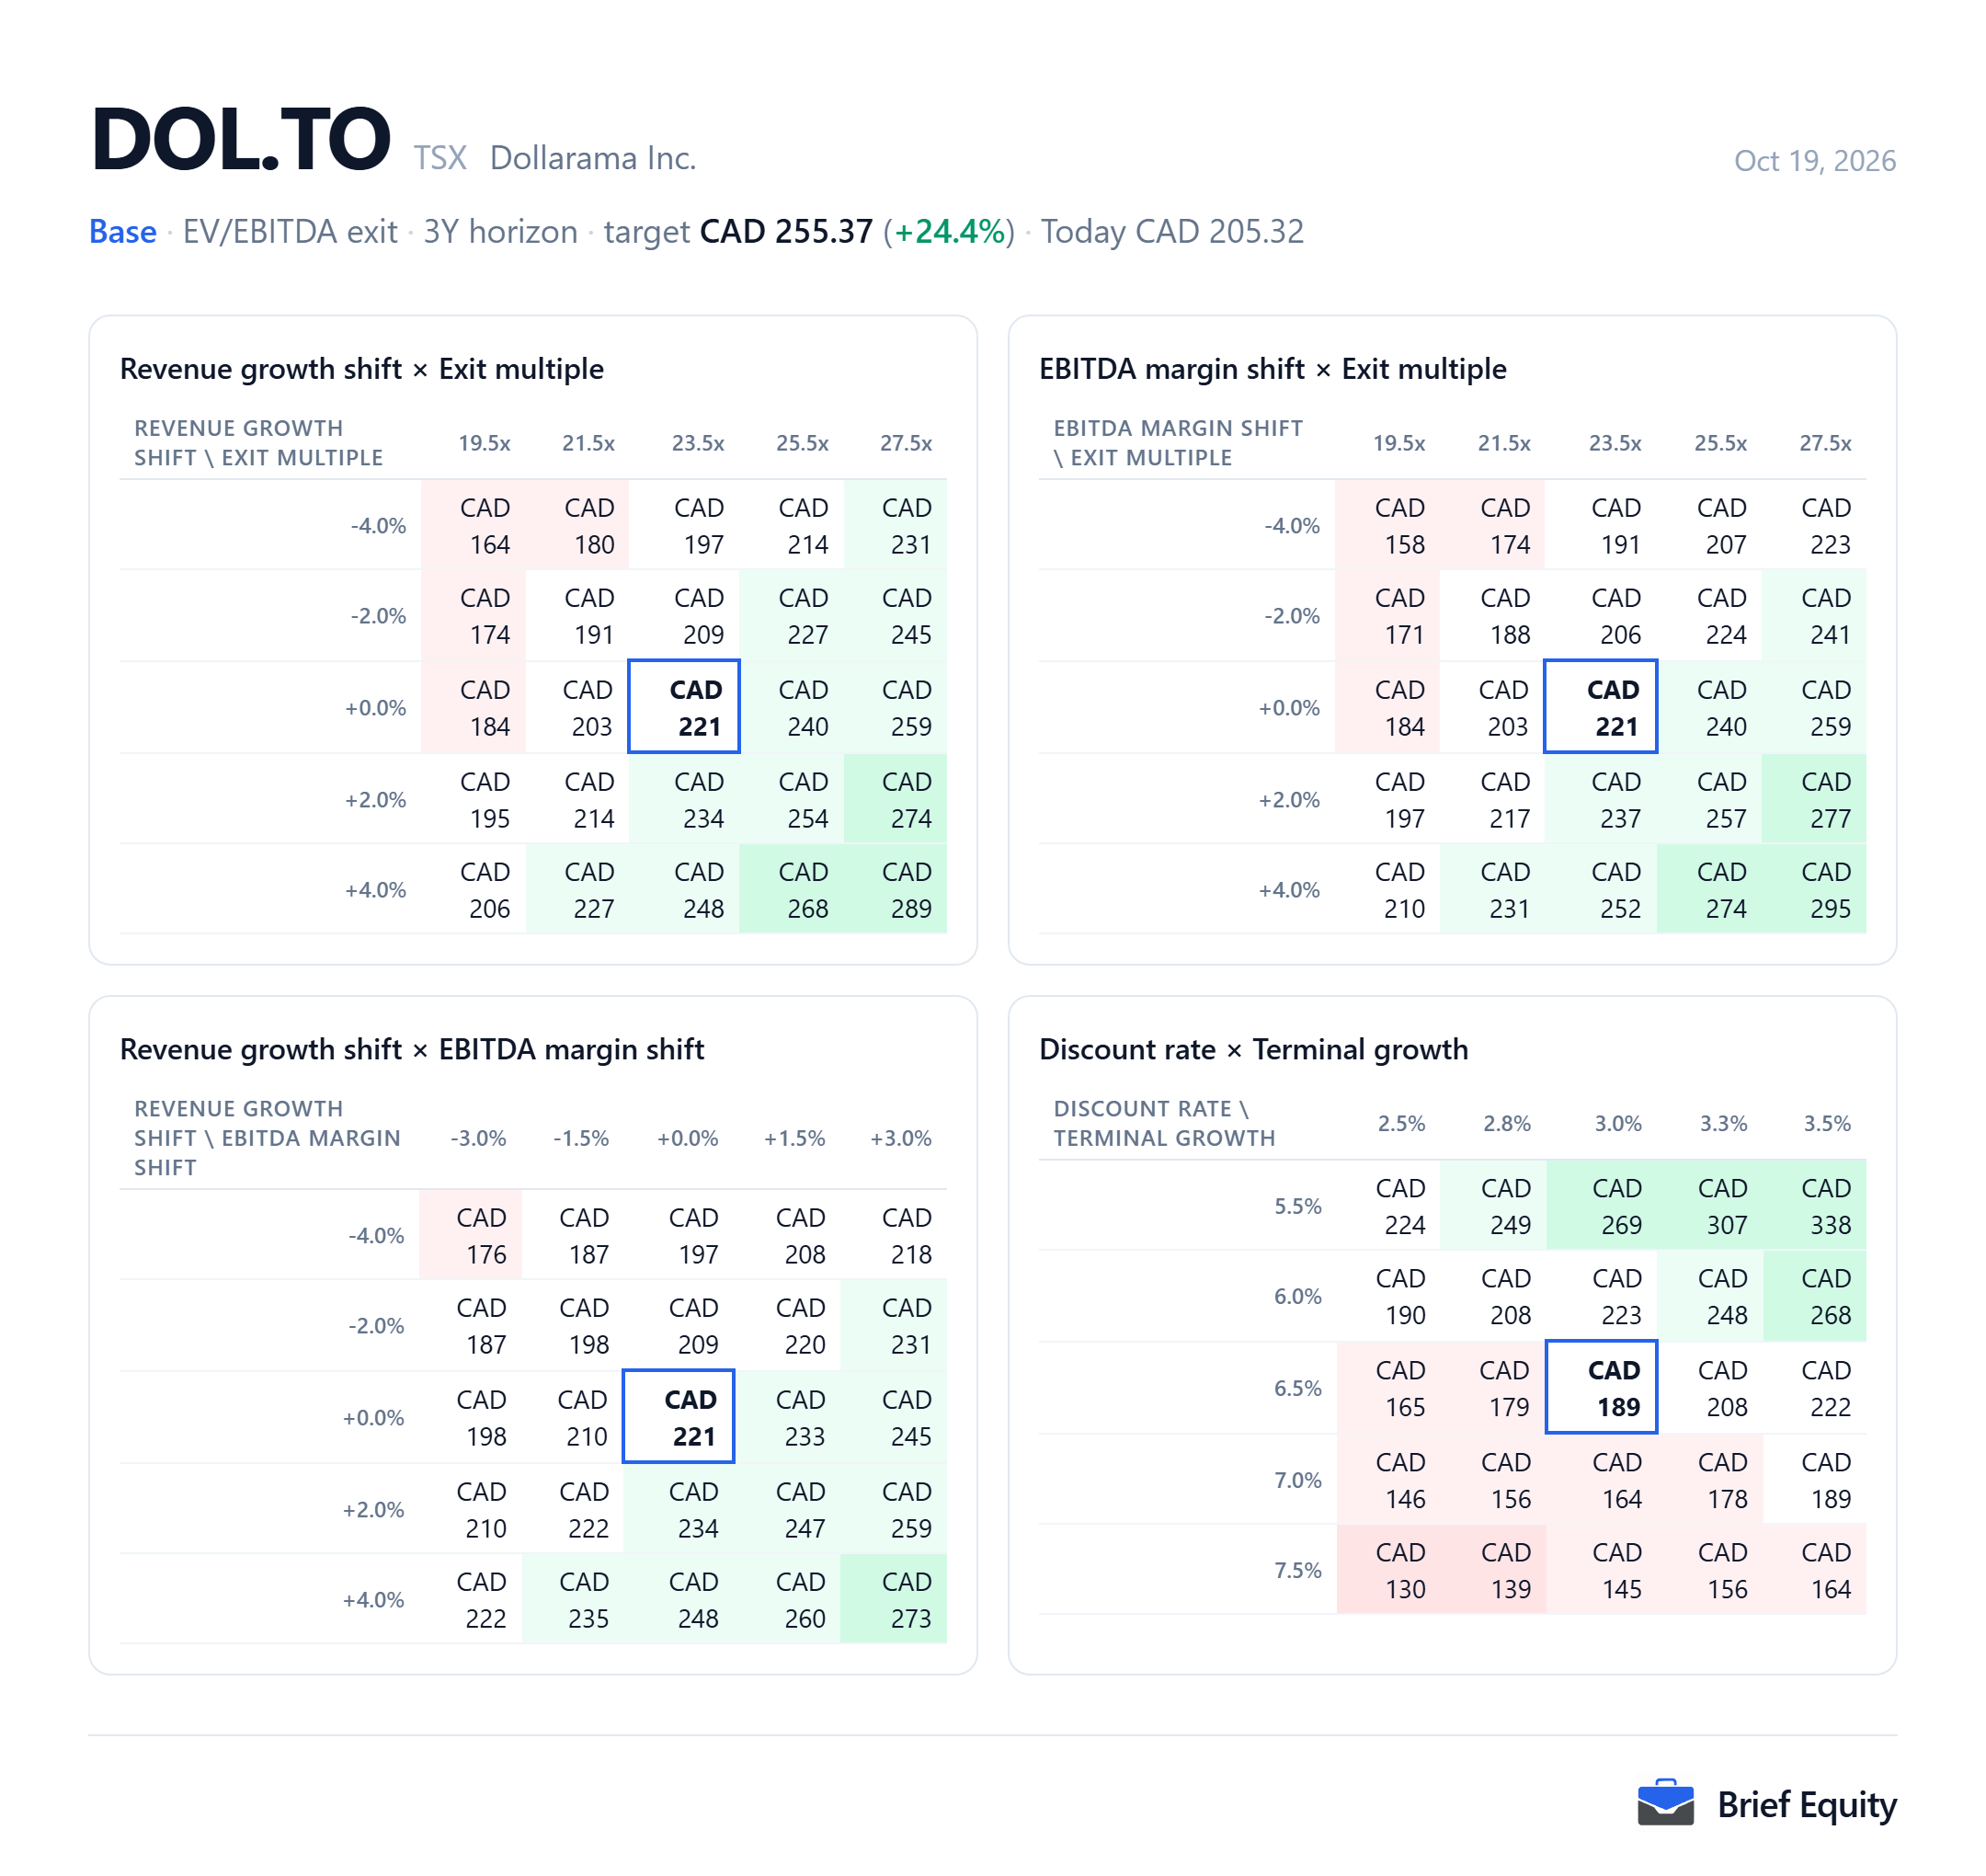
How the estimate moves with its assumptions
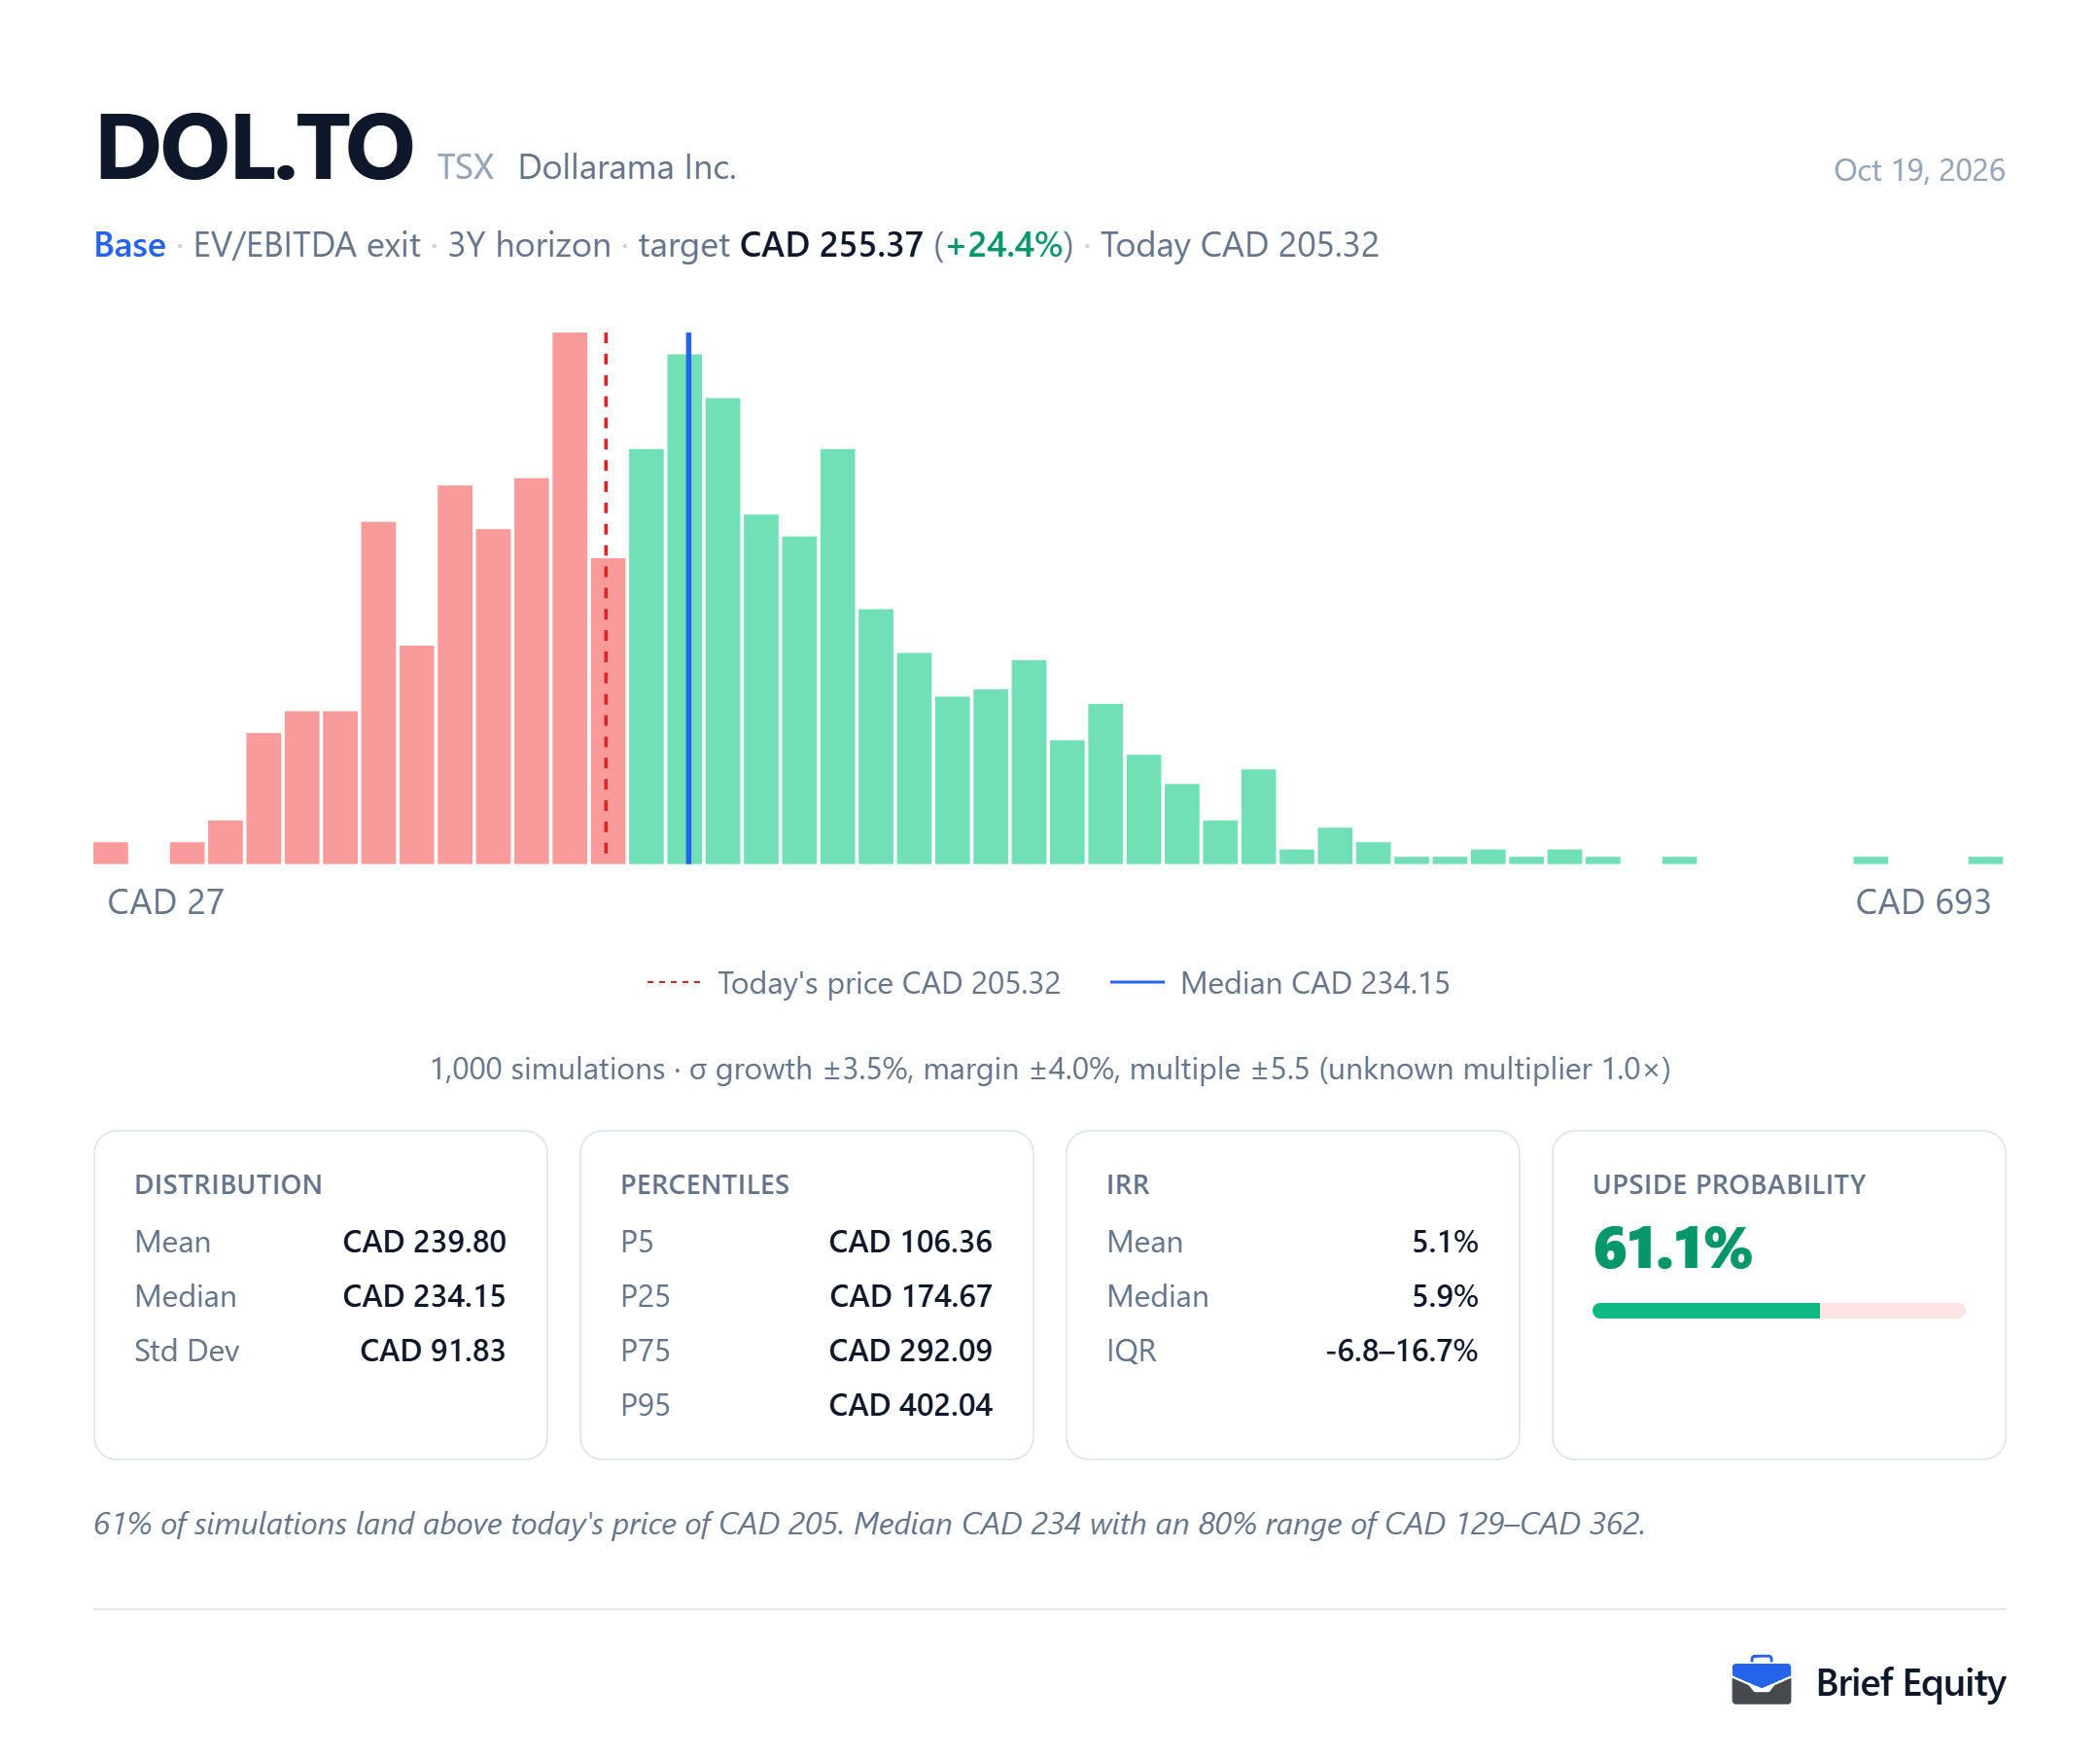
The Dollarama estimate moves with its assumptions, and the two pictures below show by how much. The first changes two assumptions at a time. The second runs the model many times with growth, margin and the exit multiple drawn at random.
Questions about Dollarama
These questions about Dollarama (DOL.TO) are answered from the documents listed under Sources.
- How many stores does Dollarama have in Canada?
- Dollarama had 1,734 stores in Canada on August 2, 2026, up from 1,665 a year earlier.
- How many stores does Dollarama plan to have in Canada?
- In its investor presentation of September 16, 2026, Dollarama set a long-term target of 2,200 stores in Canada by 2034.
- Will Dollarama raise its maximum price?
- Dollarama's highest price point is CAD 5, and on its call of September 16, 2026 the chief executive said the company does not believe an additional price point is necessary based on what it sees today.
Sources
The quotations and facts about Dollarama (DOL.TO) on this page rest on the documents below.
- Dollarama second-quarter fiscal 2027 earnings release, September 16, 2026
- Dollarama fiscal 2027 second-quarter earnings call, September 16, 2026
- Dollarama investor presentation, second quarter of fiscal 2027, September 16, 2026
- 2026 to 2028 Immigration Levels Plan, permanent resident targets, December 4, 2025
About this page
Brief Equity and its team hold no position in Dollarama (DOL.TO) as of October 19, 2026.
This page is research, not investment advice. It describes one model and the assumptions behind it, and market data is delayed. Read how these models are built and our editorial policy.
Related guides: EV/EBITDA explained, How to do a comparable-companies (comps) analysis, What is an investment thesis.