Valuation · EV/Sales model
Is Datadog (DDOG) stock overvalued?
On November 5, 2026, with the shares at $174.60, a quick EV/Sales model by Brief Equity valued Datadog at about $222 for 2028. That is about 27% above the price over three years, which looks thin for a company whose large customers have been pushing its prices down. Datadog looks somewhat overvalued on that model unless growth from its customers outside AI keeps accelerating.
By The Brief Equity Team · Model dated · Published
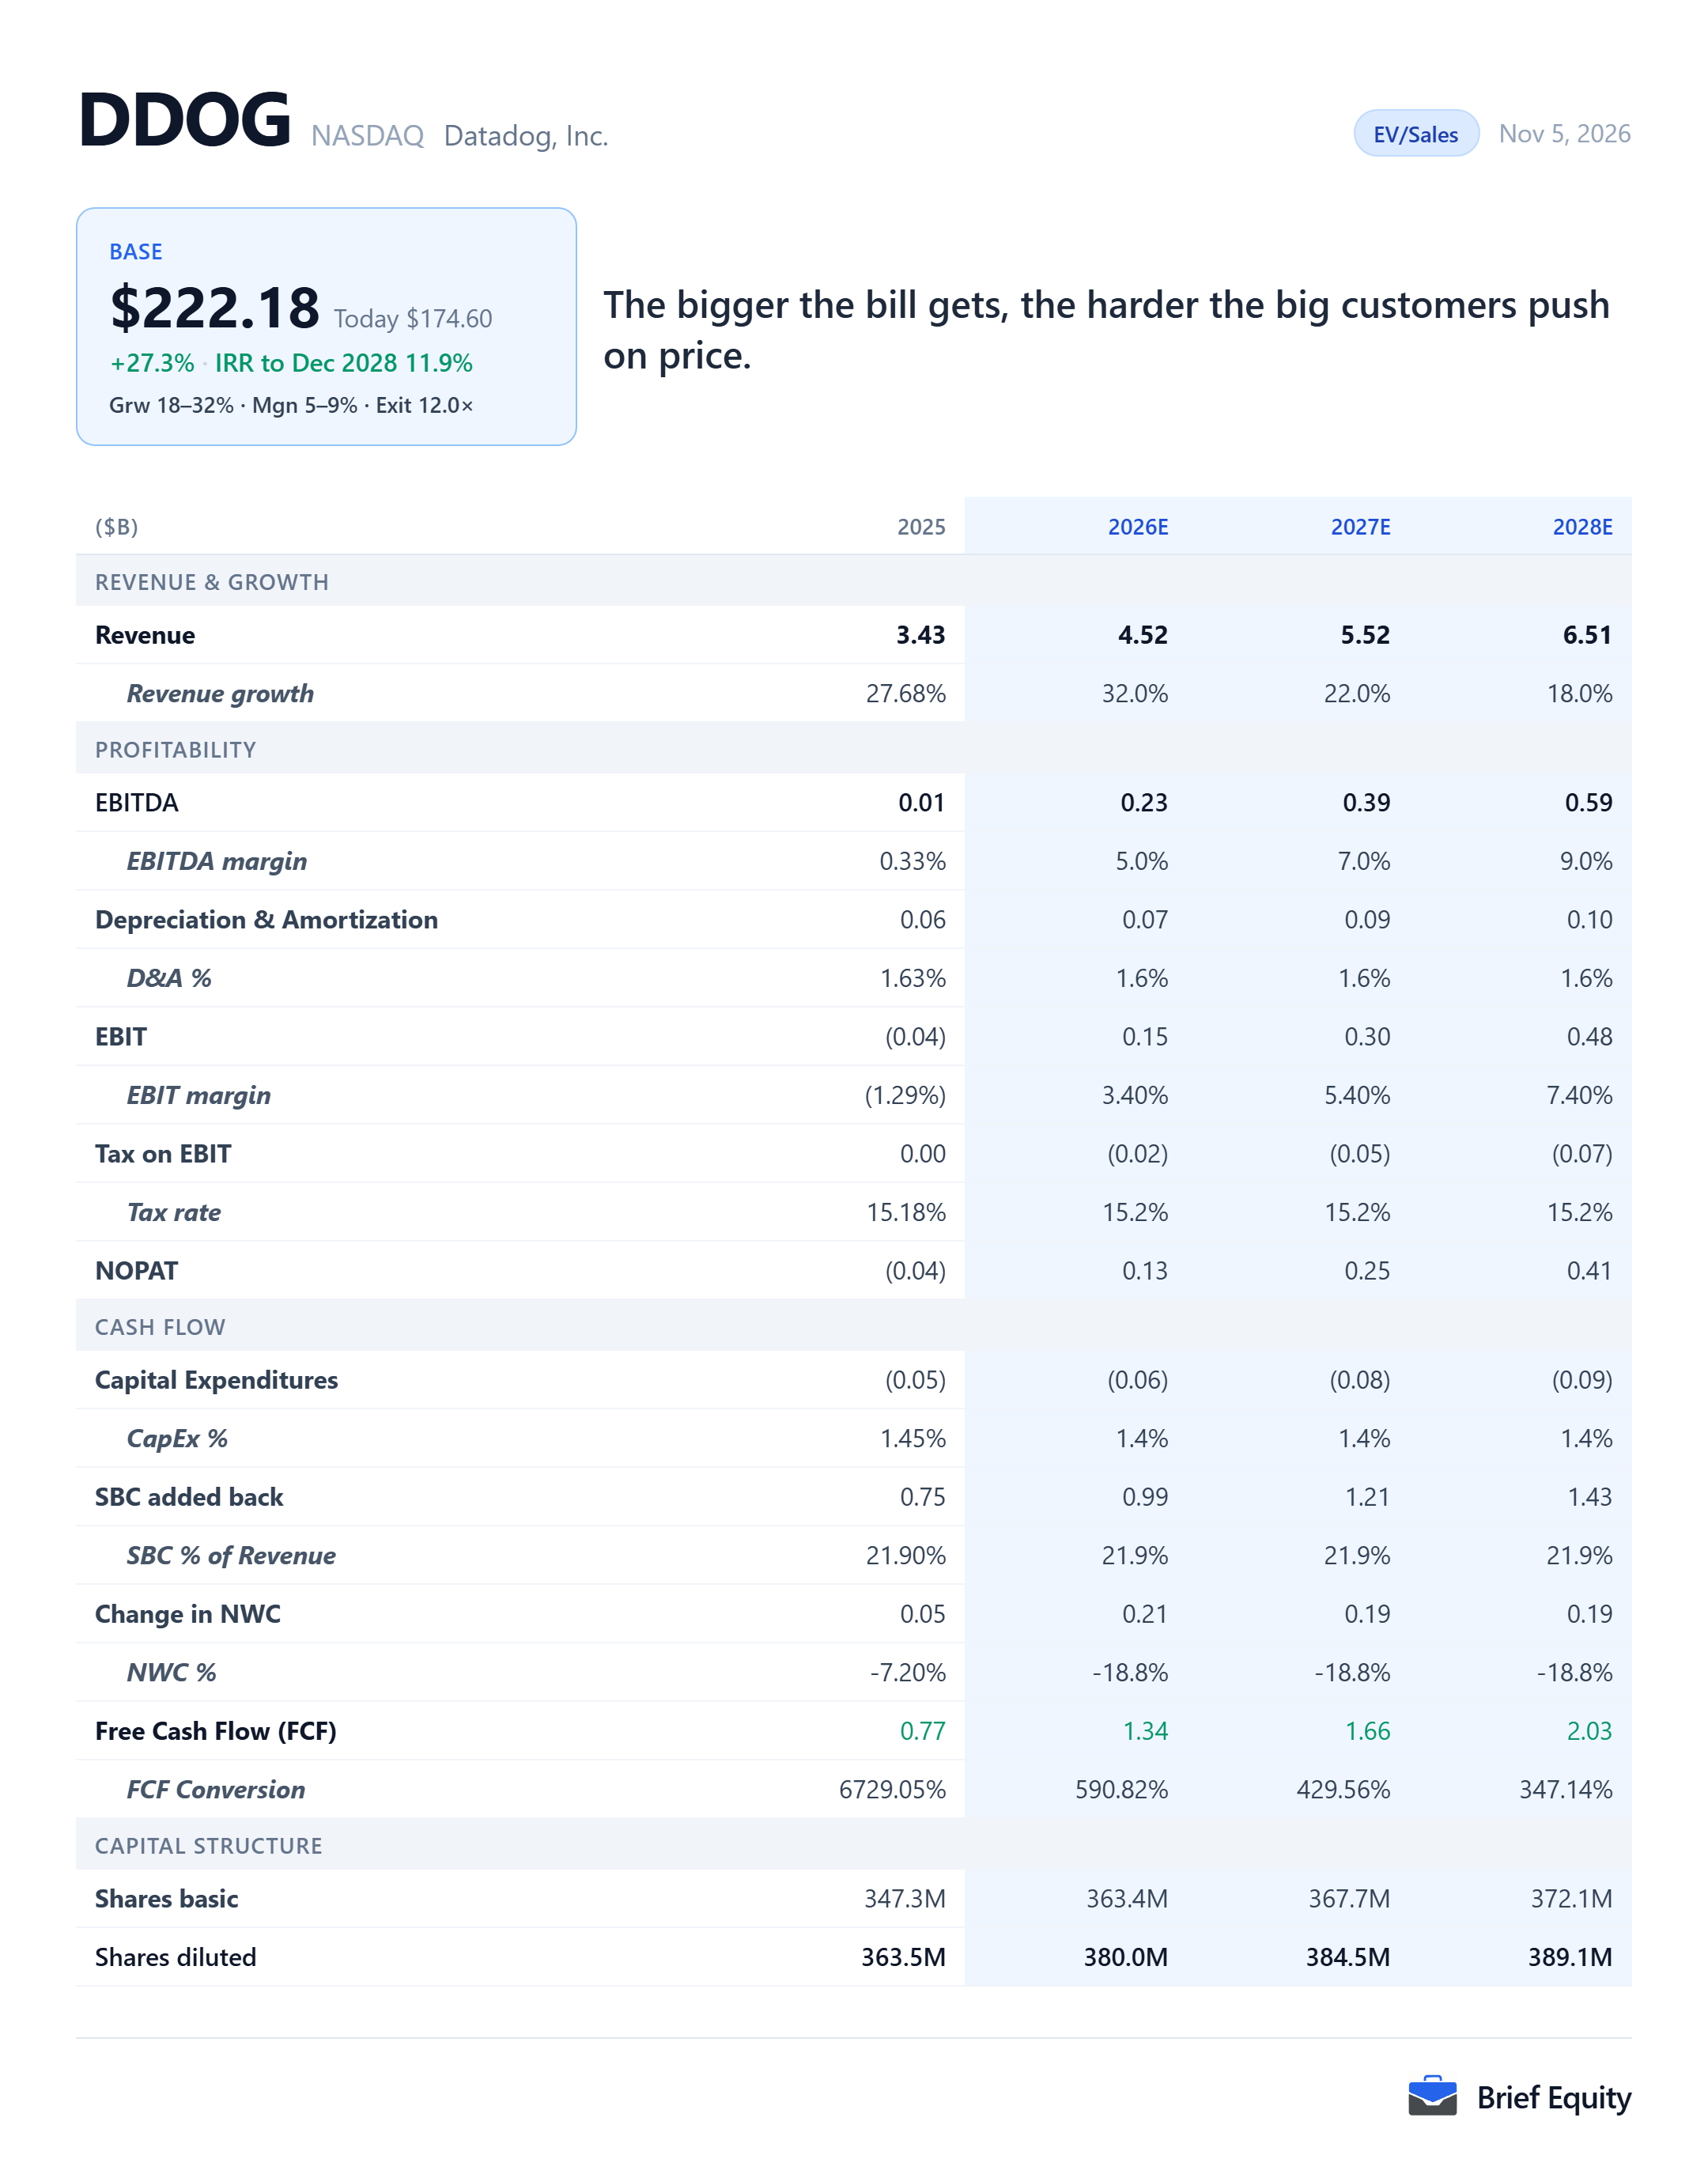
The model's assumptions for Datadog
Datadog's fiscal year is the calendar year, and the last year it has reported in full is 2025. The model runs three years, to 2028, and values the company on a multiple of its 2028 revenue. Every row below is the model's own except the analyst consensus revenue.
| 2026 | 2027 | 2028 | |
|---|---|---|---|
| Revenue, model | 4.52 | 5.52 | 6.51 |
| Revenue growth, model | 32.0% | 22.0% | 18.0% |
| Revenue, analyst consensus | 4.48 | 5.49 | 6.78 |
Why Datadog looks overvalued
Datadog's large customers have been pushing its prices down. In the third quarter of 2026, several of them, AI companies among them, renewed their contracts early at higher commitments and lower prices. The stock fell about 34% in the week to November 5, 2026, and the model still values it only modestly above that price.
Datadog describes the pattern itself in its annual report for 2025:
“Certain customers and cohorts of customers in specific industries have or in the future may increase usage of our product and then seek to optimize their usage, renew their subscriptions on terms less favorable to us, or not renew their subscriptions, which may result in revenue volatility.”
Datadog annual report on Form 10-K for 2025, February 18, 2026
Coinbase did this. According to The Pragmatic Engineer, Coinbase spent $65M with Datadog in 2021, built its own monitoring system to replace it as the crypto market cooled, and stayed only after Datadog offered it a better deal. Separately, Datadog's largest customer reduced its usage in the third quarter of 2026, and Datadog has not said why.
For Datadog, the Brief Equity model takes revenue growth of 32.0% in 2026, in line with the company's own guidance of about 32% for the year, slowing to 22.0% in 2027 and 18.0% in 2028, somewhat below the analyst consensus. At 12 times 2028 revenue, that values Datadog at about $222 a share in 2028, about 27% above the price of $174.60.
The main risk to this view is the rest of Datadog's business. Revenue growth from customers outside AI accelerated for the fifth straight quarter, to the high 20s percent, and if it keeps accelerating, the price pressure from large customers matters much less.
What has to be true, and what would break it
The view that Datadog looks somewhat overvalued at $174.60 rests on its large customers continuing to push its prices down.
What has to be true
- Large customers keep optimizing their usage and renewing at lower prices as their bills grow, as Datadog's annual report says some have done.
- Revenue growth slows to around 22% in 2027 and 18% in 2028, below the analyst consensus.
- The market pays about 12 times revenue for Datadog in 2028.
What would break it
- Growth from customers outside AI keeps accelerating from the high 20s percent.
- The customers that renewed early at lower prices grow their usage enough to make up the difference.
- The market keeps paying a higher multiple of revenue for Datadog than 12 times.
The parts of Datadog's business
Datadog reports one business, and it splits its revenue by where customers are billed.
| Share of revenue | Share of revenue growth | |
|---|---|---|
| North America | 71.0% | 75.2% |
| International | 29.0% | 24.8% |
Datadog beside its peers
Datadog is compared here with seven U.S.-listed software companies chosen for this post: monitoring rivals and usage-priced infrastructure and developer tools sold to the same technology buyers.
- DT: Monitoring software, the direct rival
- ESTC: Monitoring and search built on open source
- NET: Usage-priced network and developer infrastructure
- SNOW: Usage-priced data platform
- MDB: Usage-priced database with open-source alternatives
- GTLB: Developer tools
- NOW: IT operations and workflow software
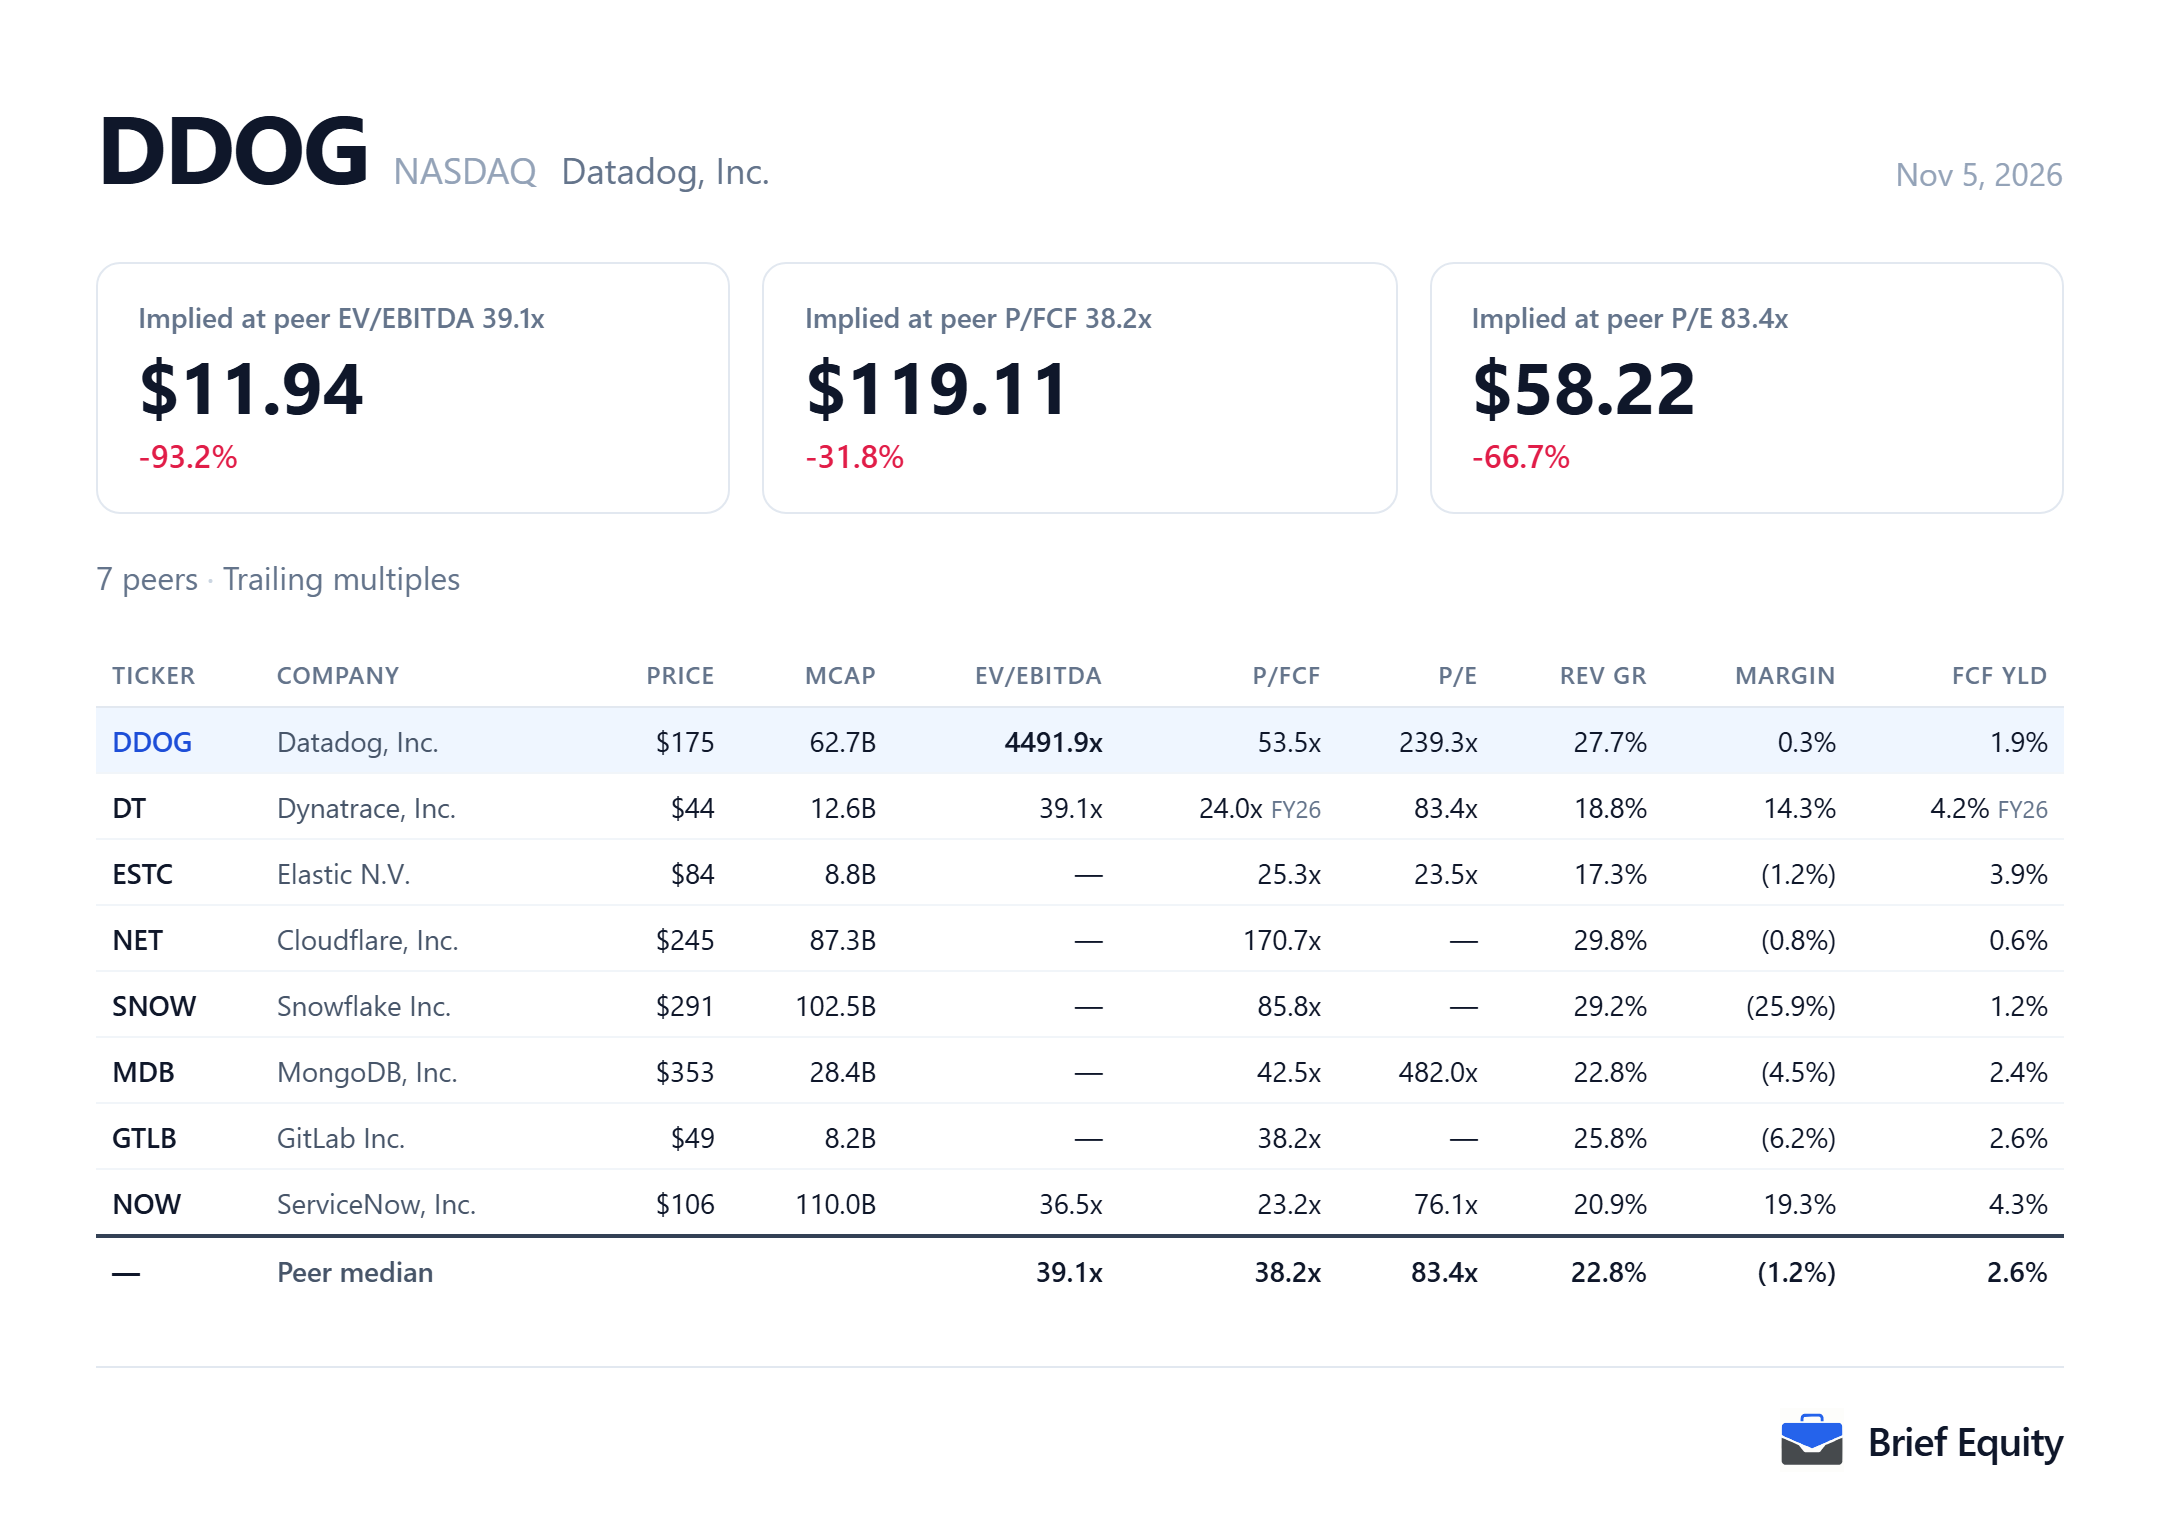
How the estimate moves with its assumptions
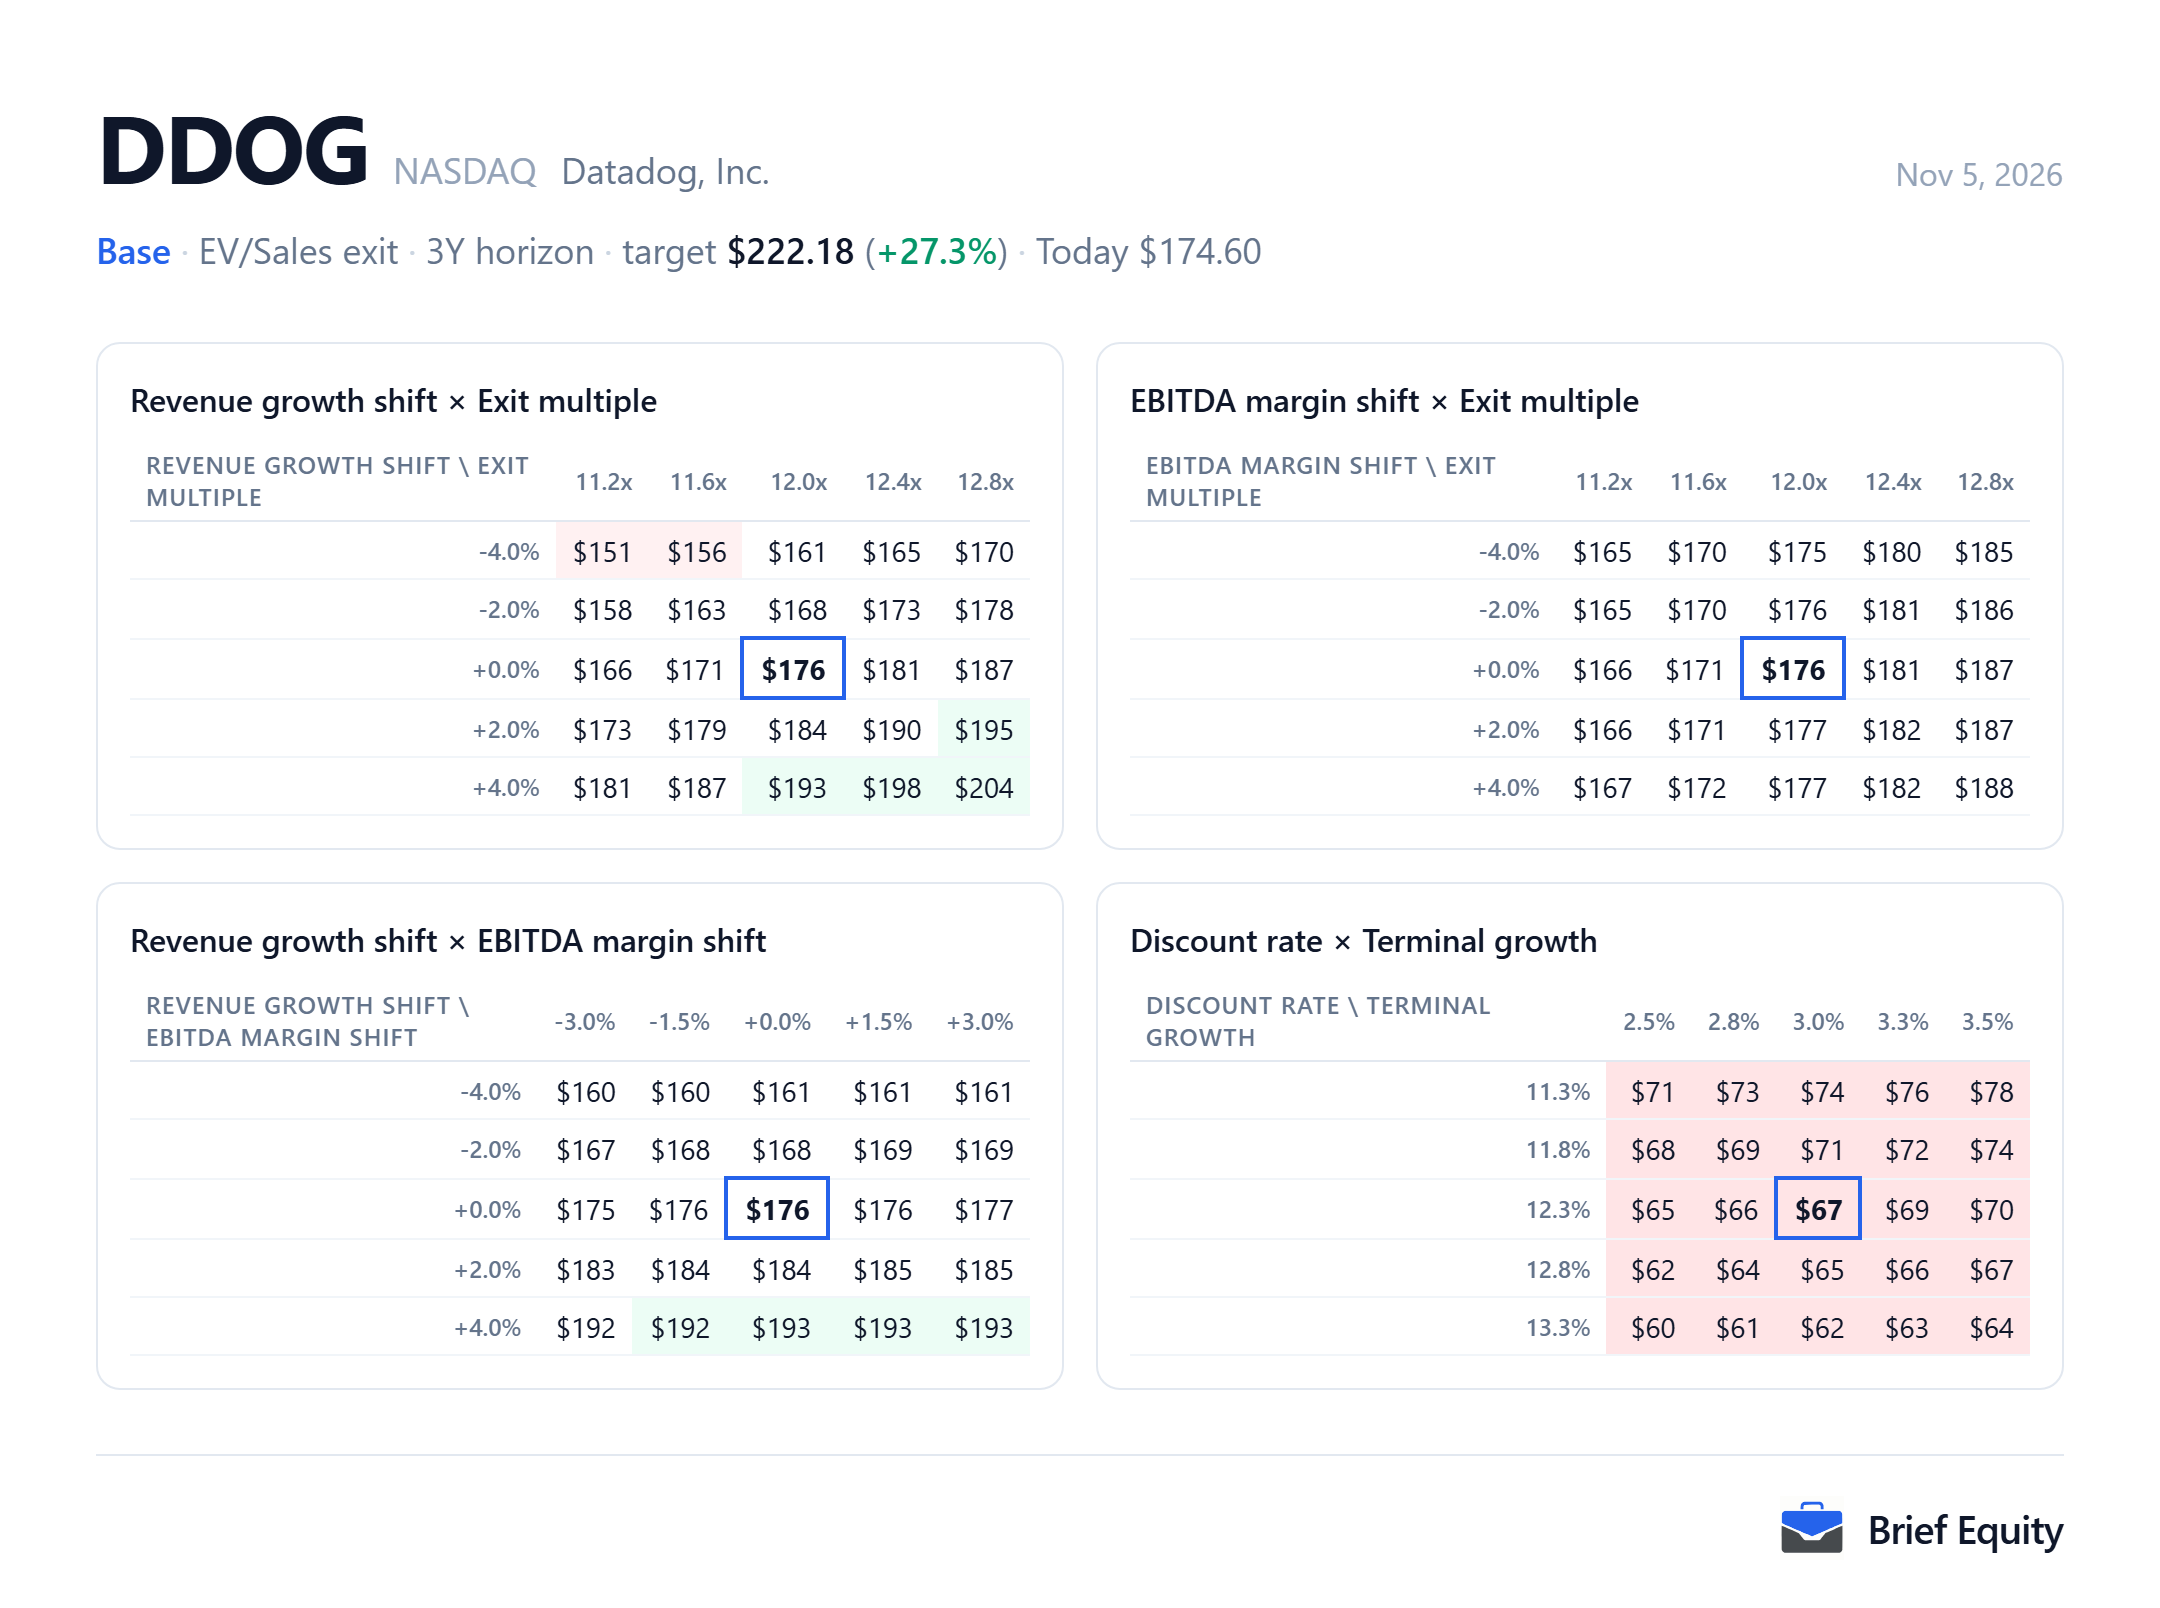
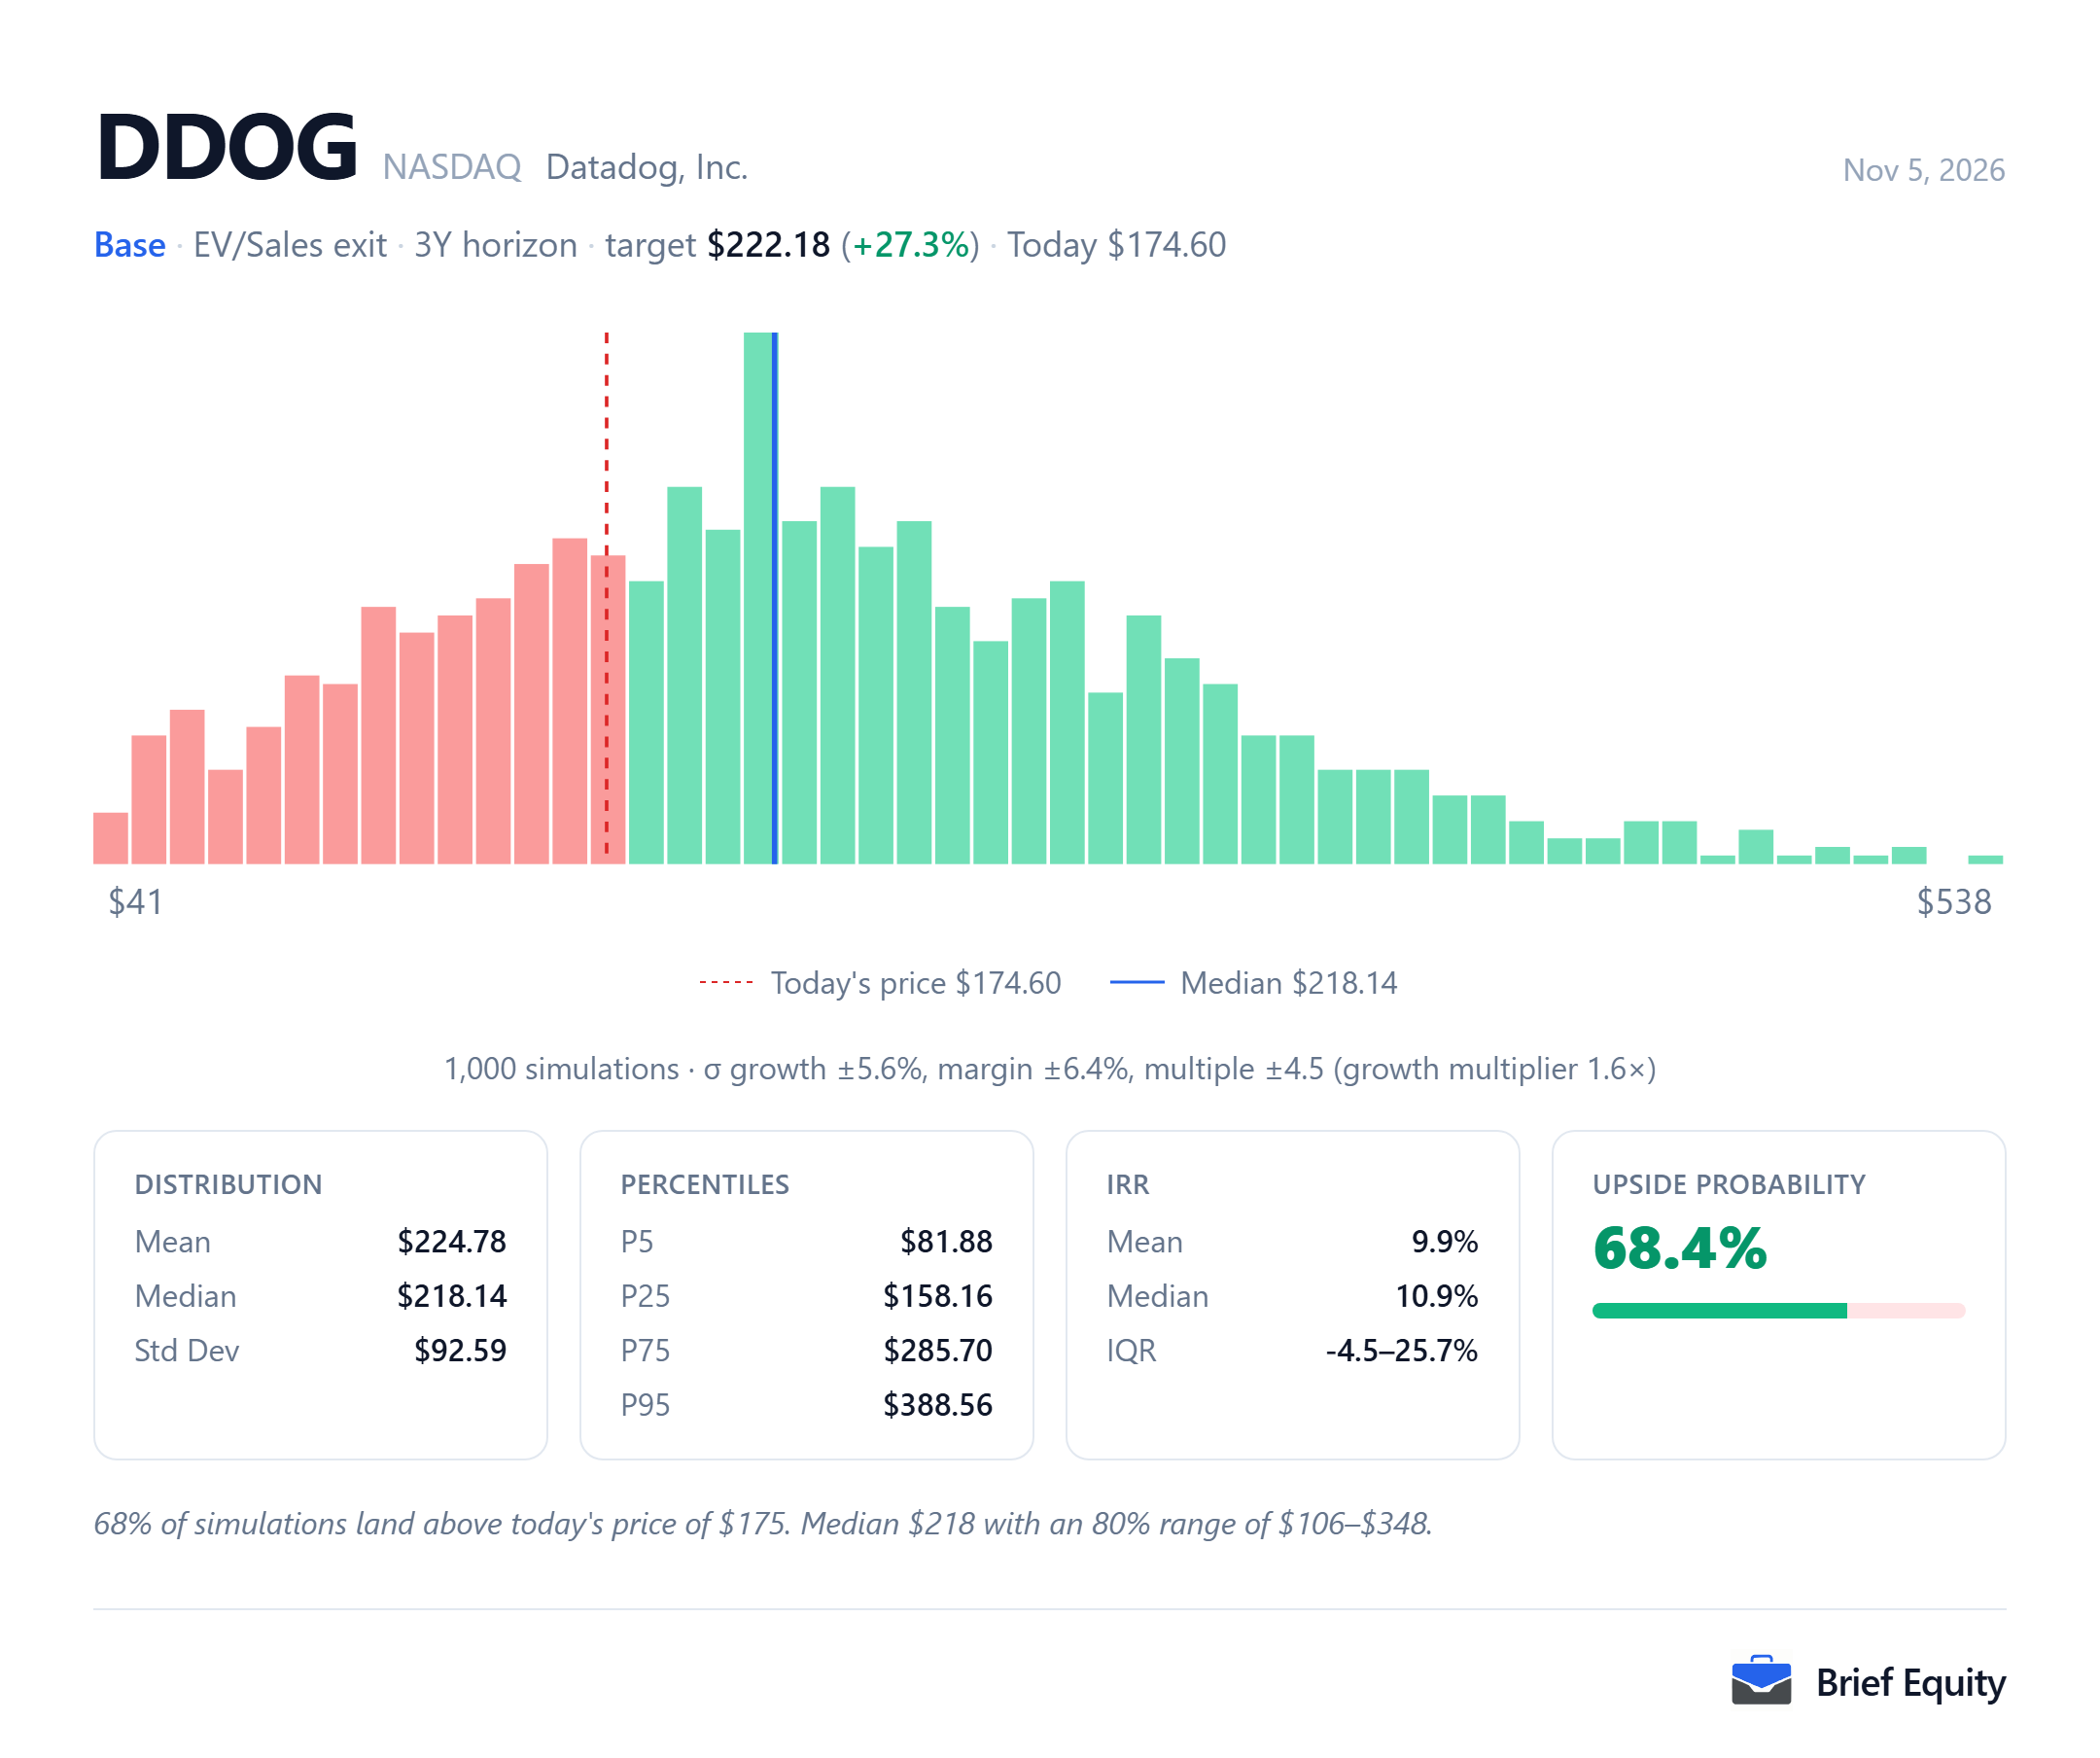
The two Datadog cards below test the estimate: the sensitivity grids move two assumptions at a time, and the Monte Carlo card reruns the model many times with growth, margin and the exit multiple drawn at random.
Questions about Datadog
These questions about Datadog (DDOG) are answered from the documents listed under Sources.
- Who is Datadog's largest customer?
- Datadog has not named it. On its call of August 6, 2026, it described the customer as a leading AI company that had signed a 9-figure renewal and uses 17 Datadog products.
- What revenue does Datadog expect for 2026?
- On November 4, 2026, Datadog guided full-year 2026 revenue to between $4.515 billion and $4.525 billion.
- How much stock-based compensation did Datadog record in 2025?
- Datadog recorded $750.7 million of stock-based compensation, net of amounts capitalized, in 2025, on revenue of $3.43 billion.
- Does Datadog carry debt?
- Datadog's only borrowing at September 30, 2026 was $1.0 billion of 0.00% convertible notes due December 1, 2029.
Sources
The quotations and facts about Datadog (DDOG) on this page rest on the documents below.
- Datadog annual report on Form 10-K for 2025, February 18, 2026
- Datadog quarterly report on Form 10-Q for the third quarter of 2026, November 4, 2026
- Datadog third-quarter 2026 results release, November 4, 2026
- Datadog third-quarter 2026 earnings call, November 4, 2026
- Datadog second-quarter 2026 earnings call, August 6, 2026
- Datadog's share price fall in the week to November 5, 2026, November 5, 2026
- The Pragmatic Engineer: Datadog's $65M/year customer mystery solved, May 11, 2023
About this page
Brief Equity and its team hold no position in Datadog (DDOG) as of November 5, 2026.
This page is research, not investment advice. It describes one model and the assumptions behind it, and market data is delayed. Read how these models are built and our editorial policy.
Related guides: What is enterprise value (EV), How to read a 10-K (SEC filing), How to research a stock before you buy.