Valuation · EV/EBITDA model
Is Church & Dwight (CHD) stock undervalued?
On November 2, 2026, with the shares at $110.45, a quick EV/EBITDA model by Brief Equity valued Church & Dwight at about $150 for 2028. Church & Dwight looks undervalued on that model if its brands keep growing at about 5% a year through 2028 and its margin keeps rising despite inflation.
By The Brief Equity Team · Model dated · Published
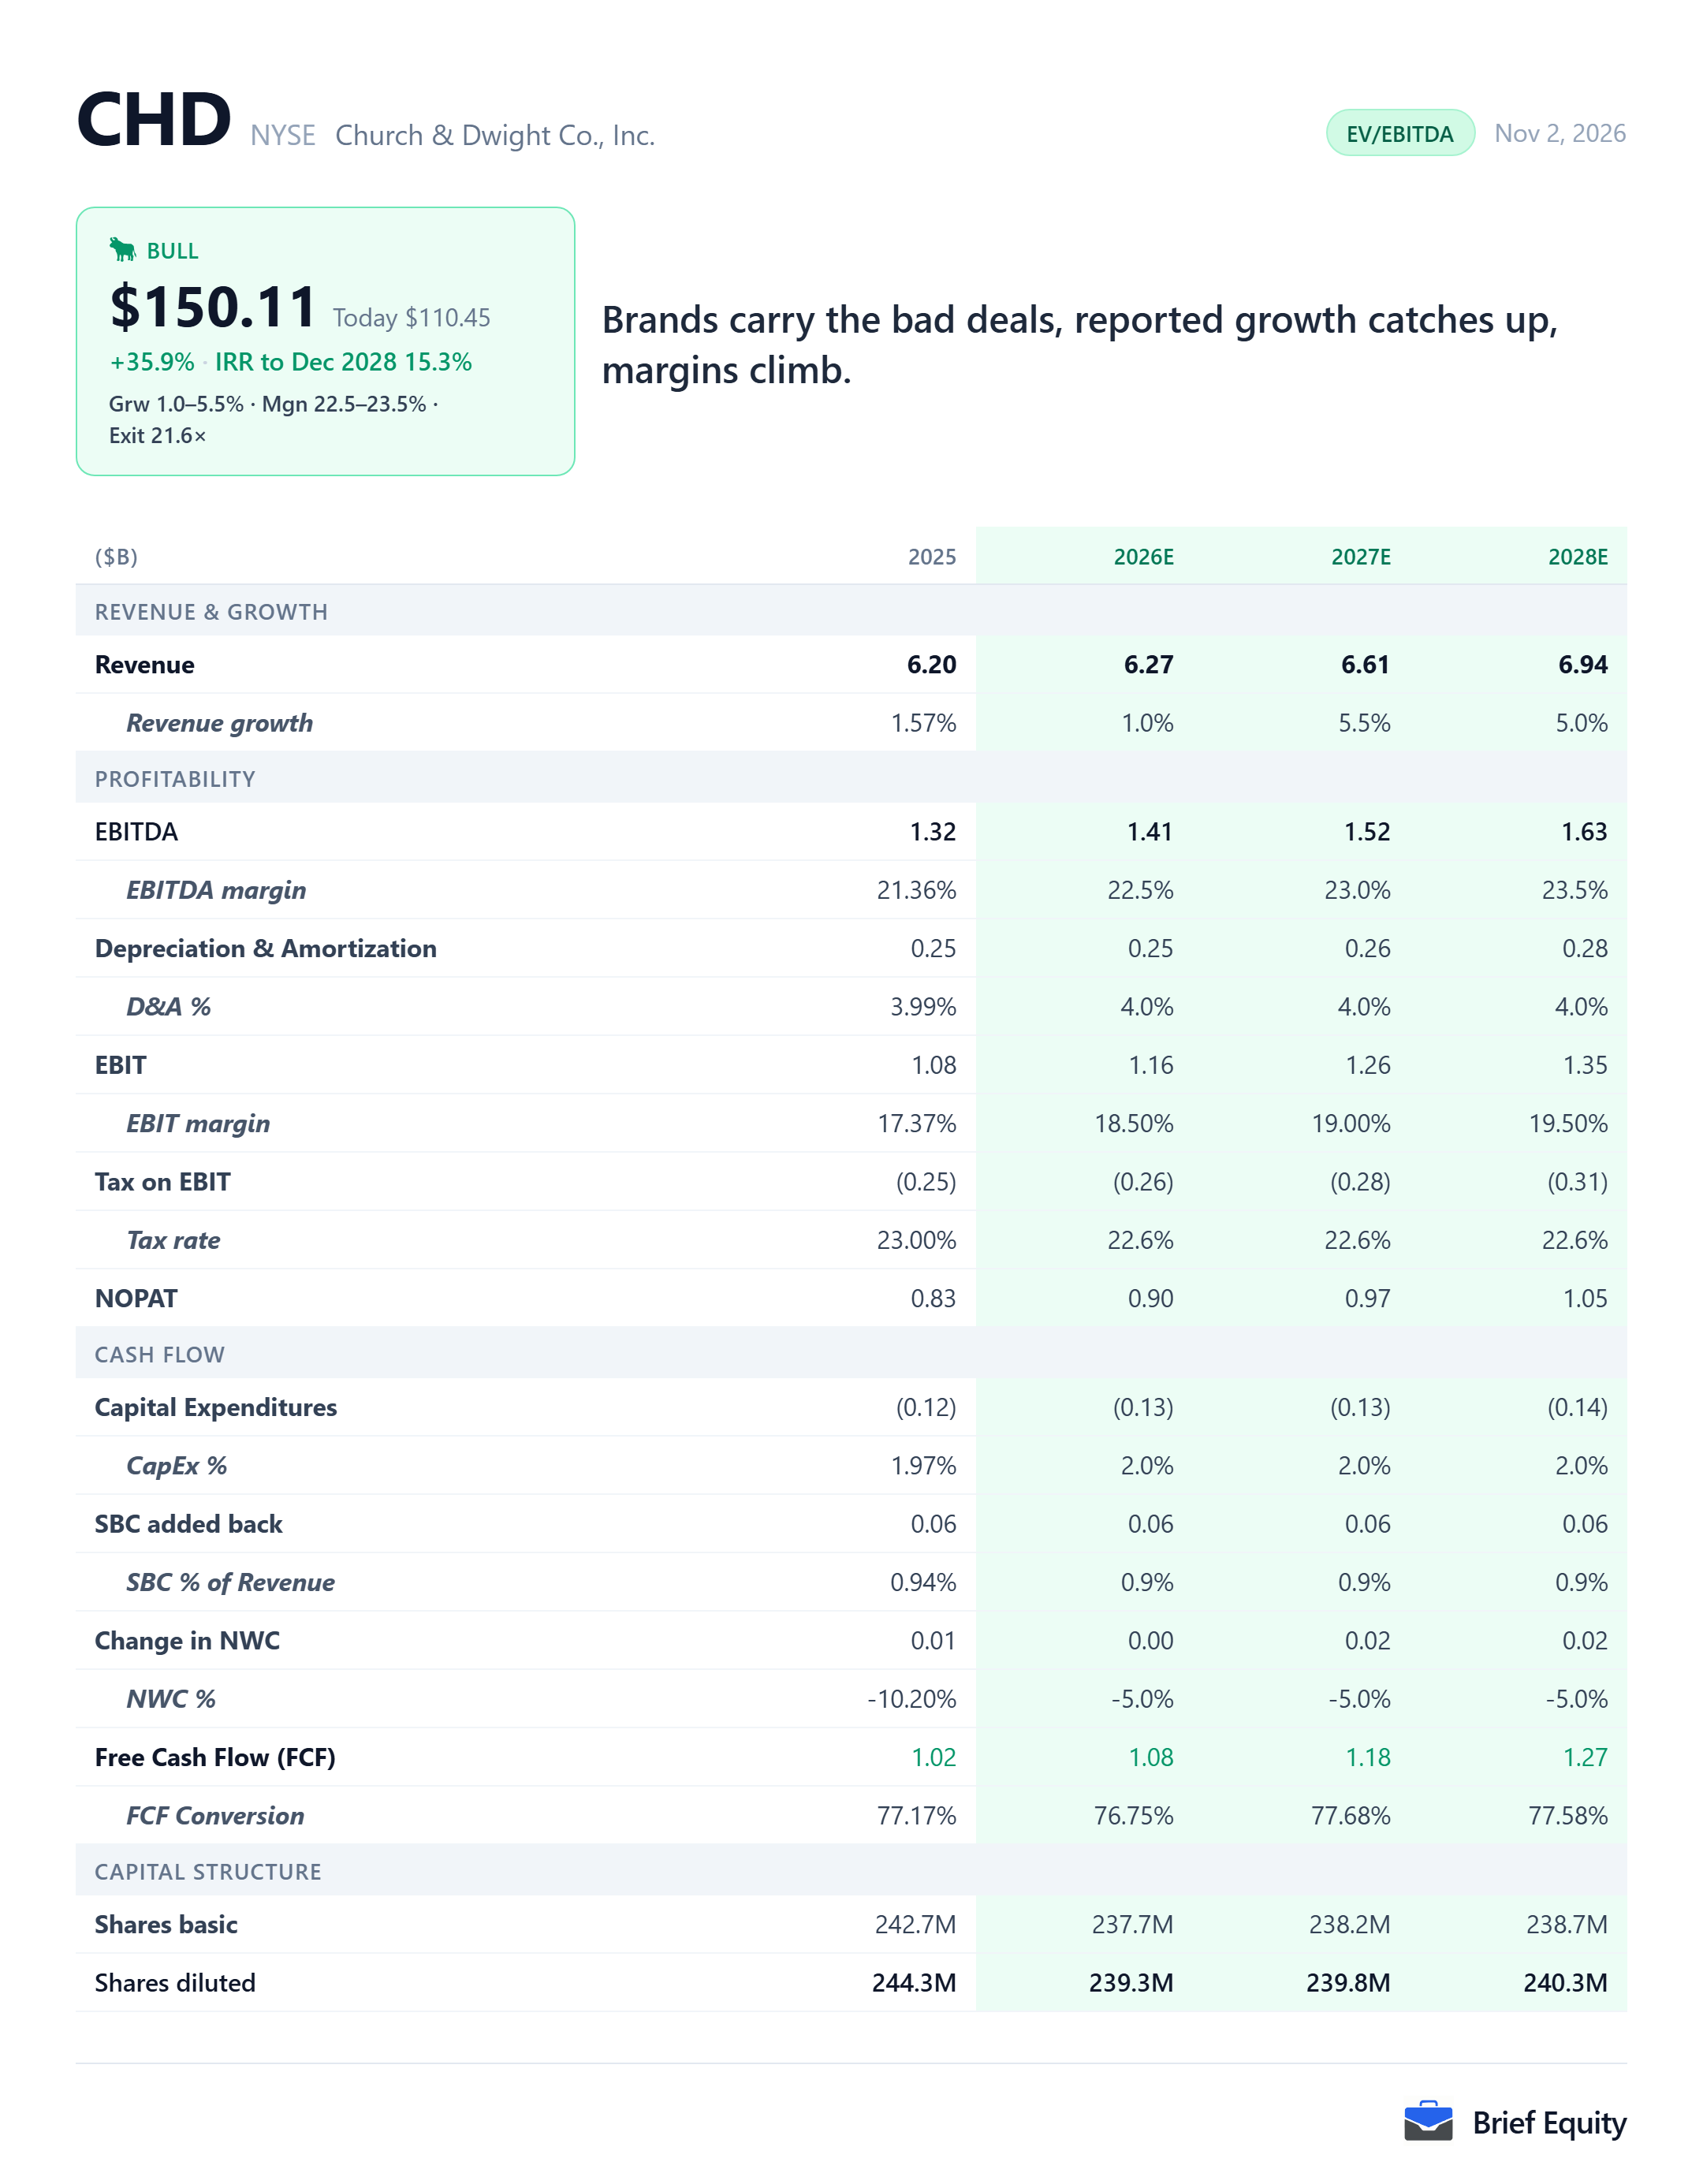
The model's assumptions for Church & Dwight
Church & Dwight's fiscal year is the calendar year, and the last year it has reported is 2025. The model runs three years, to 2028. Every row below is the model's own except the analyst consensus revenue.
| 2026 | 2027 | 2028 | |
|---|---|---|---|
| Net sales, model | 6.27 | 6.61 | 6.94 |
| Revenue growth, model | 1.0% | 5.5% | 5.0% |
| EBITDA, model | 1.41 | 1.52 | 1.63 |
| EBITDA margin, model | 22.5% | 23.0% | 23.5% |
| Net sales, analyst consensus | 6.24 | 6.51 | 6.76 |
Why Church & Dwight looks undervalued
Church & Dwight's organic sales grew 5.1% in the third quarter of 2026, well above the company's 3% outlook, mainly on higher volume.
Church & Dwight acquired THERABREATH in 2021, and on its third-quarter 2026 earnings call the company said the brand had reached a record 26.8% share of total mouthwash in the United States.
The model assumes Church & Dwight's revenue grows 5.5% in 2027 and 5.0% in 2028, against analyst consensus of 4.3% and 3.8%. It lifts the EBITDA margin from 22.5% in 2026 to 23.5% in 2028. With an exit multiple of 21.6 times EBITDA, the model values Church & Dwight at about $150 a share for 2028, about 36% above the share price.
Inflation could hold back Church & Dwight's rising margin. Its chief executive expects inflation to be quite large in 2027 and said it was too soon to give a margin target for that year.
“We always believe that we can expand margin. Just not ready to put that out there yet. It's about 2 or 3 months too soon.”
Richard Dierker, President and Chief Executive Officer, Church & Dwight third-quarter 2026 earnings call, October 30, 2026
What has to be true, and what would break it
Church & Dwight looks undervalued on this model if its brands keep growing at about 5% a year and its margin keeps rising.
What has to be true
- Church & Dwight's revenue grows 5.5% in 2027 and 5.0% in 2028, ahead of analyst consensus.
- Church & Dwight's brands keep growing mainly on volume, as they did in the third quarter of 2026.
- Church & Dwight's EBITDA margin rises from 22.5% in 2026 to 23.5% in 2028 despite cost inflation.
- The market pays about 21.6 times Church & Dwight's EBITDA at the end of 2028.
What would break it
- Inflation in 2027, which the chief executive expects to be quite large, keeps the EBITDA margin at or below 22.5%.
- Church & Dwight's organic sales growth falls well below the approximately 5% it expects for 2026.
- The market pays less than 21.6 times Church & Dwight's EBITDA at the end of 2028.
The parts of Church & Dwight's business
Church & Dwight reports its net sales in four parts. In 2025 sales grew in Personal Care Products and Consumer International and fell in Household Products and the Specialty Products Division, and the 2025 figures still include the businesses the company exited that year.
| Share of revenue | |
|---|---|
| Household Products | 41.2% |
| Personal Care Products | 35.8% |
| Consumer International | 18.2% |
| Specialty Products Division | 4.8% |
Church & Dwight beside its peers
Church & Dwight is compared here with six US-listed consumer products companies, chosen to cover its laundry, litter and oral care businesses and its model of buying brands.
- PG: Laundry and oral care
- CL: Oral care
- CLX: Cat litter and household cleaning
- PBH: A portfolio of acquired consumer health brands
- EPC: Acquired personal care brands
- REYN: Value household brands
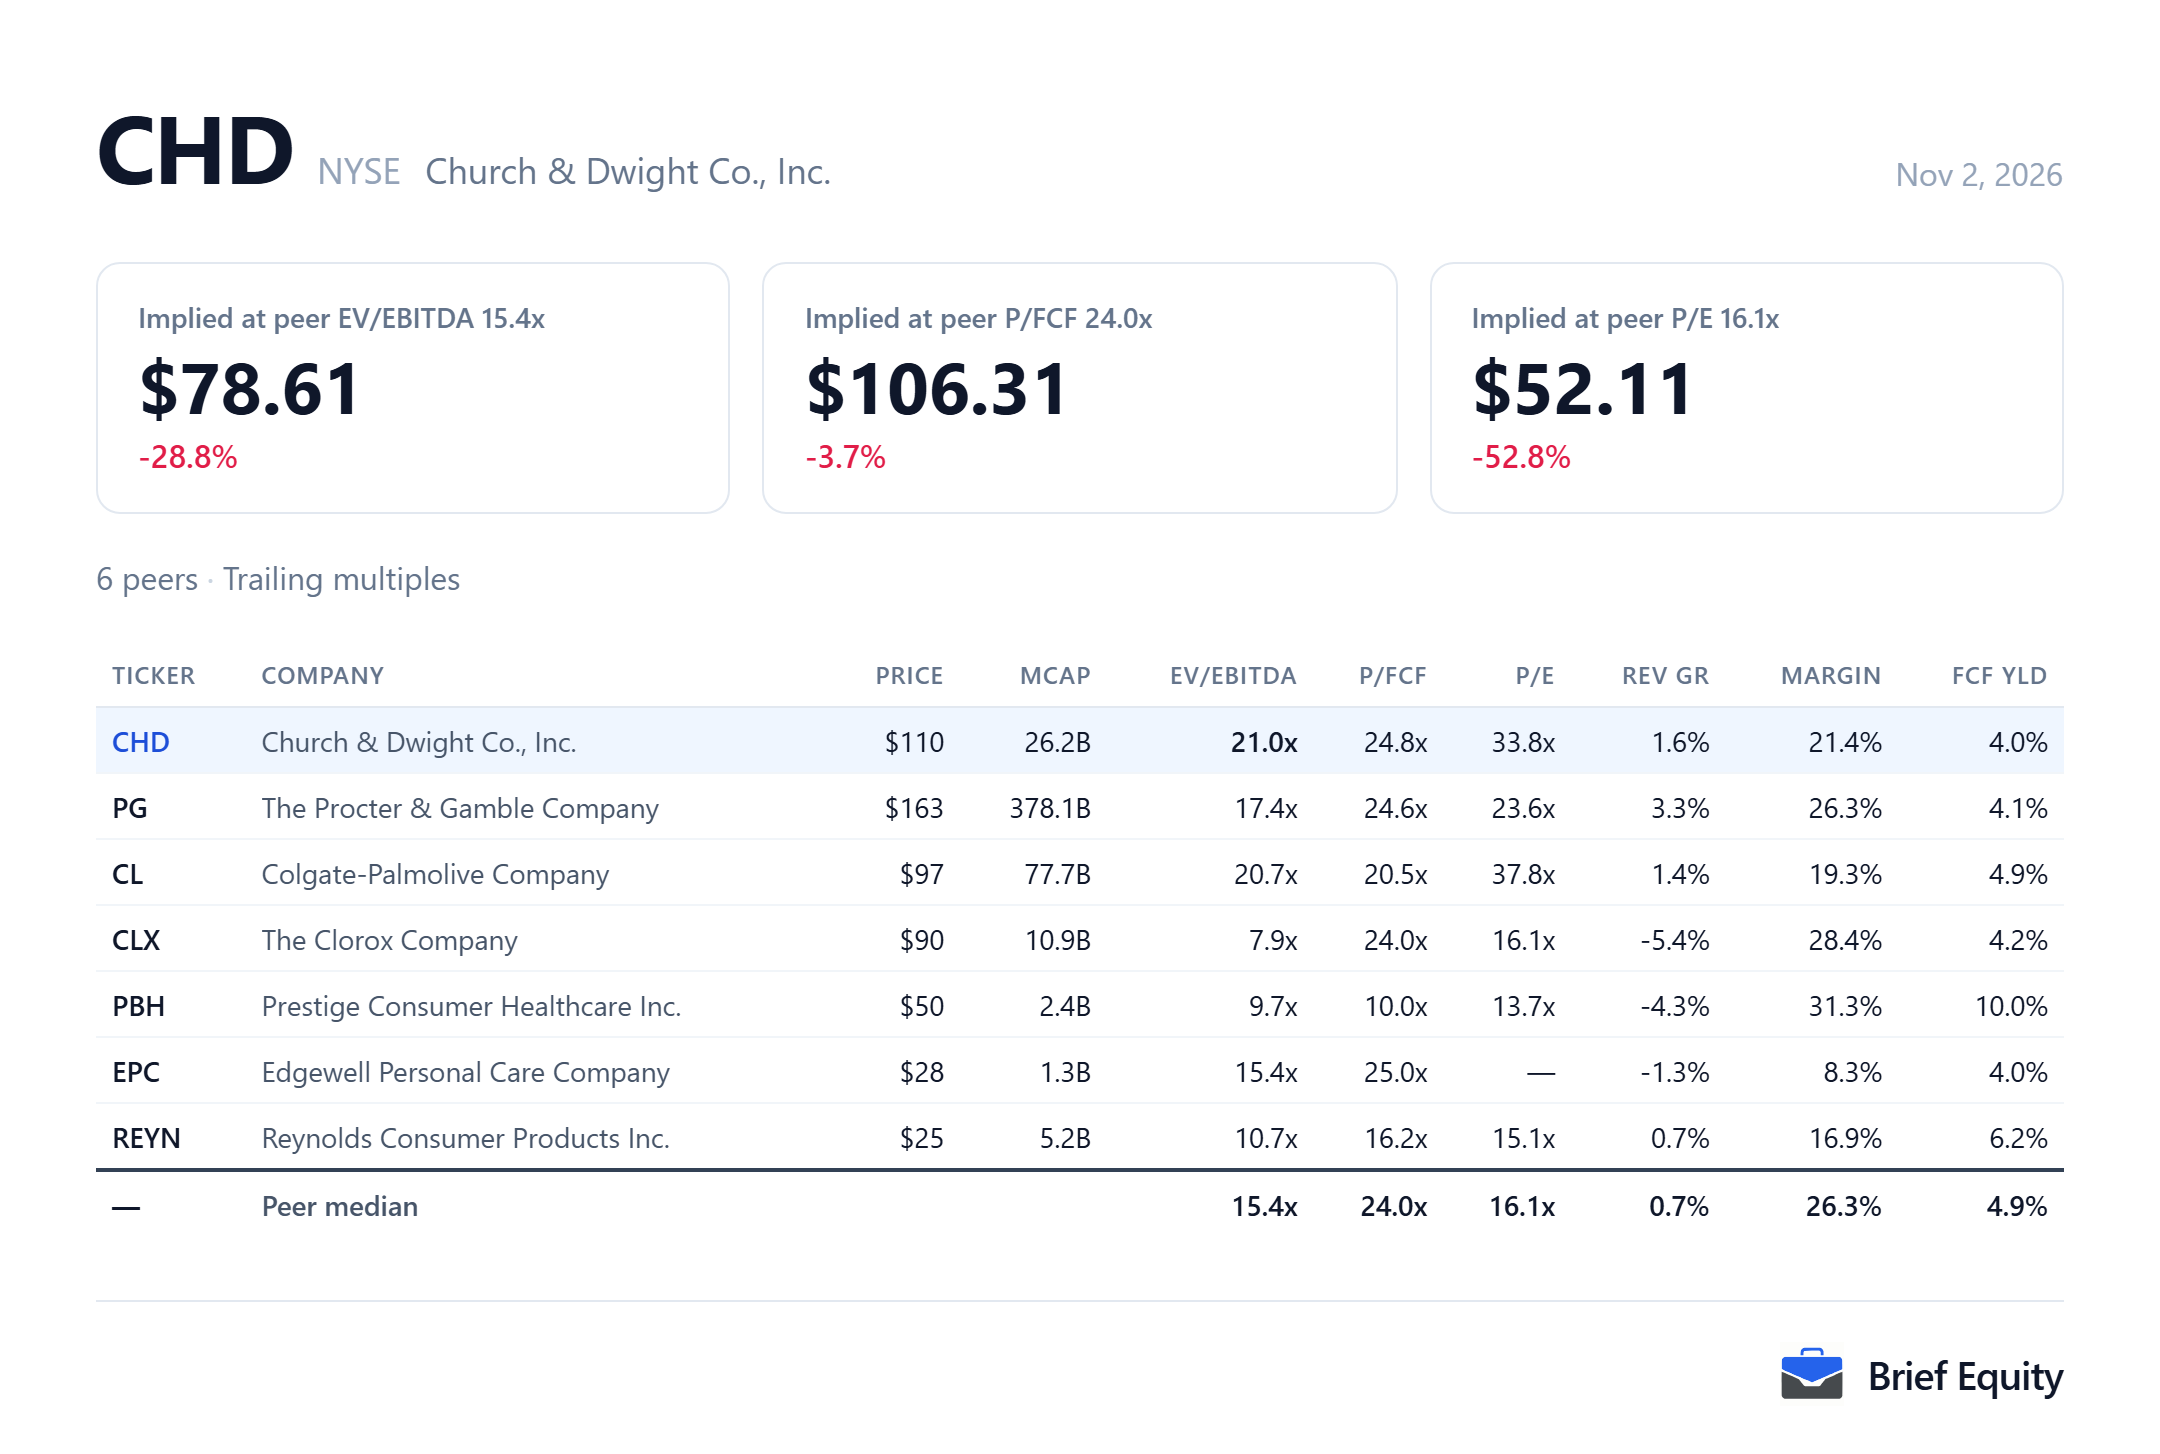
How the estimate moves with its assumptions
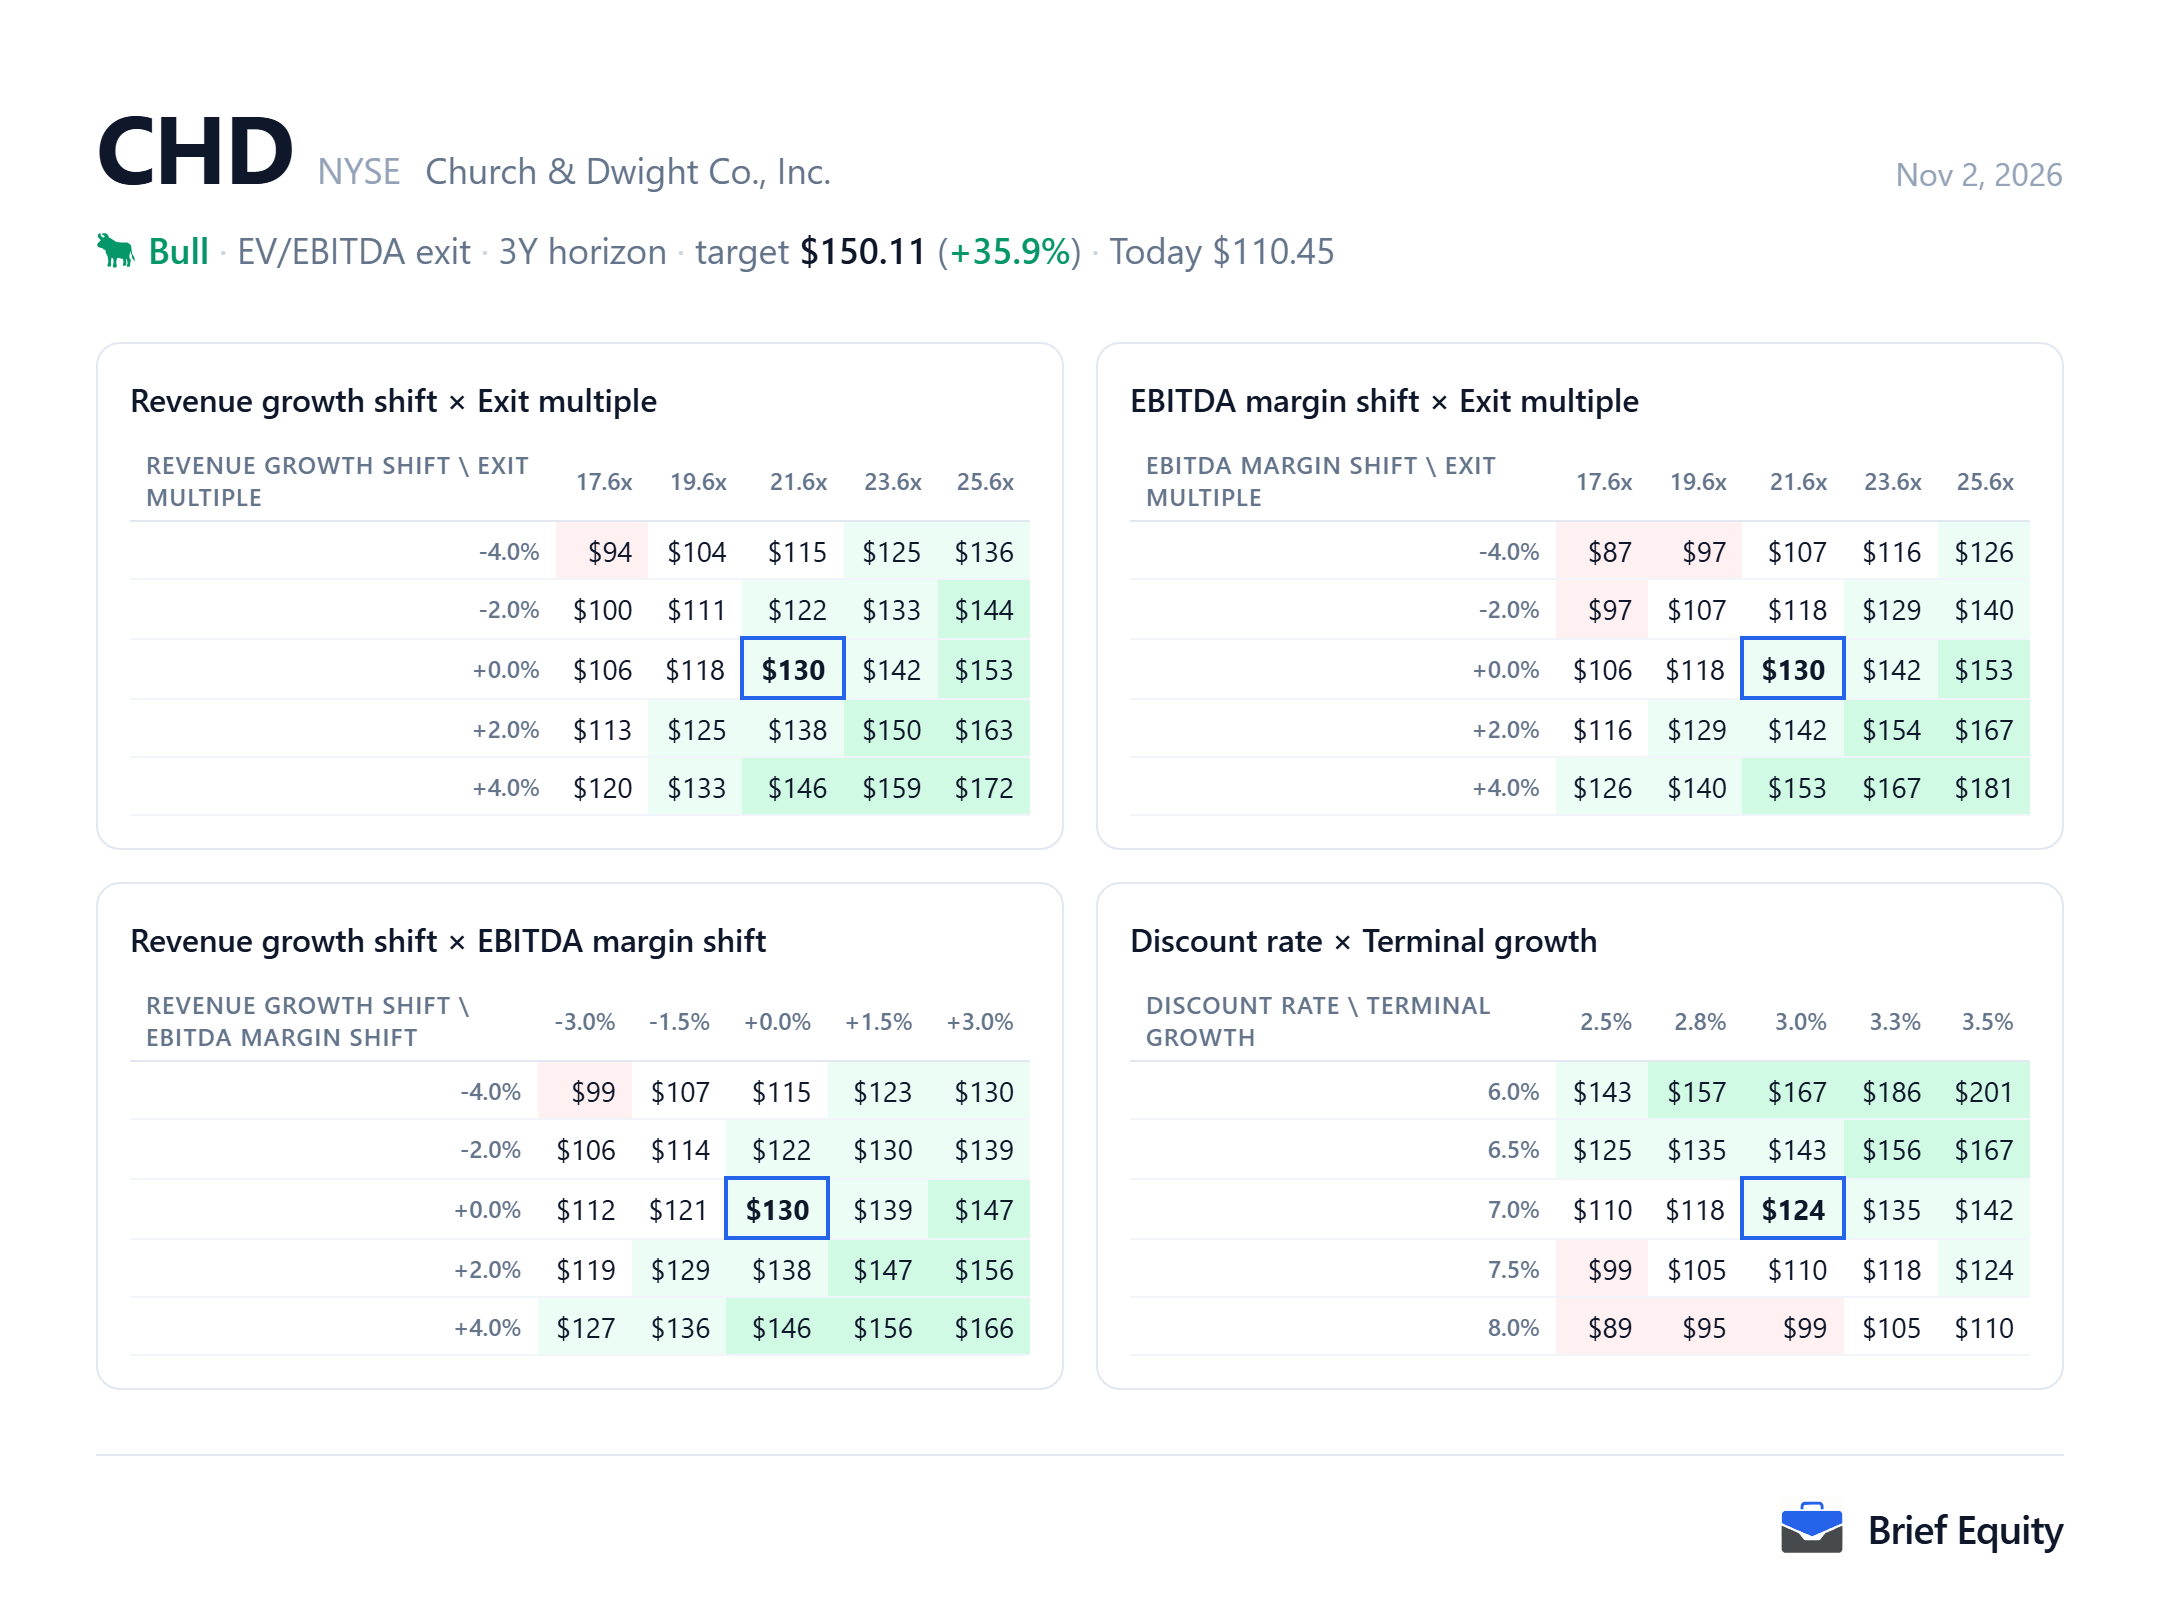
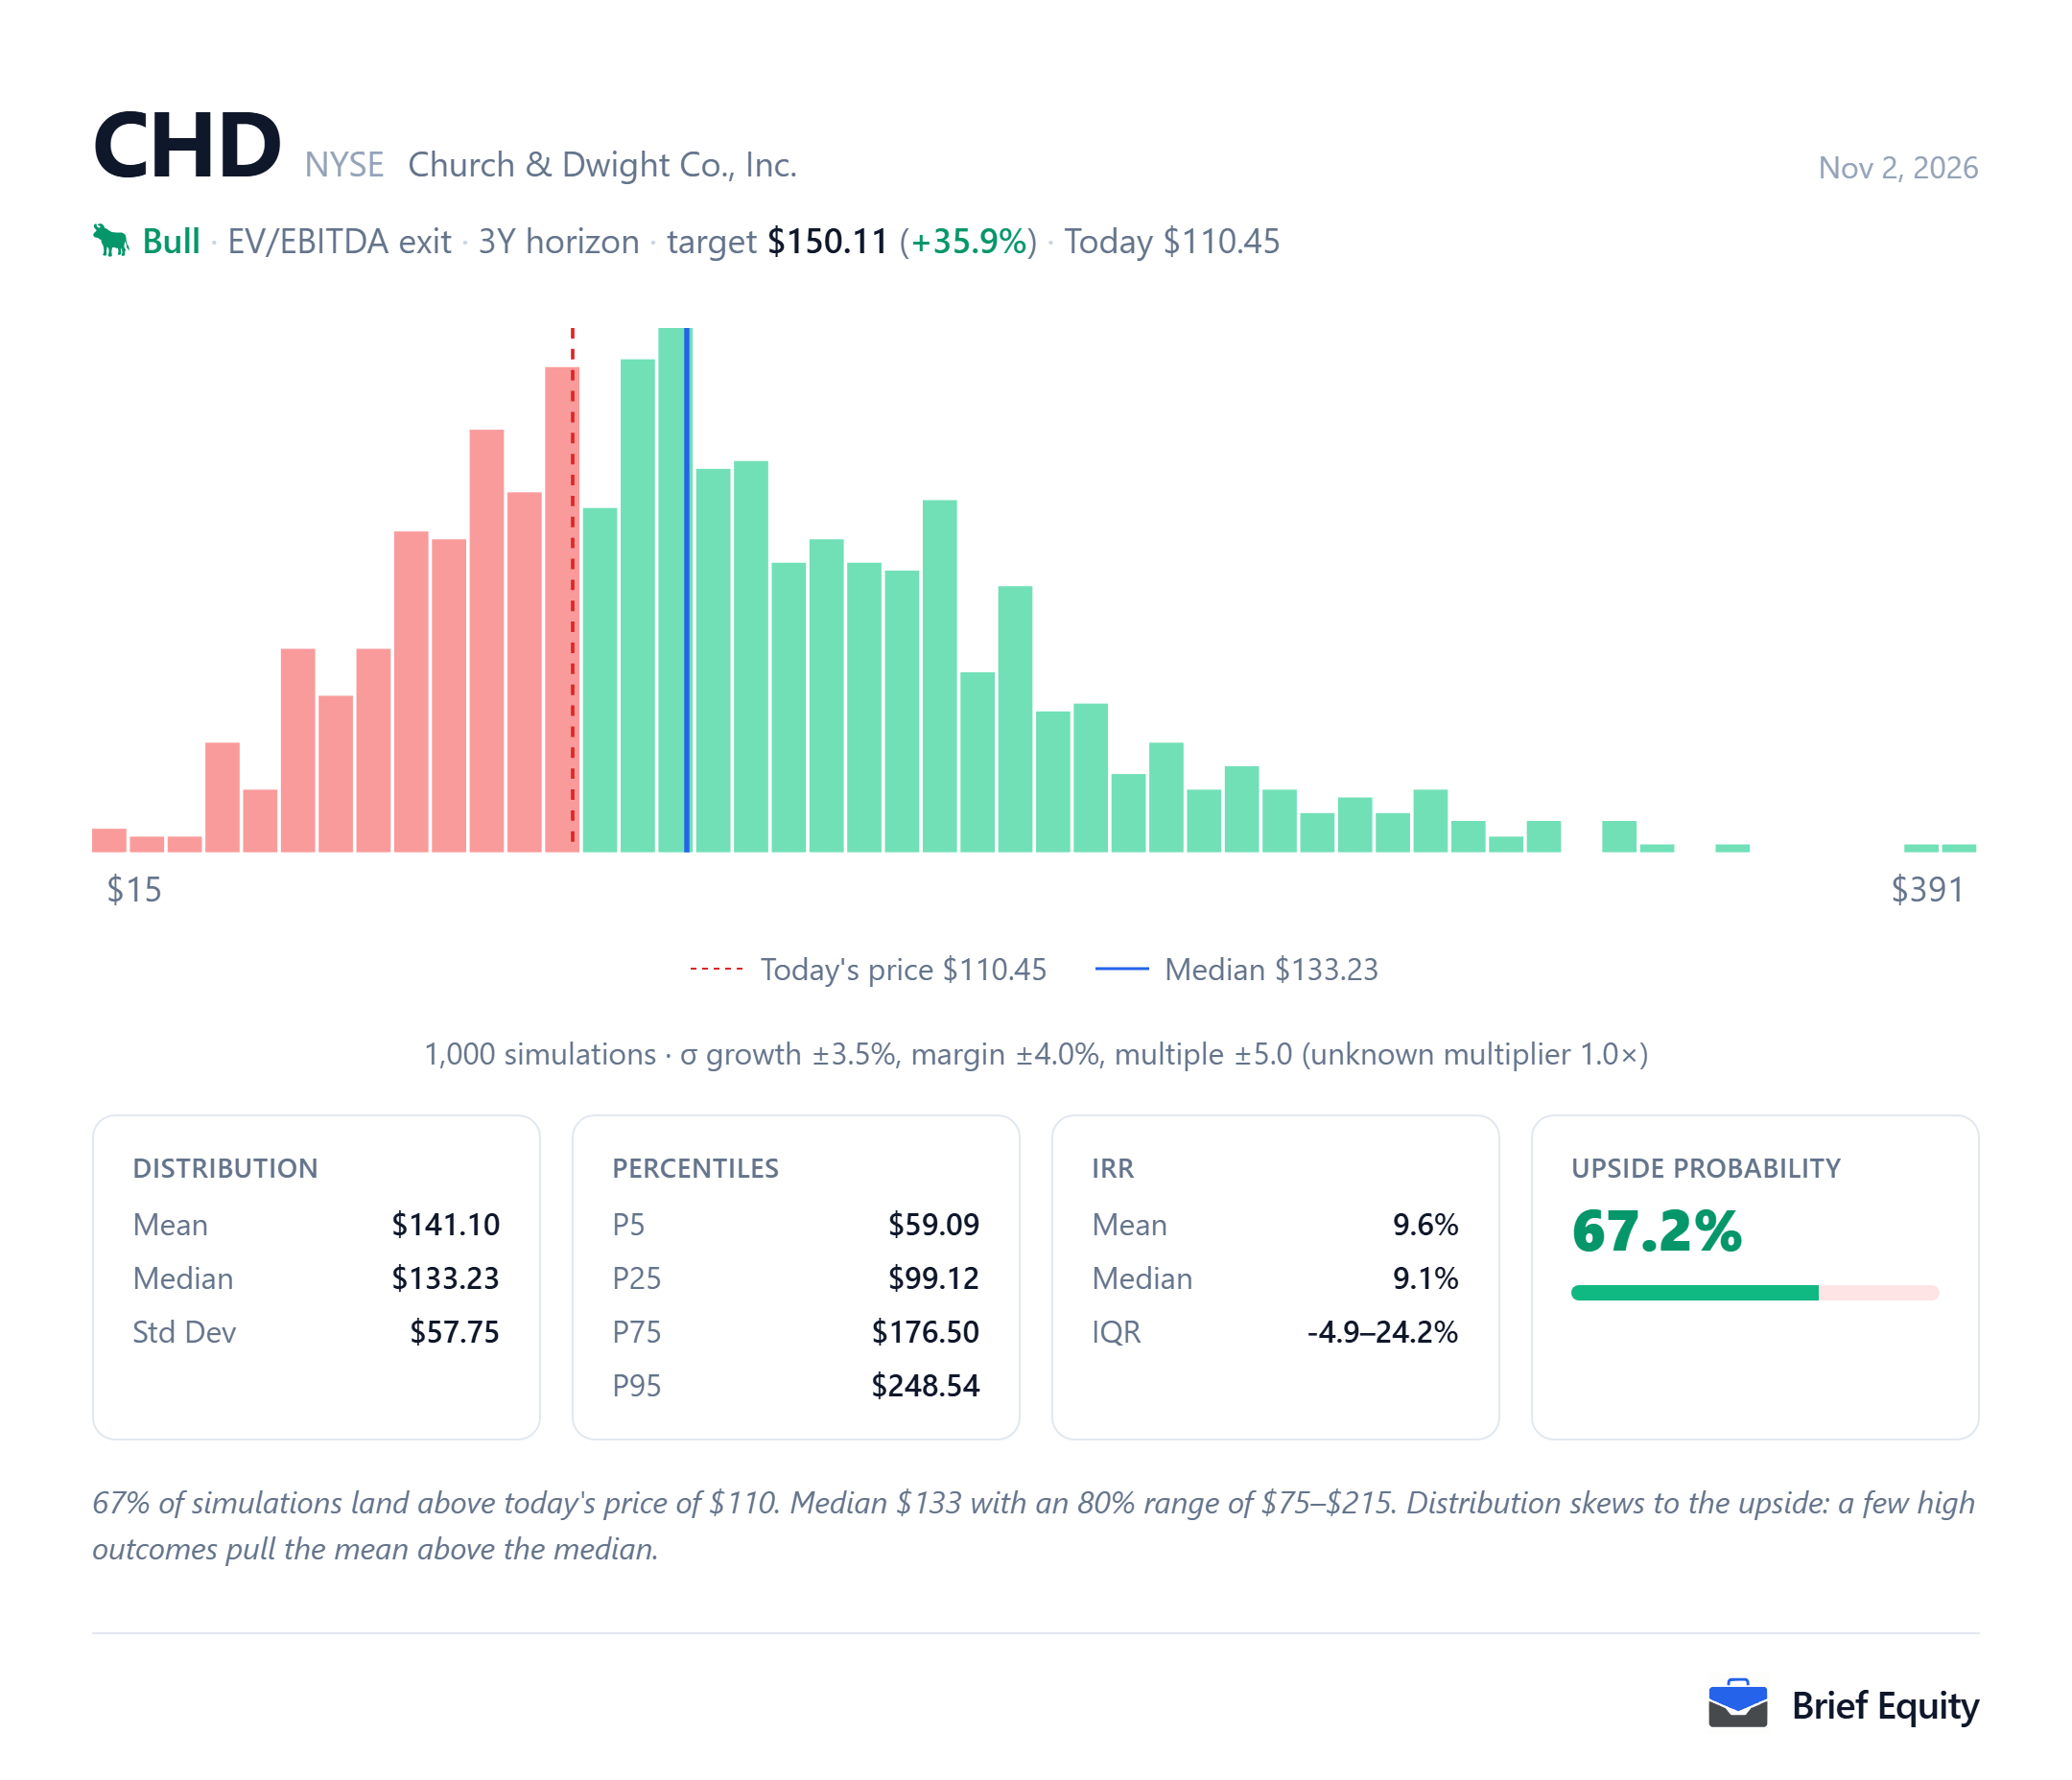
The two Church & Dwight cards below test the estimate: the sensitivity grids move two assumptions at a time, and the Monte Carlo card reruns the model many times with growth, margin and the exit multiple drawn at random.
Questions about Church & Dwight
These questions about Church & Dwight (CHD) are answered from the documents listed under Sources.
- Which brands are Church & Dwight's power brands?
- According to its annual report for 2025, Church & Dwight's seven power brands are ARM & HAMMER, OXICLEAN, TOUCHLAND, BATISTE, WATERPIK, THERABREATH and HERO.
- Who is Church & Dwight's largest customer?
- Walmart accounted for approximately 23% of Church & Dwight's net sales in each of 2025, 2024 and 2023. Its top four customers accounted for approximately 44% of net sales in 2025.
- What earnings growth does Church & Dwight expect for 2026?
- As of October 30, 2026, Church & Dwight expected full-year reported EPS to increase approximately 20% in 2026 and adjusted EPS to grow 7%.
- How much cash does Church & Dwight expect to generate in 2026?
- As of October 30, 2026, Church & Dwight expected approximately $1.175 billion of cash from operations for 2026, and full-year capital expenditures of approximately $125 million.
- How much debt does Church & Dwight have?
- As of September 30, 2026, Church & Dwight's total debt was $2.2 billion and its cash on hand was $447 million.
- What are Church & Dwight's long-term growth targets?
- Church & Dwight's annual report for 2025 sets targets to grow ARM & HAMMER from a $2 billion brand to a $3 billion brand, global oral care from $1 billion to $1.5 billion behind TheraBreath, and its international business from $1 billion to $2 billion.
Sources
The quotations and facts about Church & Dwight (CHD) on this page rest on the documents below.
- Church & Dwight annual report on Form 10-K for 2025, February 12, 2026
- Church & Dwight quarterly report on Form 10-Q for the third quarter of 2026, October 30, 2026
- Church & Dwight third-quarter 2026 results release, October 30, 2026
- Church & Dwight third-quarter 2026 earnings call, October 30, 2026
About this page
Brief Equity and its team hold no position in Church & Dwight (CHD) as of November 2, 2026.
This page is research, not investment advice. It describes one model and the assumptions behind it, and market data is delayed. Read how these models are built and our editorial policy.
Related guides: How to read a 10-K (SEC filing), Where to read earnings transcripts and filings in one place, How to value a stock yourself (without Excel).