Valuation · EV/EBITDA model
Is ASML (ASML) stock undervalued?
Brief Equity's quick EV/EBITDA model of ASML, dated October 14, 2026, puts the shares at about $3,489 for 2028, against a price of $1,650.00 that day. On those assumptions ASML looks cheap, with the model's value about 112% above the price. The view holds unless a major slowdown in AI investment cuts the demand for its machines and investors pull away from the shares.
By The Brief Equity Team · Model dated · Published
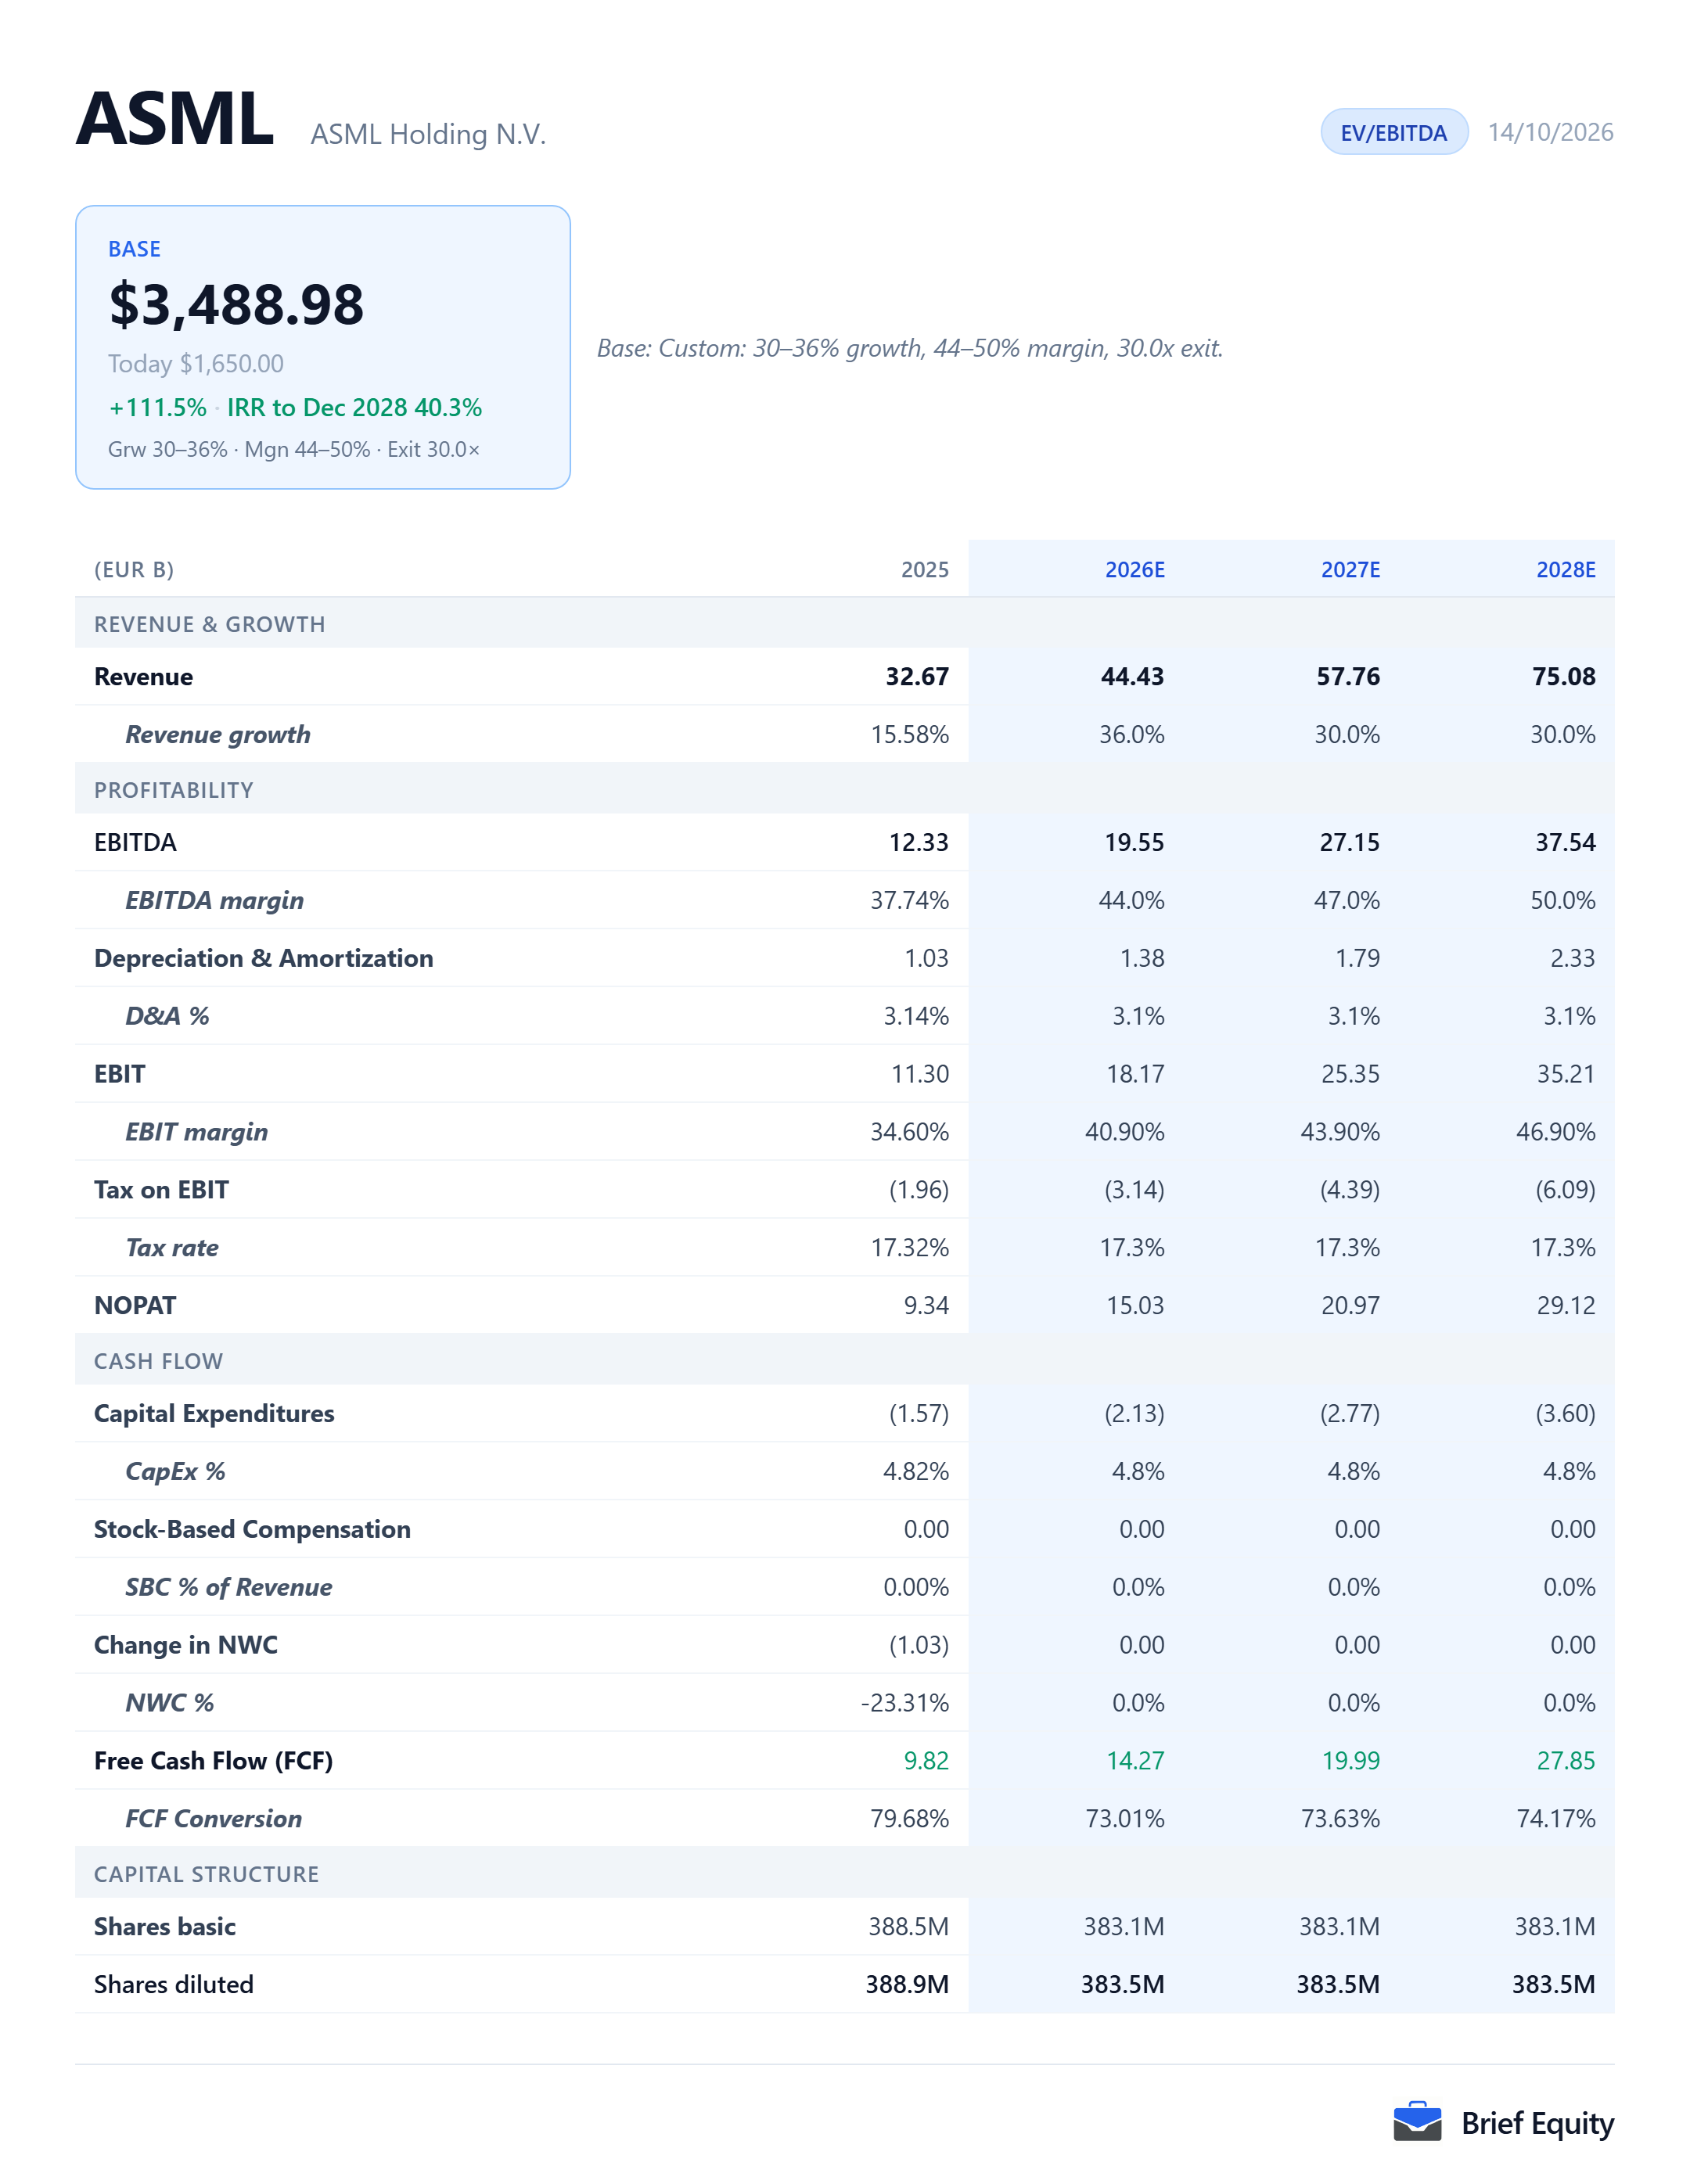
The model's assumptions for ASML
ASML's fiscal year is the calendar year and it reports in euros, so the tables below are in euros, while the share price and the model's value are in US dollars on its Nasdaq listing. The model runs three years, to 2028, and the second table sets the model's revenue beside analyst consensus revenue for the same years.
Reports in EUR. Price and per-share values in USD at 1.1173.
| 2026 | 2027 | 2028 | |
|---|---|---|---|
| Revenue, model | 44.43 | 57.76 | 75.08 |
| Revenue growth, model | 36.0% | 30.0% | 30.0% |
| EBITDA, model | 19.55 | 27.15 | 37.54 |
| EBITDA margin, model | 44.0% | 47.0% | 50.0% |
| 2026 | 2027 | 2028 | |
|---|---|---|---|
| Revenue, model | 44.43 | 57.76 | 75.08 |
| Revenue, analyst consensus | 44.13 | 56.52 | 69.11 |
Why ASML looks undervalued
ASML said on October 14, 2026, with its third-quarter results, that the supply it plans for 2027 and 2028 will not fully meet its customers' demand, even though it plans 30% more low-NA EUV and DUV immersion capacity for 2027, and that some customers want to place orders for 2029 and 2030. On this model, ASML looks cheap at $1,650.00.
“With such strong visibility and an order book momentum that continues to increase quarter on quarter this year, we now expect that our supply as currently planned for both 2027 and 2028 will not fully meet the demand of our customers”
ASML third-quarter 2026 financial results press release, October 14, 2026
ASML's revenue in the model grows 36% in 2026, in line with the company's own expectation of about 36% growth for the year, and then 30% in 2027 and in 2028, on the assumption that ASML sells all the machines it can build. Analyst consensus has revenue growth of 22.3% for 2028.
ASML's customers are also paying in advance. Its non-current contract liabilities, which its chief financial officer described on the third-quarter call as a proxy for orders, rose from EUR 3,570.3 million to EUR 9,300.6 million during the third quarter of 2026. ASML has also agreed price increases on its most critical products, with the full effect from 2028, and its chief executive said this had not happened in many years.
“If you go back many, many years back this is something we never did.”
Christophe D. Fouquet, President and Chief Executive Officer, ASML third-quarter 2026 earnings call, October 14, 2026
The model therefore has ASML's EBITDA margin rising from 44% in 2026 to 50% in 2028. ASML's operating margin was 44.4% in the third quarter of 2026. At 30 times 2028 EBITDA, the shares come to about $3,489 in 2028, about 112% above the price.
The view on ASML fails if there is a major slowdown in AI investment and investors pull away from the shares.
What has to be true, and what would break it
ASML looks cheap on this model only while a few things hold, and the view fails if they stop holding.
What has to be true
- ASML's customers keep taking every lithography system it can build through 2028, as ASML said on October 14, 2026 that its planned supply for 2027 and 2028 will not fully meet their demand.
- The price increases ASML agreed on its most critical products reach their full effect from 2028, as the company said they would.
What would break it
- A major slowdown in AI investment leads ASML's customers to cut or delay their orders.
- Investors pay much less for the shares than the 30 times 2028 EBITDA the model uses.
The parts of ASML's business
ASML reports its sales by type of system and service, and in 2025 its low-NA EUV systems accounted for the largest share of the year's growth, while its KrF, ArF dry and I-line systems shrank.
| Share of revenue | Share of revenue growth | |
|---|---|---|
| NXE (EUV 0.33 NA) | 32.0% | 58.8% |
| ArF immersion | 31.6% | 14.6% |
| Installed Base Management | 25.1% | 38.6% |
| EXE (EUV 0.55 NA) | 3.5% | 15.7% |
| KrF | 3.1% | |
| Metrology & Inspection | 2.5% | 4.1% |
| ArF dry | 1.3% | |
| I-line | 0.9% |
ASML beside its peers
ASML is compared here with three makers of chipmaking equipment, chosen to cover its lithography systems, the memory build-out and its metrology and service business.
- LRCX: Etch and deposition equipment, standing for the memory build-out
- AMAT: Wafer fabrication equipment, against ASML's systems in the same fab budgets
- KLAC: Process control and metrology, against ASML's Metrology & Inspection and service business
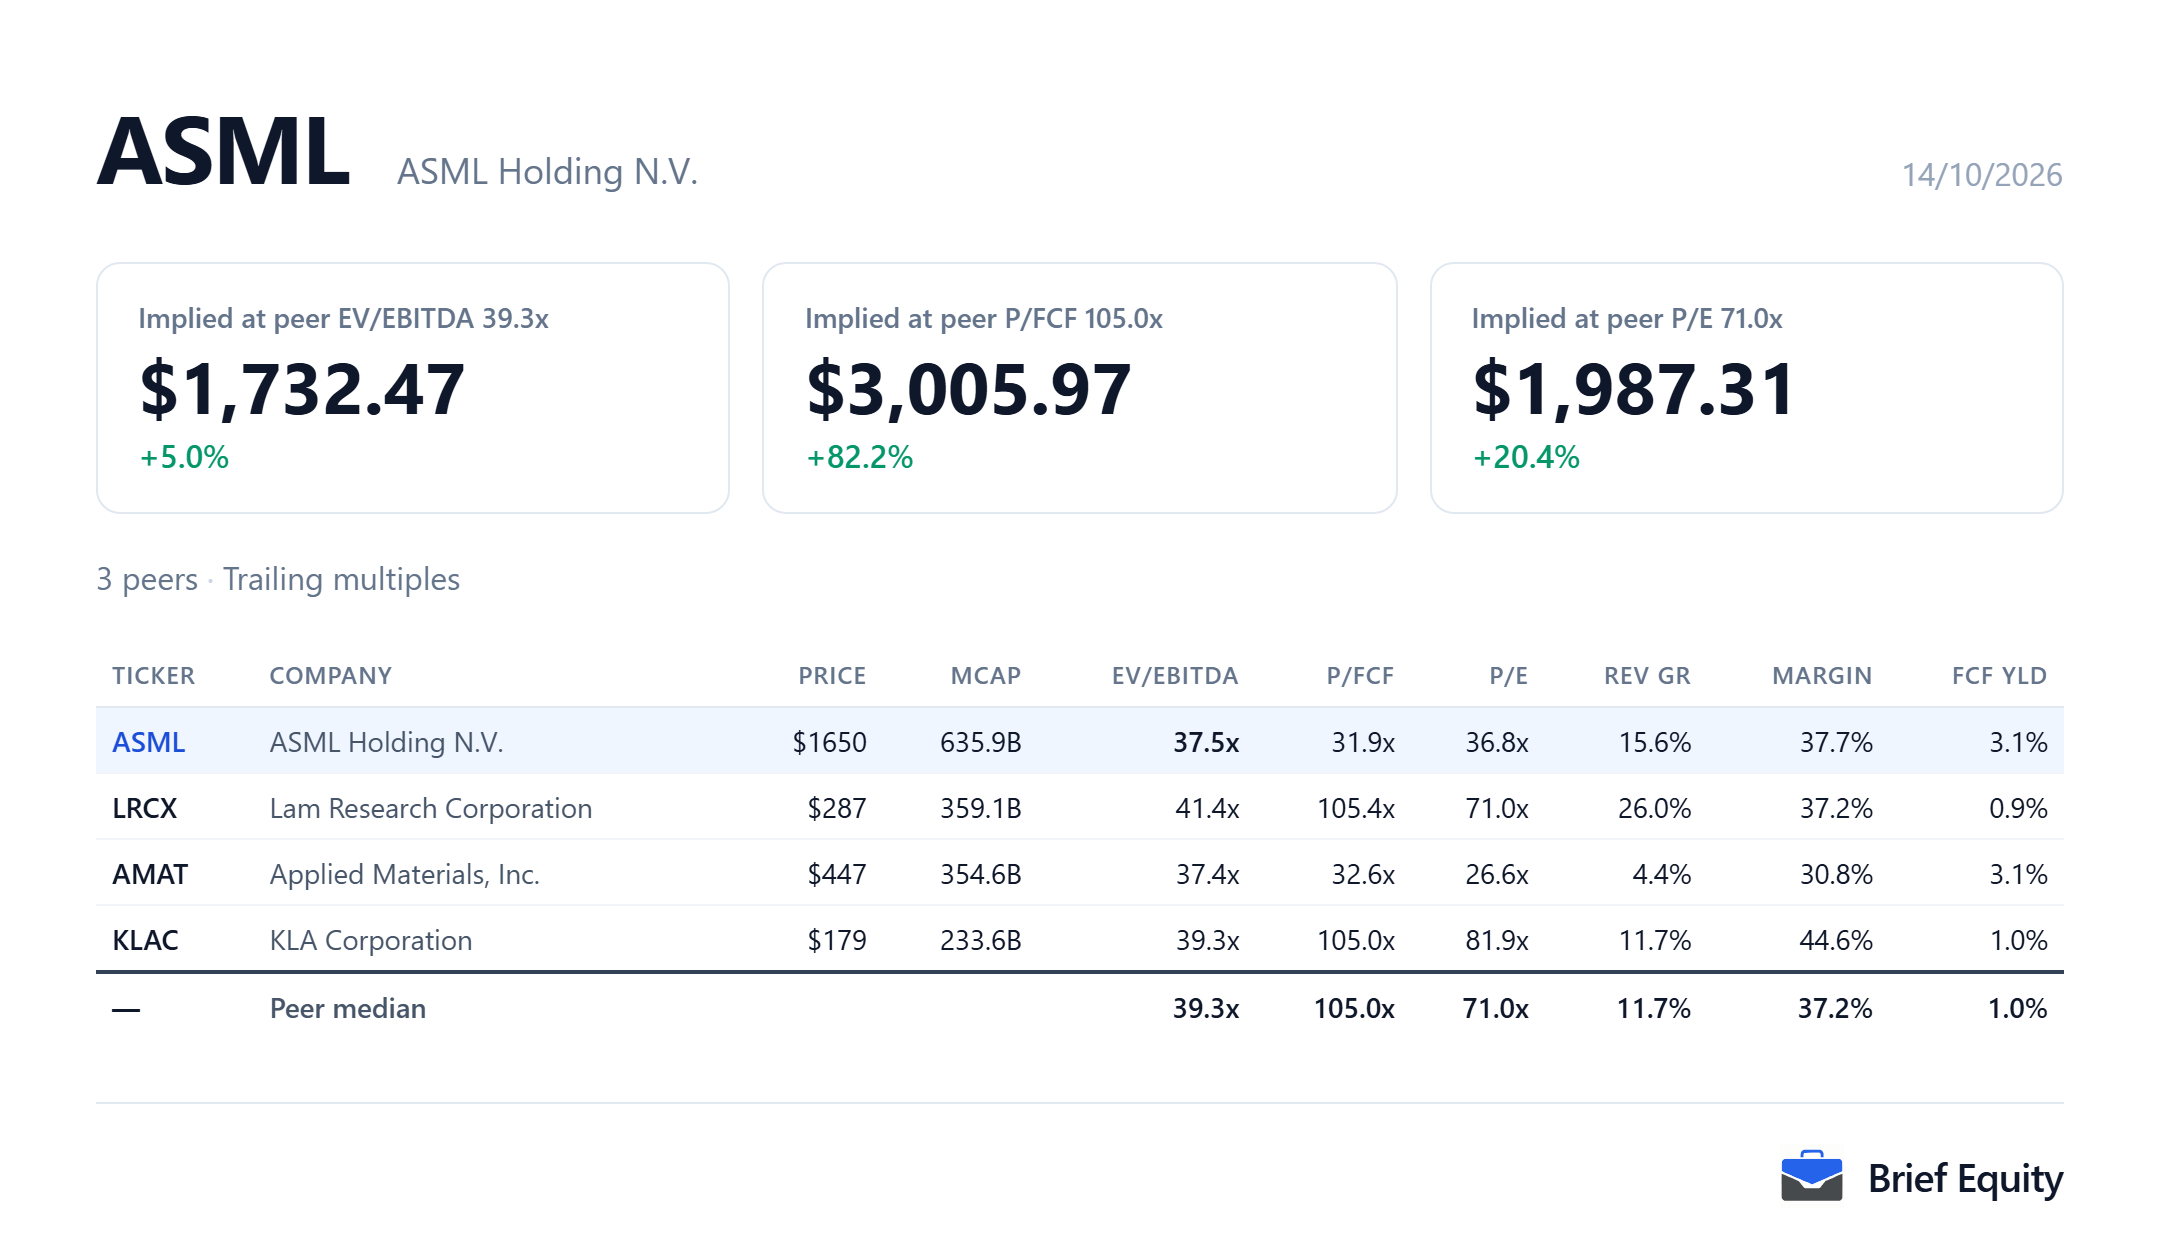
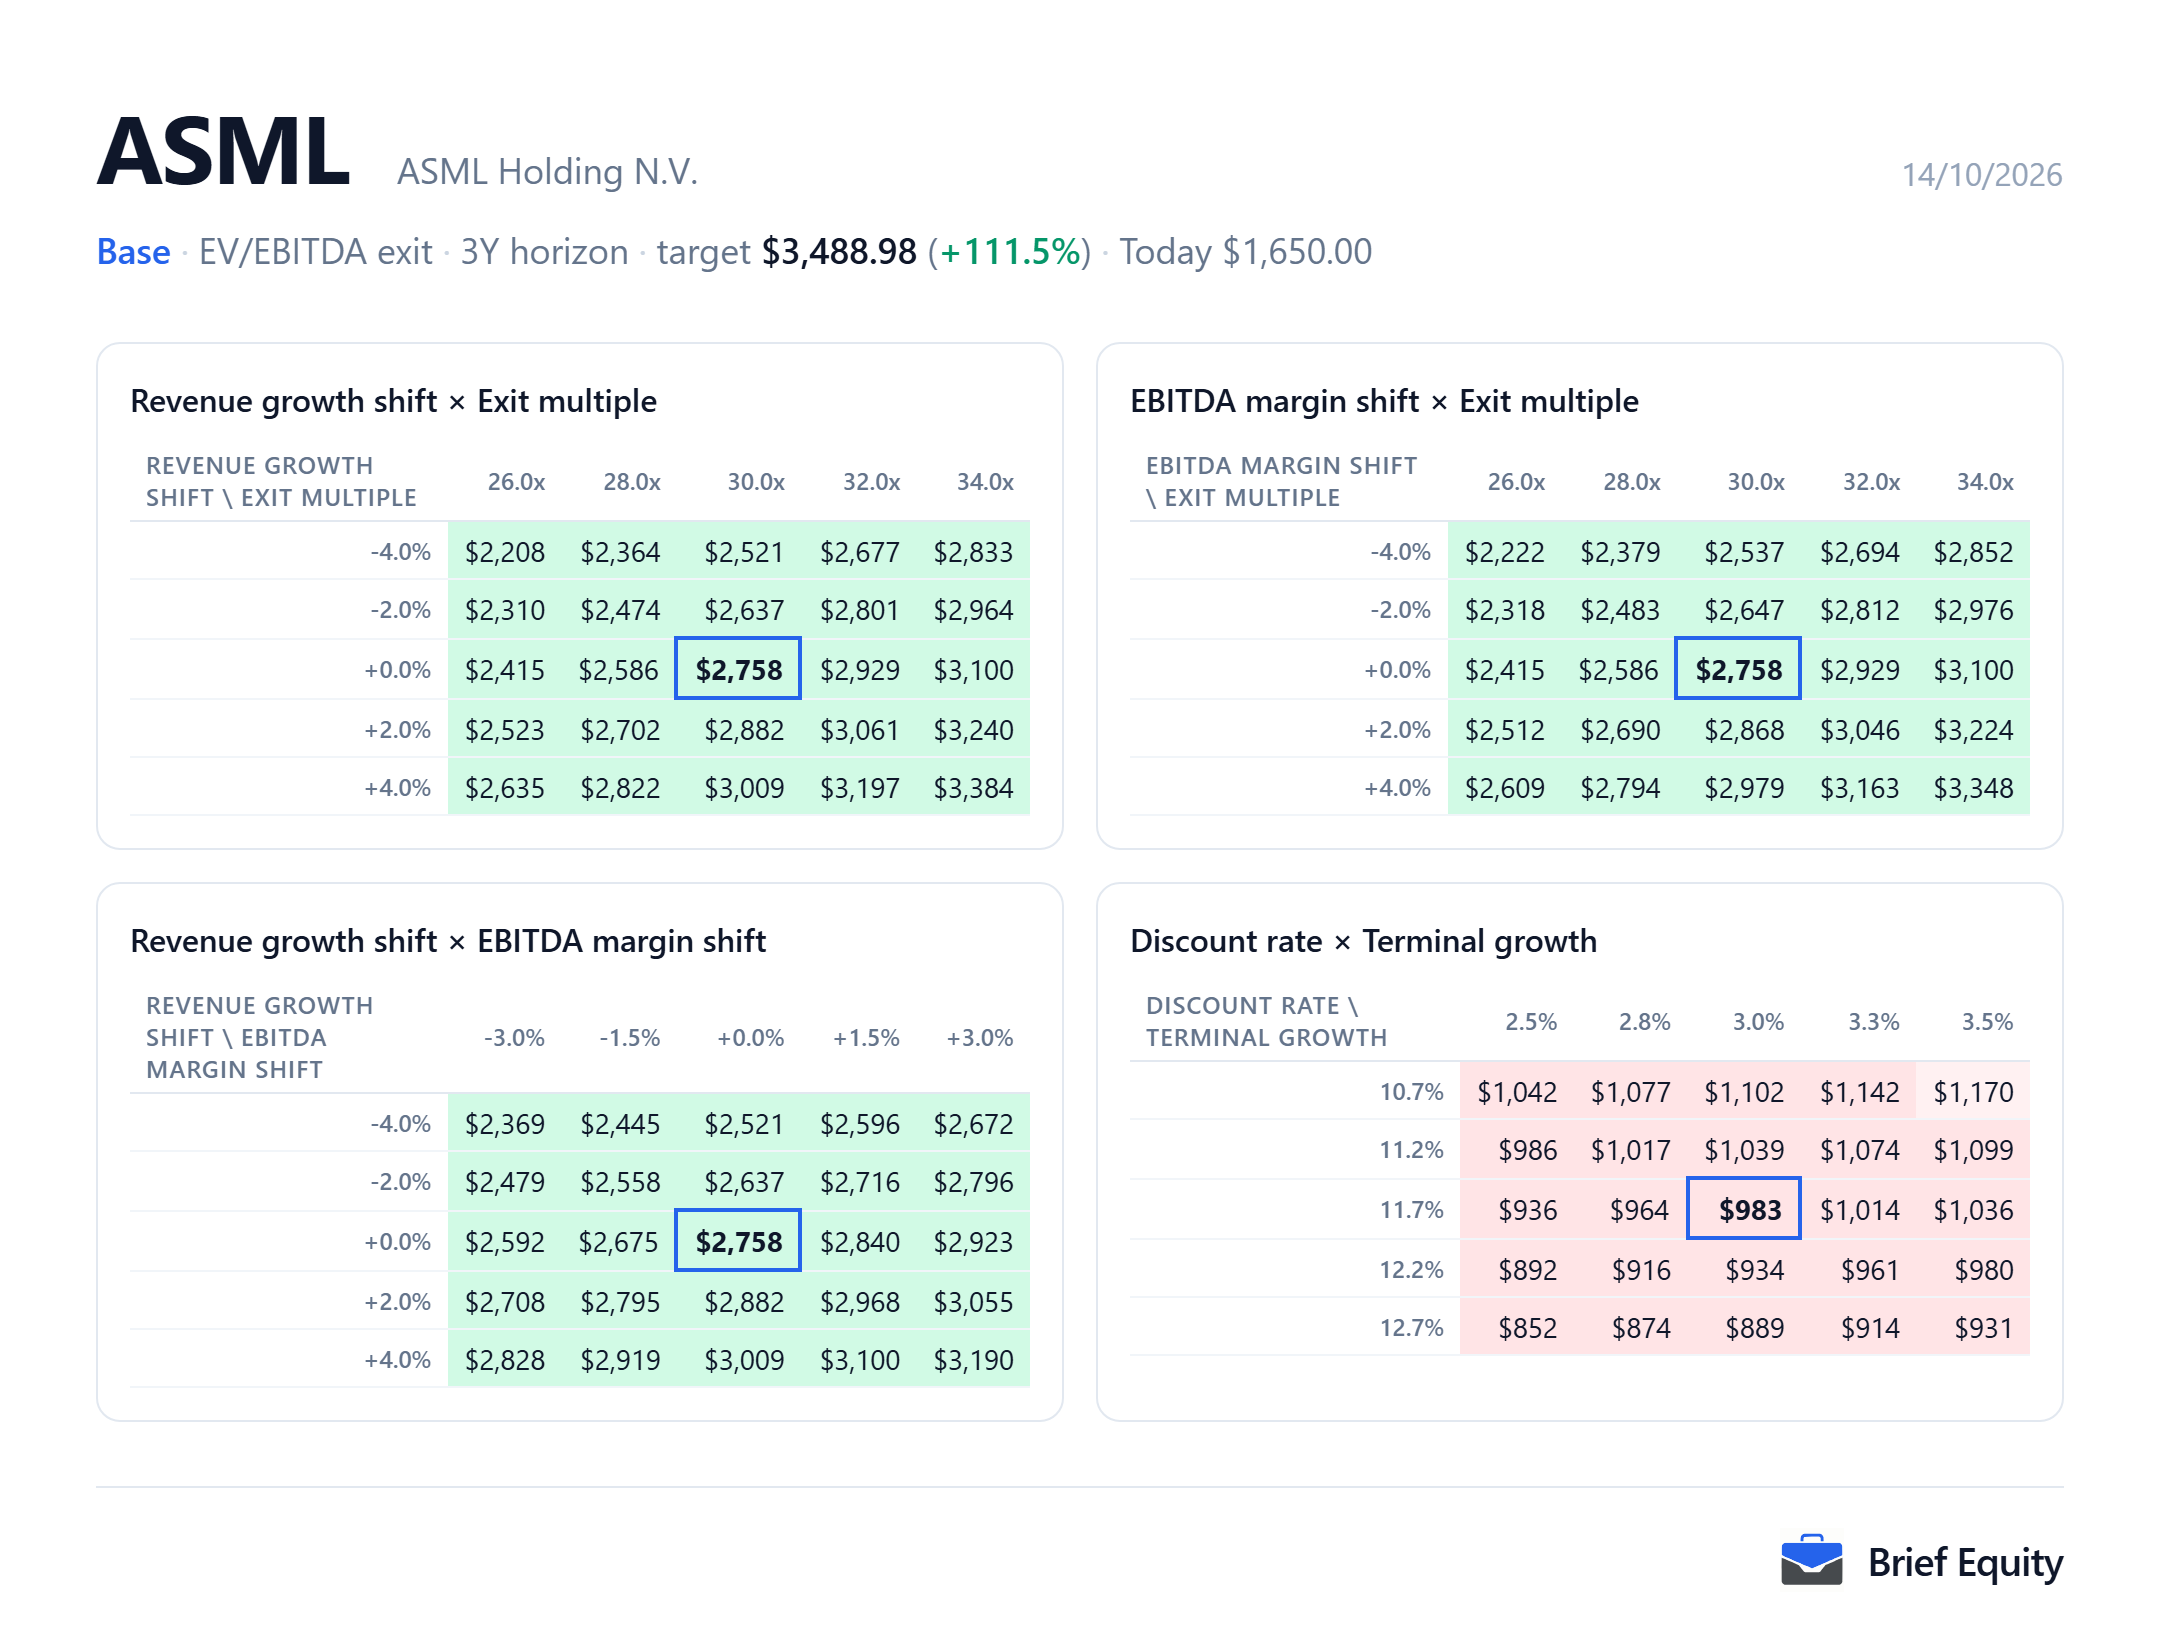
How the estimate moves with its assumptions
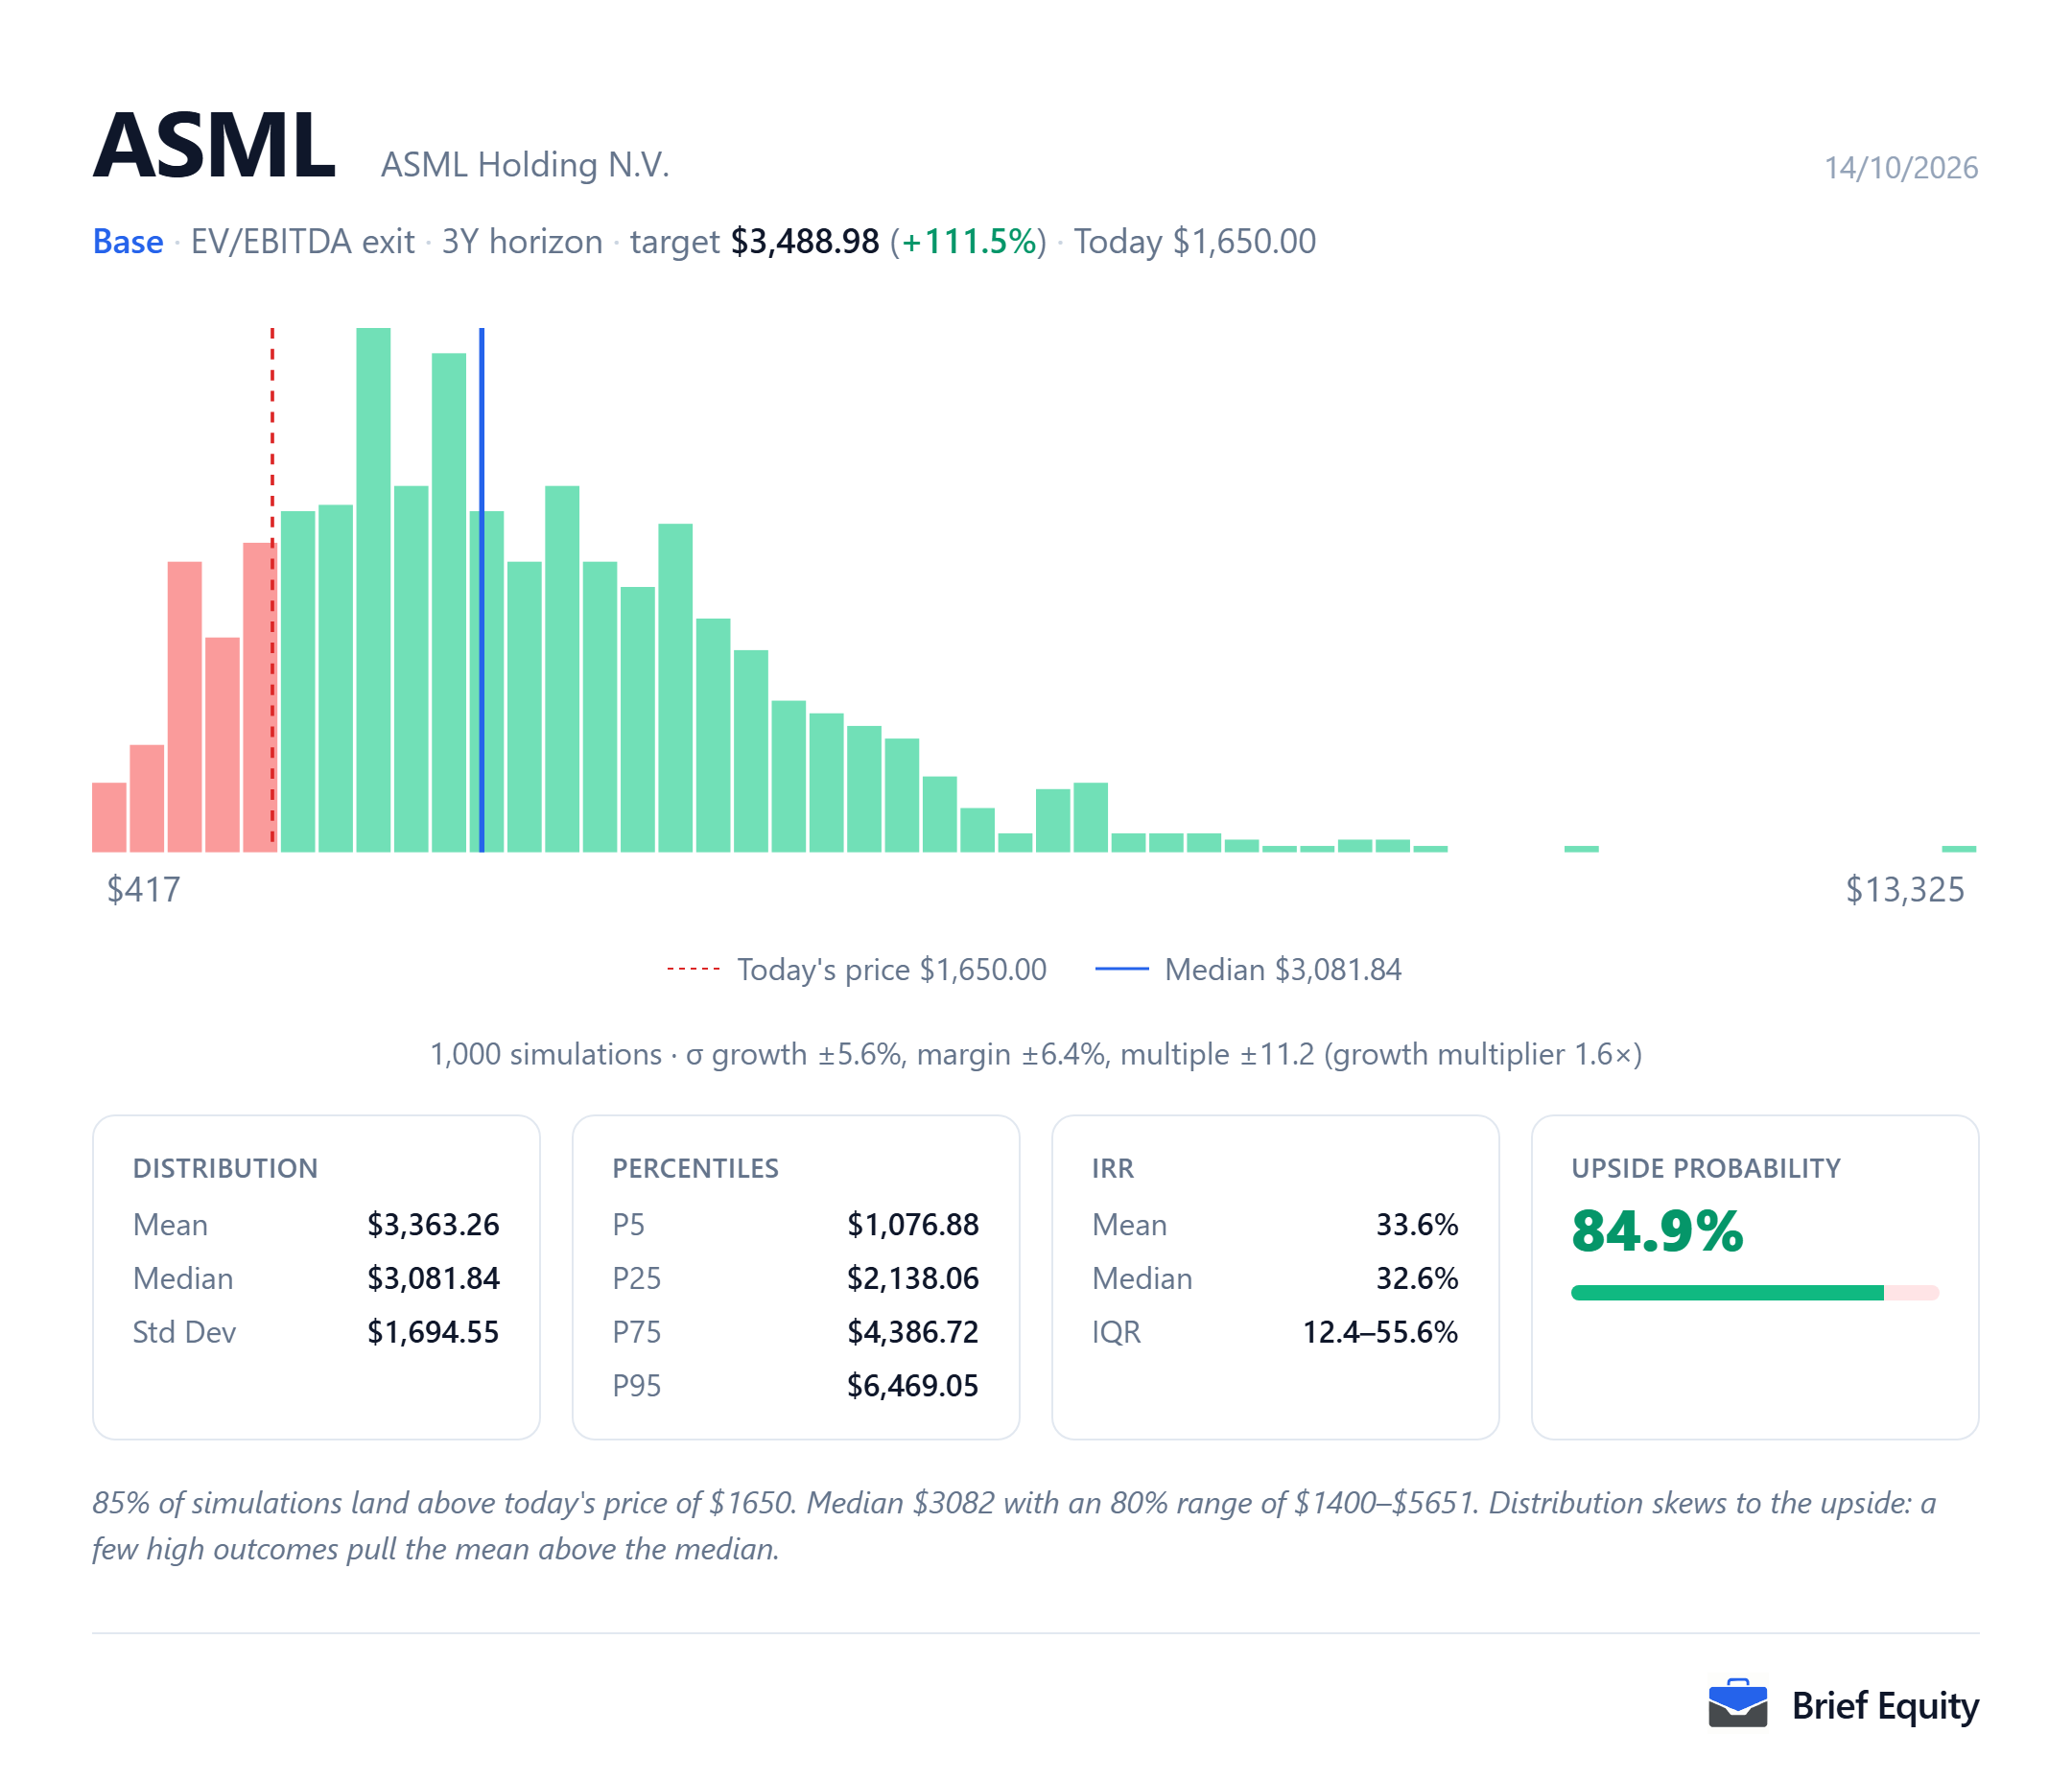
The two pictures below show how far the ASML estimate moves when its assumptions change: one moves two assumptions at a time, and the other runs the model many times with growth, margin and the exit multiple drawn at random.
Questions about ASML
These questions about ASML (ASML) are answered from the documents listed under Sources.
- What does ASML expect for 2026?
- In its third-quarter results of October 14, 2026, ASML said it expects 2026 total net sales between EUR 44 billion and EUR 45 billion, with a gross margin around 56%.
- Does ASML buy back its shares?
- In the third quarter of 2026, ASML bought back around EUR 4.1 billion worth of shares under its 2026 to 2028 share buyback program.
- How much of ASML's sales come from China?
- On its third-quarter call on October 14, 2026, ASML said it expects China to account for around 20% of its total net sales in 2026.
- How concentrated are ASML's customers?
- In 2025, ASML's largest customer accounted for 23.9% of its total net sales. Four customers each exceeded 10% of total net sales that year, together 61.2%.
Sources
The quotations and facts about ASML (ASML) on this page rest on the documents below.
- ASML third-quarter 2026 financial results press release, October 14, 2026
- ASML US GAAP financial statements for the third quarter of 2026, October 14, 2026
- ASML third-quarter 2026 earnings call, October 14, 2026
- ASML annual report (Form 20-F) for 2025, February 25, 2026
About this page
Brief Equity and its team hold no position in ASML (ASML) as of October 14, 2026.
This page is research, not investment advice. It describes one model and the assumptions behind it, and market data is delayed. Read how these models are built and our editorial policy.
Related guides: EV/EBITDA explained, How to value a stock yourself (without Excel), What is an analyst price target.