Valuation · EV/EBITDA model
Is Albany International (AIN) stock undervalued?
Brief Equity's EV/EBITDA model of Albany International, built on October 26, 2026 with the shares at $62.61, reaches a target of about $109 for 2028. On that model the stock looks undervalued, provided the amended CH-53K helicopter contract holds and Albany International adds the capacity to build more missile parts.
By The Brief Equity Team · Model dated · Published
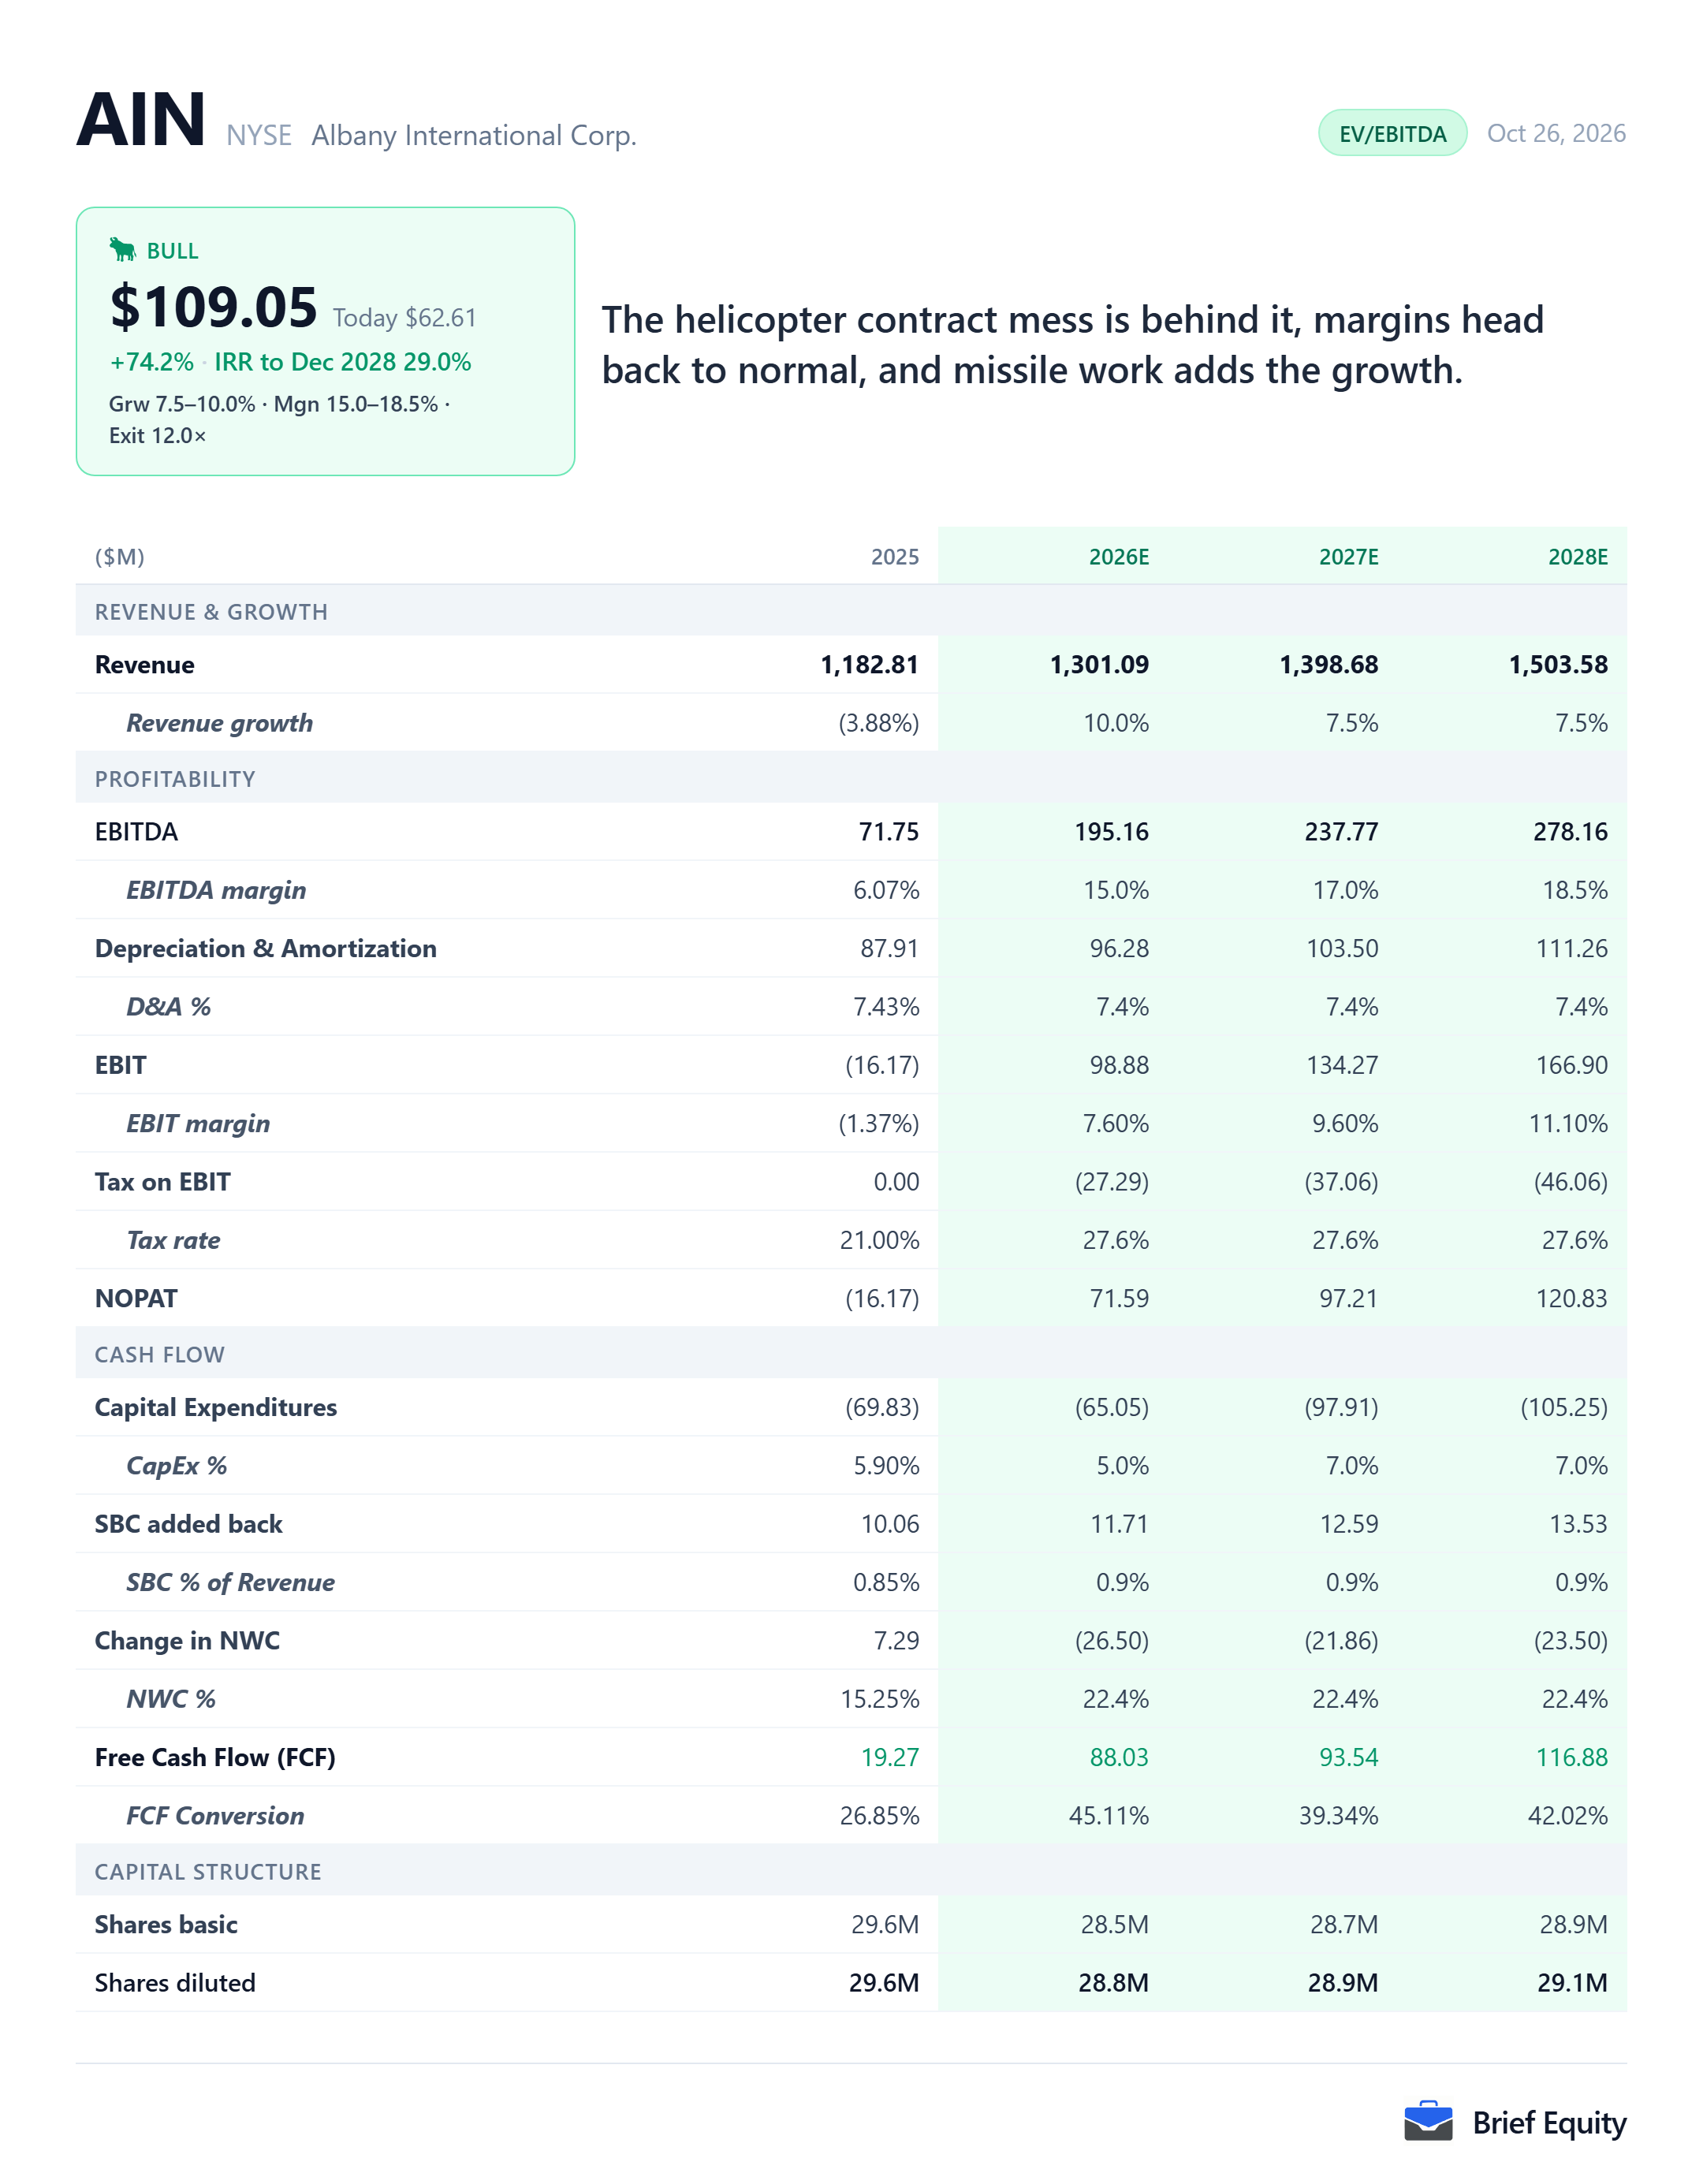
The model's assumptions for Albany International
Albany International is valued here with a quick model that projects 2026 to 2028 and applies 12 times EBITDA at the end of 2028. The first table holds the model's revenue and EBITDA, and the second sets its revenue beside the analyst consensus.
| 2026 | 2027 | 2028 | |
|---|---|---|---|
| Revenue, model | 1,301.09 | 1,398.68 | 1,503.58 |
| Revenue growth, model | 10.0% | 7.5% | 7.5% |
| EBITDA, model | 195.16 | 237.77 | 278.16 |
| EBITDA margin, model | 15.0% | 17.0% | 18.5% |
| 2026 | 2027 | 2028 | |
|---|---|---|---|
| Revenue, model | 1,301.09 | 1,398.68 | 1,503.58 |
| Revenue, analyst consensus | 1300.14 | 1381.85 | 1469.00 |
Why Albany International looks undervalued
Albany International’s share price fell 23.2% from October 23, 2023 to October 23, 2026, while the iShares U.S. Aerospace & Defense ETF (ITA) rose 89.3% over the same dates, both measured on price alone.
Albany International recorded a $155.9 million change in the estimated profitability of its CH-53K helicopter contracts in 2025, and its operating result went from income of $131.4 million in 2024 to a loss of $36.1 million. On September 1, 2026 it announced an amended CH-53K contract with Sikorsky, said it would keep the Salt Lake City facility it had been reviewing for a sale, and said it expects the contract modification to generate positive cash flow beginning in 2027.
Albany International’s adjusted EBITDA margin was 17.6% in the second quarter of 2026, and the adjusted EBITDA margin of its Engineered Composites segment rose to 13.3% from 8.5% a year earlier. The model takes the EBITDA margin from 15.0% in 2026 to 18.5% in 2028, with revenue growth of 10.0% in 2026 and 7.5% in each of 2027 and 2028, against analyst consensus of 6.3% for 2027 and for 2028. At 12 times EBITDA the model gives a target of about $109 for 2028, about 74% above the price on the model’s date.
Albany International makes missile bodies for Lockheed Martin’s JASSM missiles, and in September 2025 it received multiyear contracts extending its JASSM and LRASM work through 2029. On the first-quarter 2026 call its chief executive said the customer had asked for more output.
“For both JASSM and LRASM missiles, we have been requested by our customer to increase production, bringing output to the highest level achievable within our current capabilities, including through the use of overtime.”
Gunnar Kleveland, President and Chief Executive Officer, Albany International first-quarter 2026 earnings call, April 30, 2026
Albany International’s customer on those missiles, Lockheed Martin, was awarded a further $825.97 million contract modification for JASSM and LRASM by the US Air Force in September 2026, and the plans reported with it could support more than 1,000 of the two missiles a year, against 450 JASSMs and 115 LRASMs funded in the fiscal 2025 budget.
Albany International’s government work is still a small part of the whole: about 35% of Engineered Composites’ 2025 revenue related to U.S. government contracts or programs, and Engineered Composites was 40.1% of the company’s revenue.
What has to be true, and what would break it
Albany International's target rests on the CH-53K amendment holding, and on margins and missile capacity that keep rising.
What has to be true
- The amended CH-53K contract offsets the program’s projected losses and turns cash positive from 2027, as Albany International expects.
- The EBITDA margin rises from 15.0% in 2026 to 18.5% in 2028.
- Albany International adds the capacity to build more missile parts as JASSM and LRASM orders grow.
- Buyers pay 12 times EBITDA for the business at the end of 2028.
What would break it
- The CH-53K program keeps losing money after the amendment.
- Albany International cannot add missile capacity, so its output stays at what its current plants allow.
The parts of Albany International's business
Albany International has two parts: Machine Clothing, which makes belts and fabrics for paper machines, and Albany Engineered Composites, which makes aerospace and defense components. Revenue fell in 2025, so no share of growth is shown.
| Share of revenue | |
|---|---|
| Machine Clothing | 59.9% |
| Albany Engineered Composites | 40.1% |
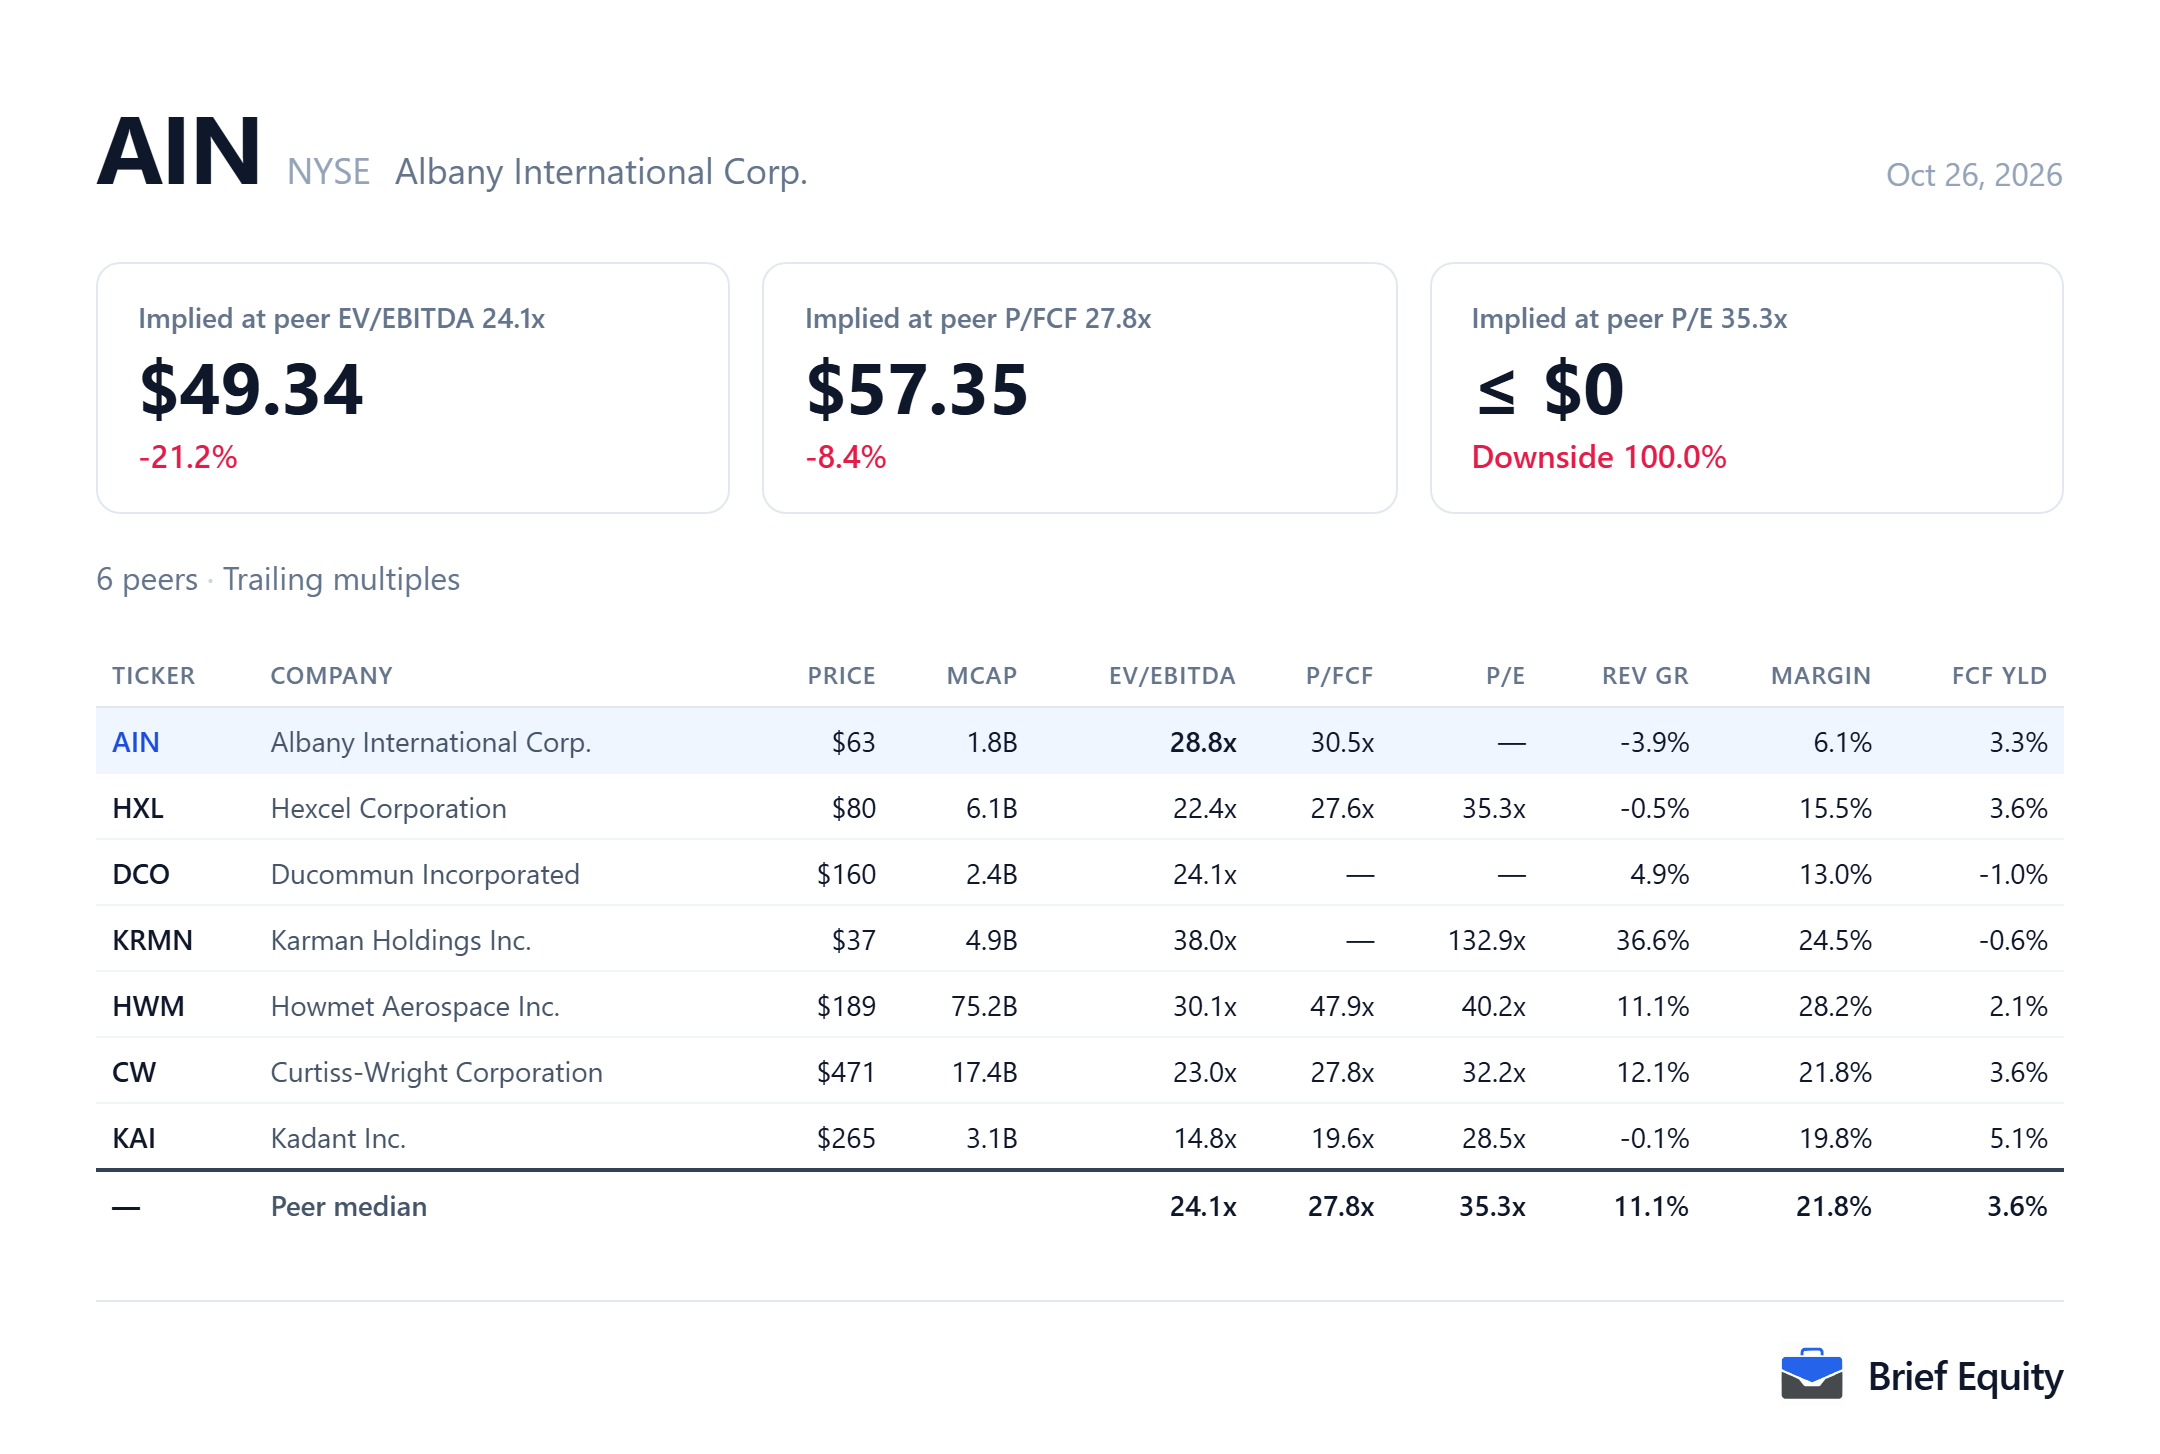
Albany International beside its peers
Albany International is compared here with six companies: four makers of aerospace and defense structures and components, one maker of engine parts, and one supplier to the paper industry.
- HXL: Aerospace composites, including the LEAP engine and the Boeing 787
- DCO: Aerostructures and missile structures for defense prime contractors
- KRMN: Missile and space structures
- CW: Defense components
- HWM: Engine parts, including the LEAP engine
- KAI: Equipment for the paper industry, beside Machine Clothing
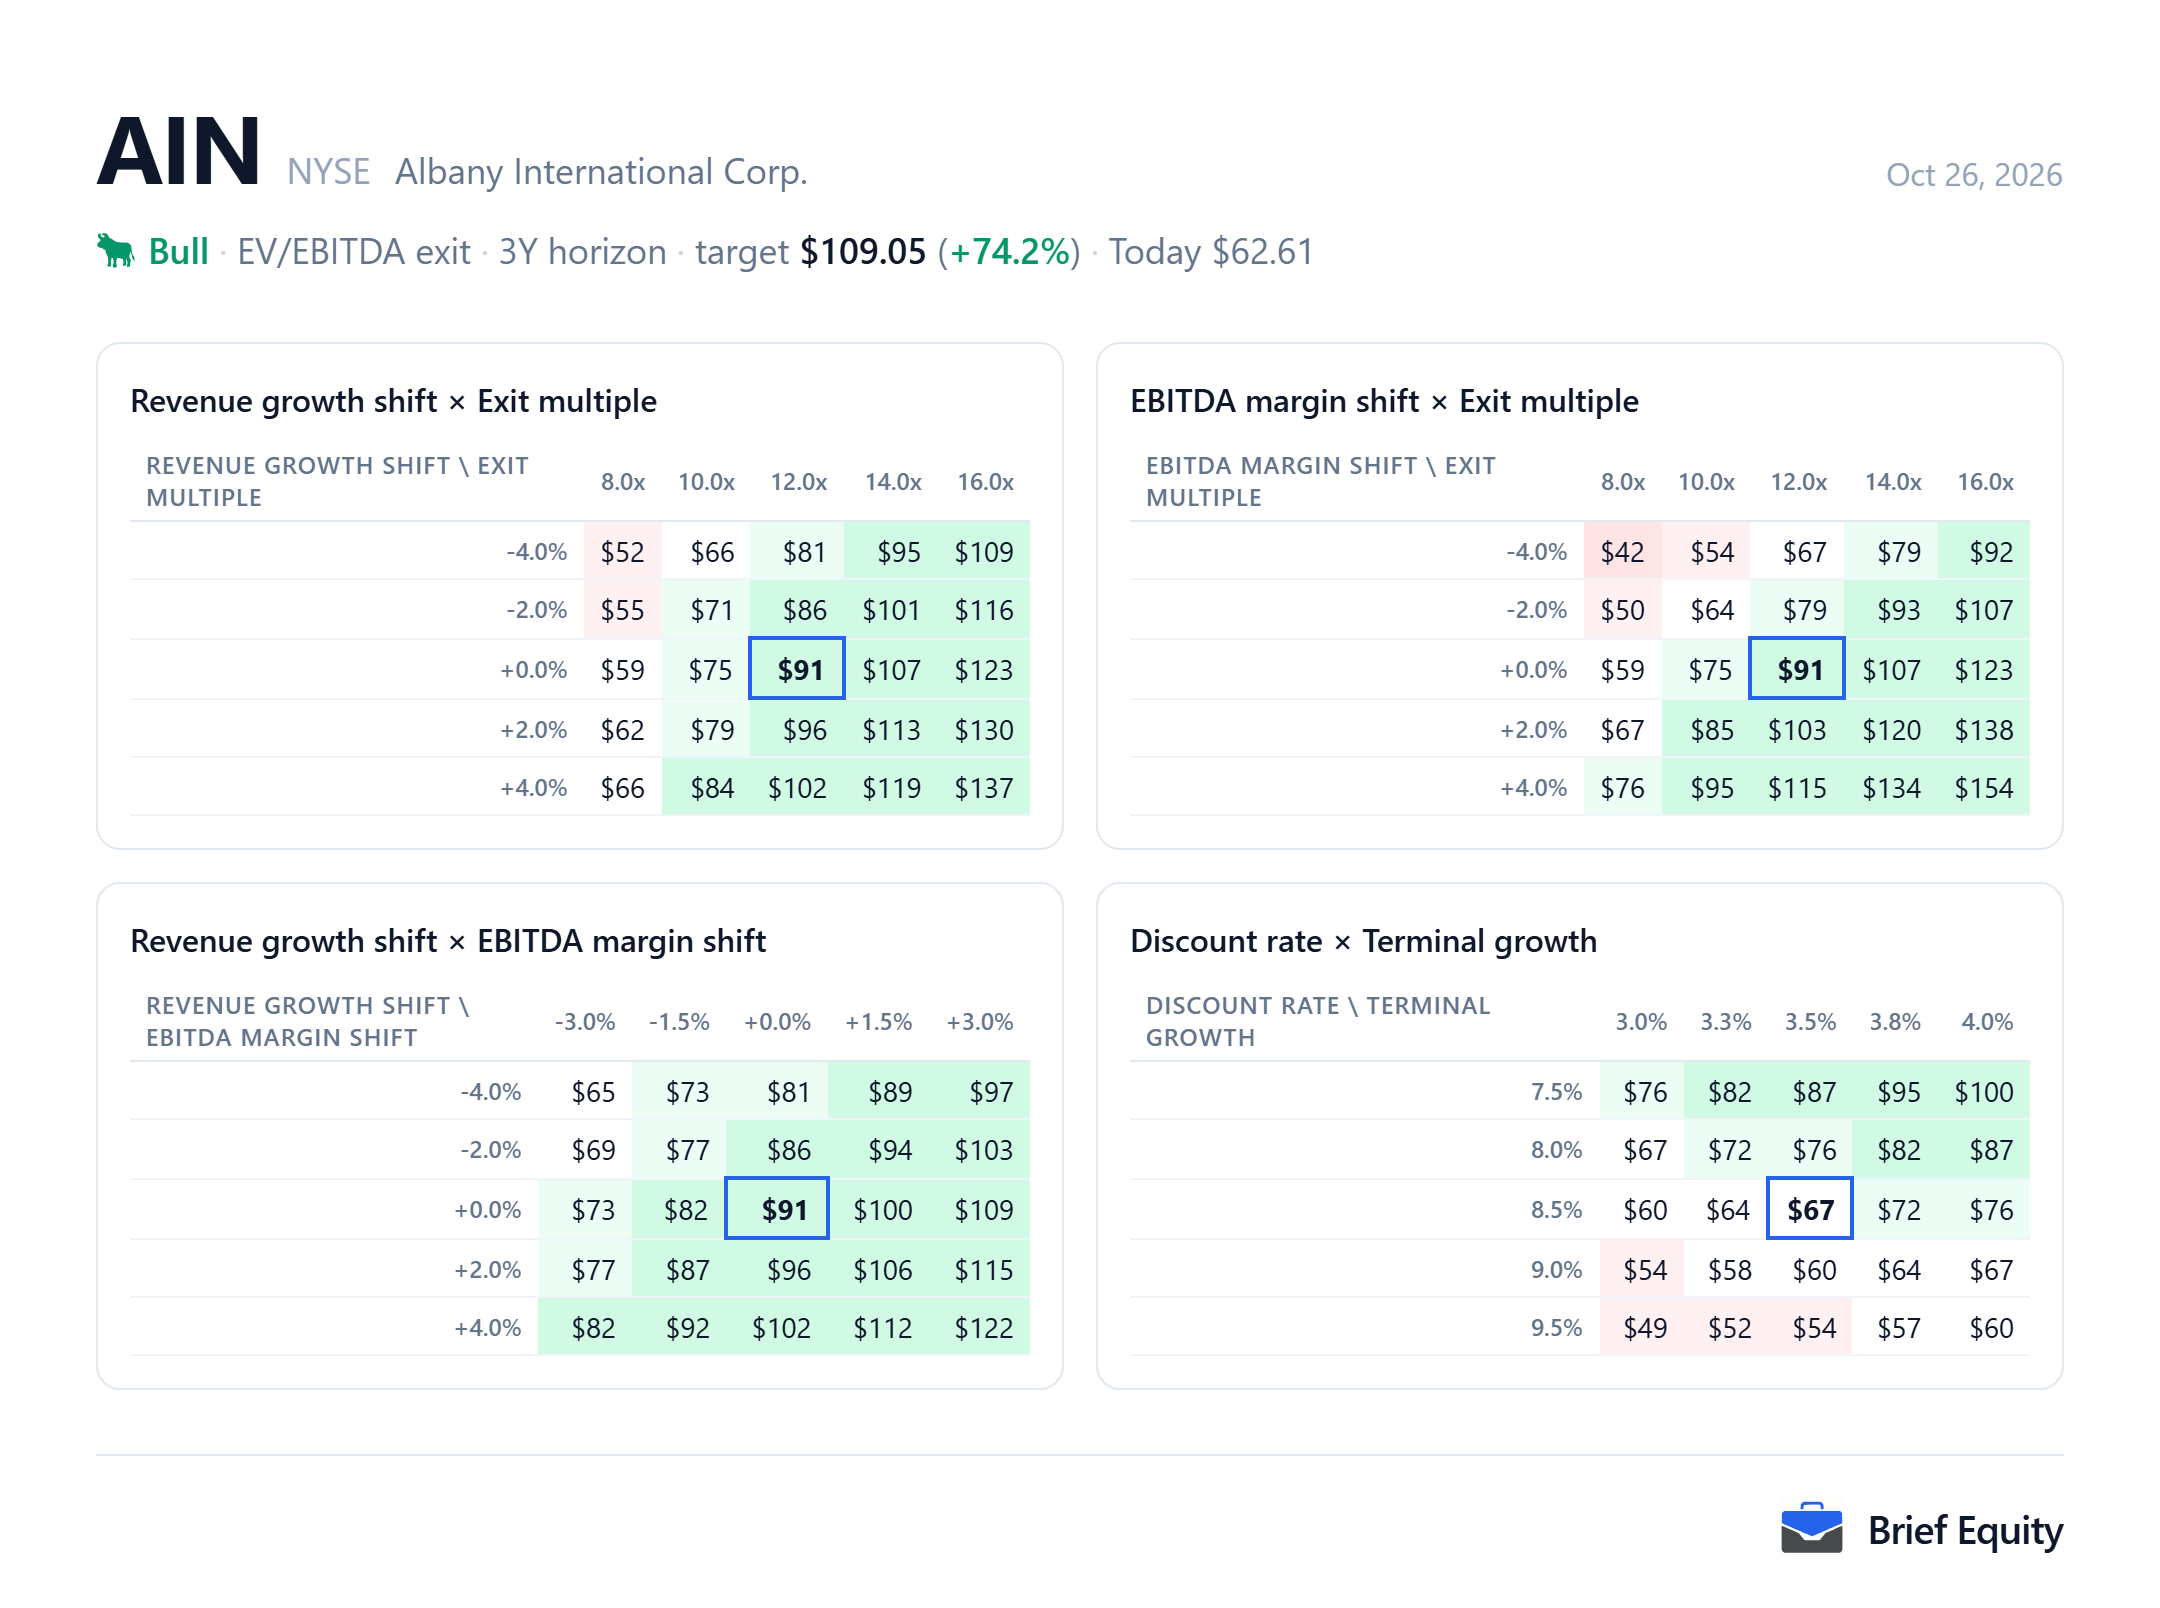
How the estimate moves with its assumptions
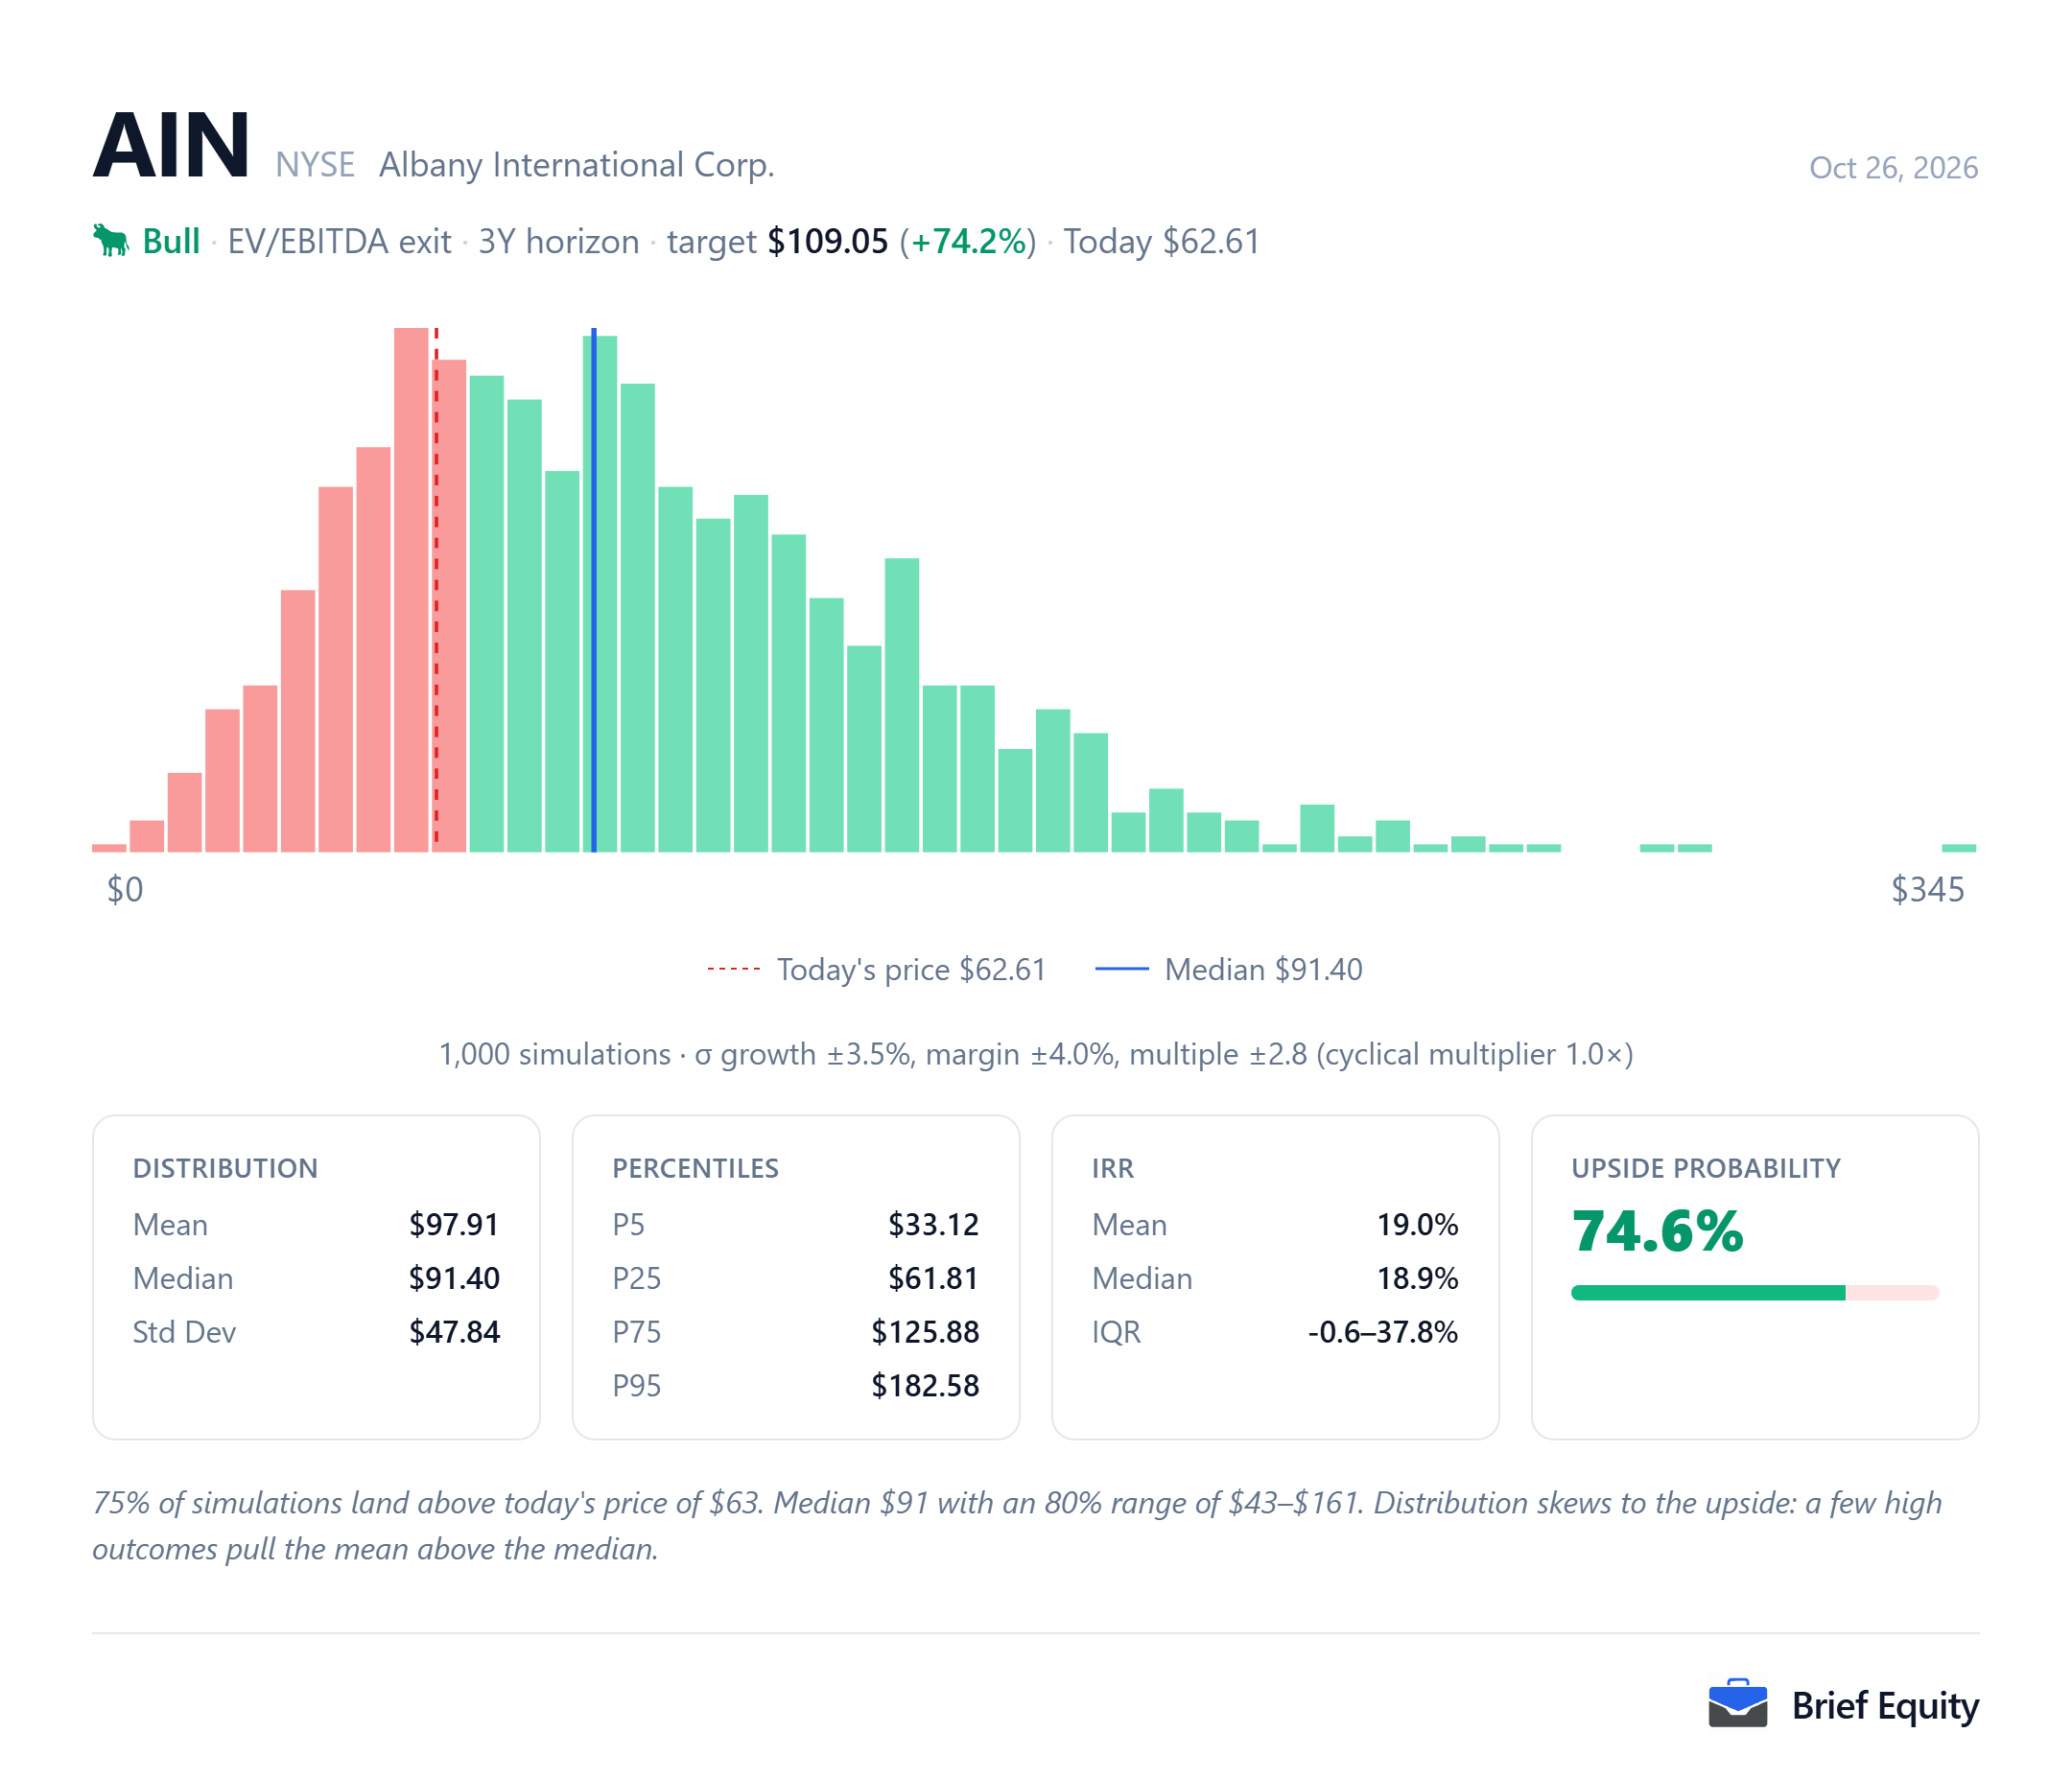
Albany International's estimate moves when its assumptions do, and the two pictures below show by how much. One changes two assumptions at a time, and the other runs the model many times with its main inputs drawn at random.
Questions about Albany International
These questions about Albany International (AIN) are answered from the documents listed under Sources.
- Who is Albany International's largest customer?
- Safran, mainly through fan blades and cases for the LEAP engine, accounted for approximately 15% of Albany International's consolidated net revenues in 2025.
- How large was the backlog of Albany Engineered Composites?
- Backlog at Albany Engineered Composites was $1.4 billion as of December 31, 2025.
- How much debt does Albany International carry?
- At June 30, 2026 Albany International had cash and cash equivalents of $77.3 million and total debt of $450.7 million, a net debt position of $373.3 million.
Sources
The quotations and facts about Albany International (AIN) on this page rest on the documents below.
- Albany International annual report (Form 10-K) for 2025, February 27, 2026
- Albany International second-quarter 2026 earnings release, August 4, 2026
- Albany International second-quarter 2026 earnings call, August 4, 2026
- Albany International first-quarter 2026 earnings call, April 30, 2026
- Albany International announces the completion of its strategic review, September 1, 2026
- Albany Engineered Composites extends JASSM and LRASM programs with Lockheed Martin through 2029, September 8, 2025
- The Defense Post on the September 2026 JASSM and LRASM contract modification, September 14, 2026
- Share price change for Albany International and the ITA exchange-traded fund, October 2023 to October 2026, October 26, 2026
- iShares U.S. Aerospace & Defense ETF fund page, October 26, 2026
About this page
Brief Equity and its team hold no position in Albany International (AIN) as of October 26, 2026.
This page is research, not investment advice. It describes one model and the assumptions behind it, and market data is delayed. Read how these models are built and our editorial policy.
Related guides: EV/EBITDA explained, What is enterprise value (EV).