Valuation · EV/EBITDA model
Is Akamai (AKAM) stock overvalued?
On November 8, 2026, with the shares at $83.09, a quick EV/EBITDA model by Brief Equity valued Akamai at about $57 for 2028, about 32% below the price. Akamai looks overvalued on that model, because most of its new cloud commitments come from one customer, Anthropic, at the lowest prices Akamai offers, and it spends heavily before that revenue arrives. The view holds unless Anthropic takes up its option to commit $9 billion more.
By The Brief Equity Team · Model dated · Published
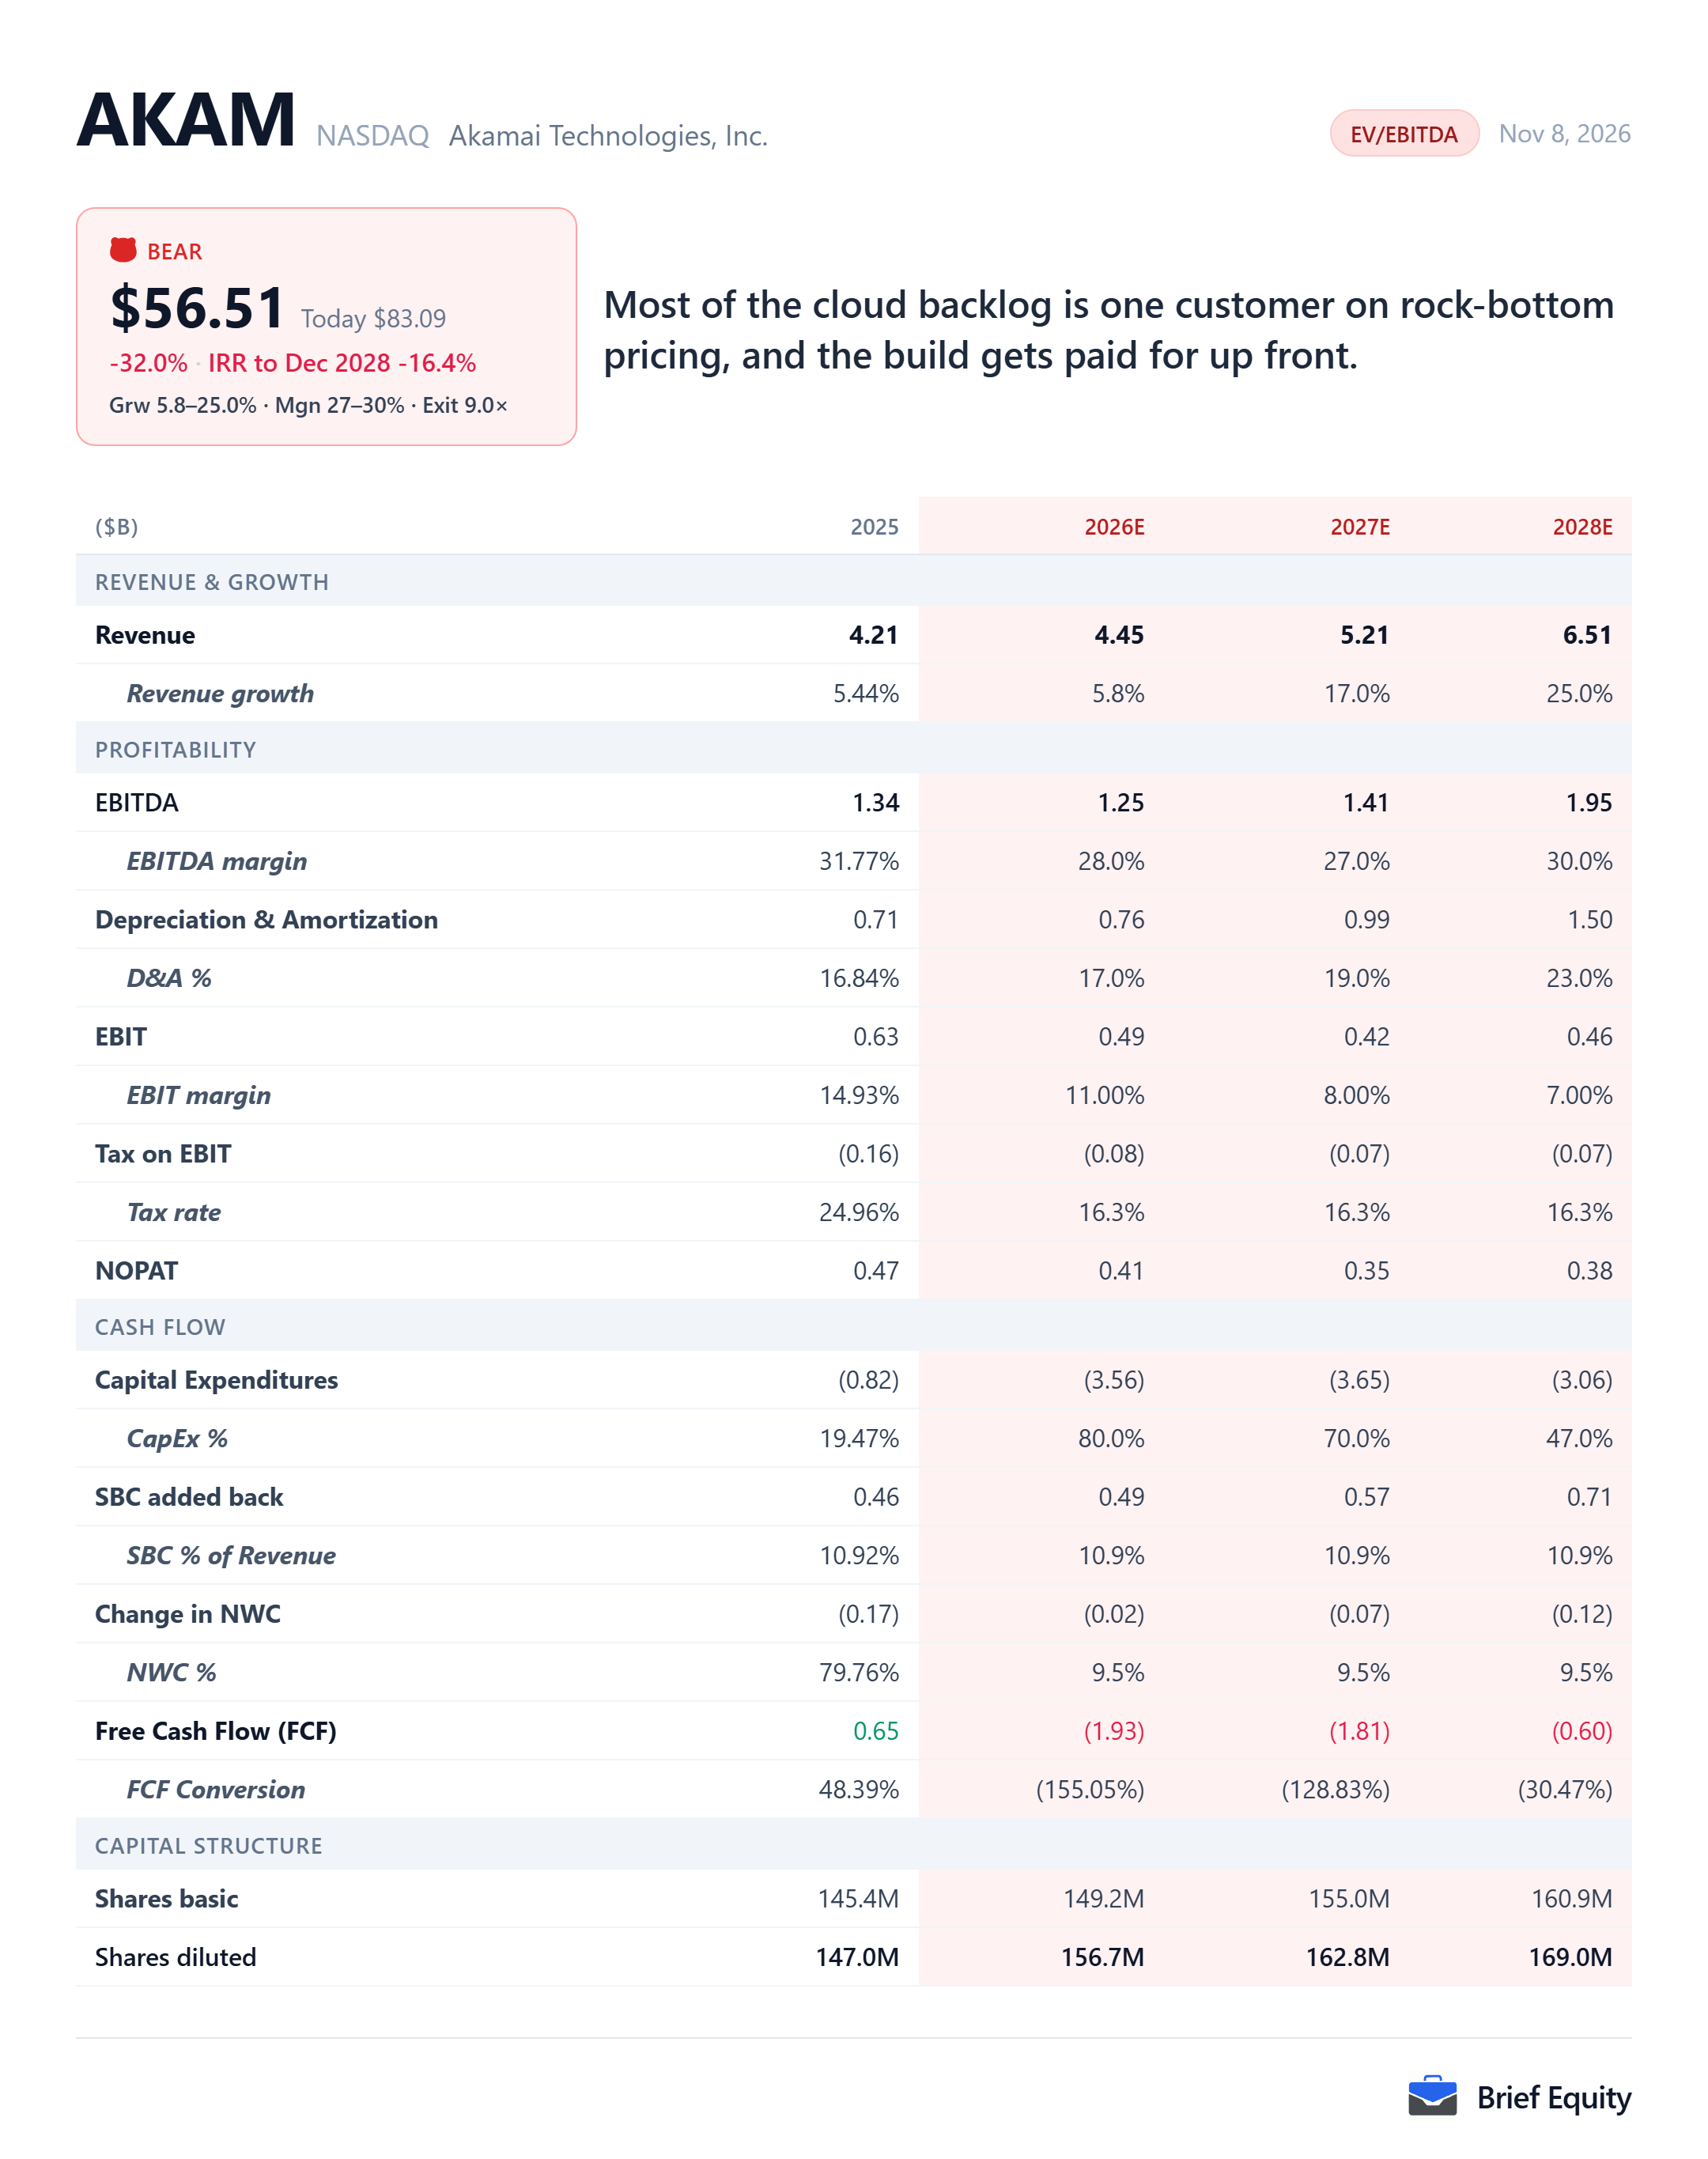
The model's assumptions for Akamai
Akamai's fiscal year is the calendar year, and the last year it has reported in full is 2025. The model runs three years, to 2028, and values the company on a multiple of its 2028 EBITDA. Every figure below is the model's own except the analysts' revenue, which is the consensus the model was built beside.
| 2026 | 2027 | 2028 | |
|---|---|---|---|
| Revenue, model | 4.45 | 5.21 | 6.51 |
| Revenue growth, model | 5.8% | 17.0% | 25.0% |
| EBITDA, model | 1.25 | 1.41 | 1.95 |
| EBITDA margin, model | 28.0% | 27.0% | 30.0% |
| Revenue, analysts' consensus | 4.49 | 5.22 | 6.47 |
Why Akamai looks overvalued
Akamai is turning into a provider of computing capacity that depends on one customer for most of its new cloud commitments, at the lowest prices it offers. The view here is that Akamai looks overvalued at $83.09, unless Anthropic takes up its option to commit $9 billion more, which Akamai's guidance for 2028 does not count.
In September 2026, Anthropic committed $11.6 billion over seven years to Akamai's cloud infrastructure services, most of the more than $14 billion of multiyear cloud commitments Akamai signed in 2026. Akamai's chief financial officer said these large deals carry the lowest prices it offers, and that Anthropic's carries the lowest return of them.
“So these are the lowest prices you're going to see on a unit economic basis.”
Ed McGowan, Akamai third-quarter 2026 earnings call, November 5, 2026
An analyst on Akamai's third-quarter call set its revenue per megawatt against other cloud providers:
“On our revenue per megawatt, it seems lower than a lot of the other Tier 2 hyperscalers and definitely in line with some of the older contracts of the neocloud.”
Paramveer Singh, Akamai third-quarter 2026 earnings call, November 5, 2026
Akamai expects to spend about $6.8 billion of capital on these contracts, beginning in the fourth quarter of 2026 and accelerating in 2027, before it recognizes the related revenue. It has paused share repurchases, had $7,640.0 million of convertible notes outstanding at September 30, 2026, and expects about $30 million of revenue to move from the fourth quarter of 2026 into 2027 because of supply chain and third-party data center delays.
For Akamai, the Brief Equity model is a quick one. It takes revenue to $6.51 billion in 2028, below the company's guidance of more than $7.0 billion, with an EBITDA margin of 27.0% to 30.0% and capital expenditure at 80.0% of revenue in 2026 and 70.0% in 2027. At 9 times 2028 EBITDA, that values Akamai at about $57 a share in 2028, about 32% below the price of $83.09.
What has to be true, and what would break it
The view that Akamai looks overvalued at $83.09 rests on its new cloud business staying concentrated on one low-priced customer while the spending comes first.
What has to be true
- Anthropic stays most of Akamai's new cloud commitments and does not take up its option to commit $9 billion more.
- Akamai's spending of about $6.8 billion on these contracts, beginning in the fourth quarter of 2026, comes ahead of the revenue.
- Akamai's revenue reaches about $6.51 billion in 2028, below its guidance of more than $7.0 billion.
- The market pays about 9 times EBITDA for Akamai in 2028.
What would break it
- Anthropic takes up its option to commit $9 billion more.
- Akamai signs more cloud contracts with other customers at higher prices than Anthropic's.
- The market pays a higher multiple of EBITDA for Akamai than 9 times.
The parts of Akamai's business
Akamai reports one segment and splits its revenue into three lines: security, delivery and other cloud applications, and cloud infrastructure services. Over the period below, delivery and other cloud applications shrank, so security and cloud infrastructure services carried the growth.
| Share of revenue | Share of revenue growth | |
|---|---|---|
| Security | 55.1% | 90.7% |
| Delivery and other cloud applications | 35.7% | |
| Cloud infrastructure services | 9.2% | 45.3% |
Akamai beside its peers
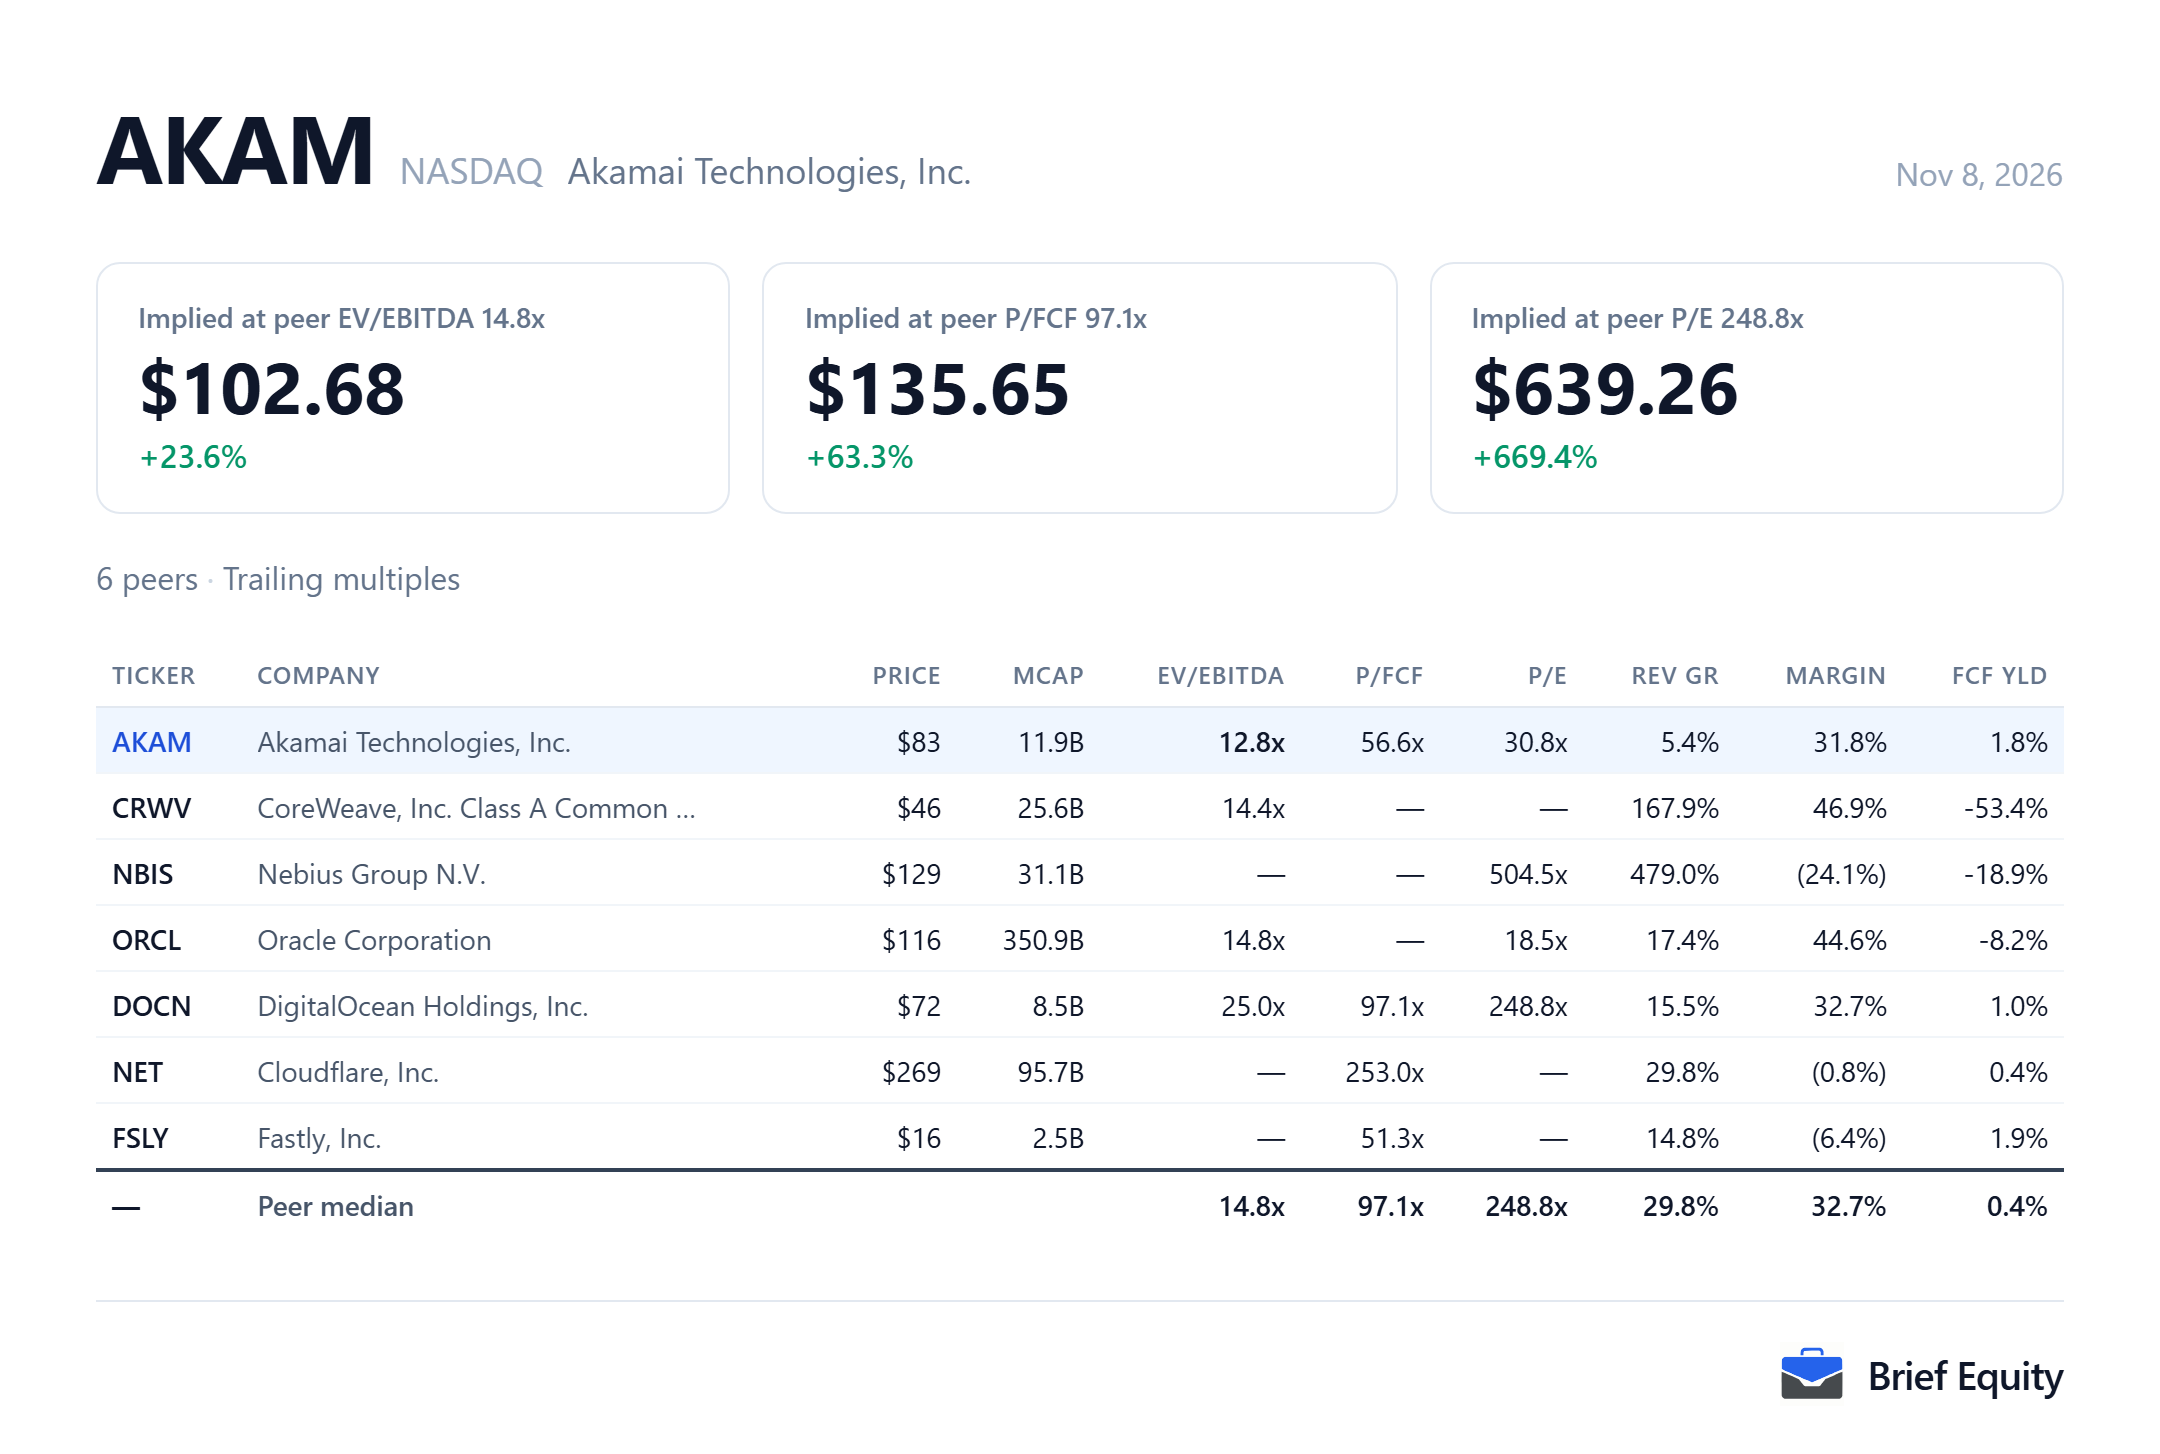
Akamai is compared here with six U.S.-listed companies chosen for this post: four that sell computing capacity and two that run networks like Akamai's own delivery and security business.
- CRWV: Computing capacity for AI companies
- NBIS: Computing capacity for AI companies
- ORCL: A large cloud provider below the three biggest
- DOCN: Computing capacity for smaller customers
- NET: Edge network and security
- FSLY: Content delivery
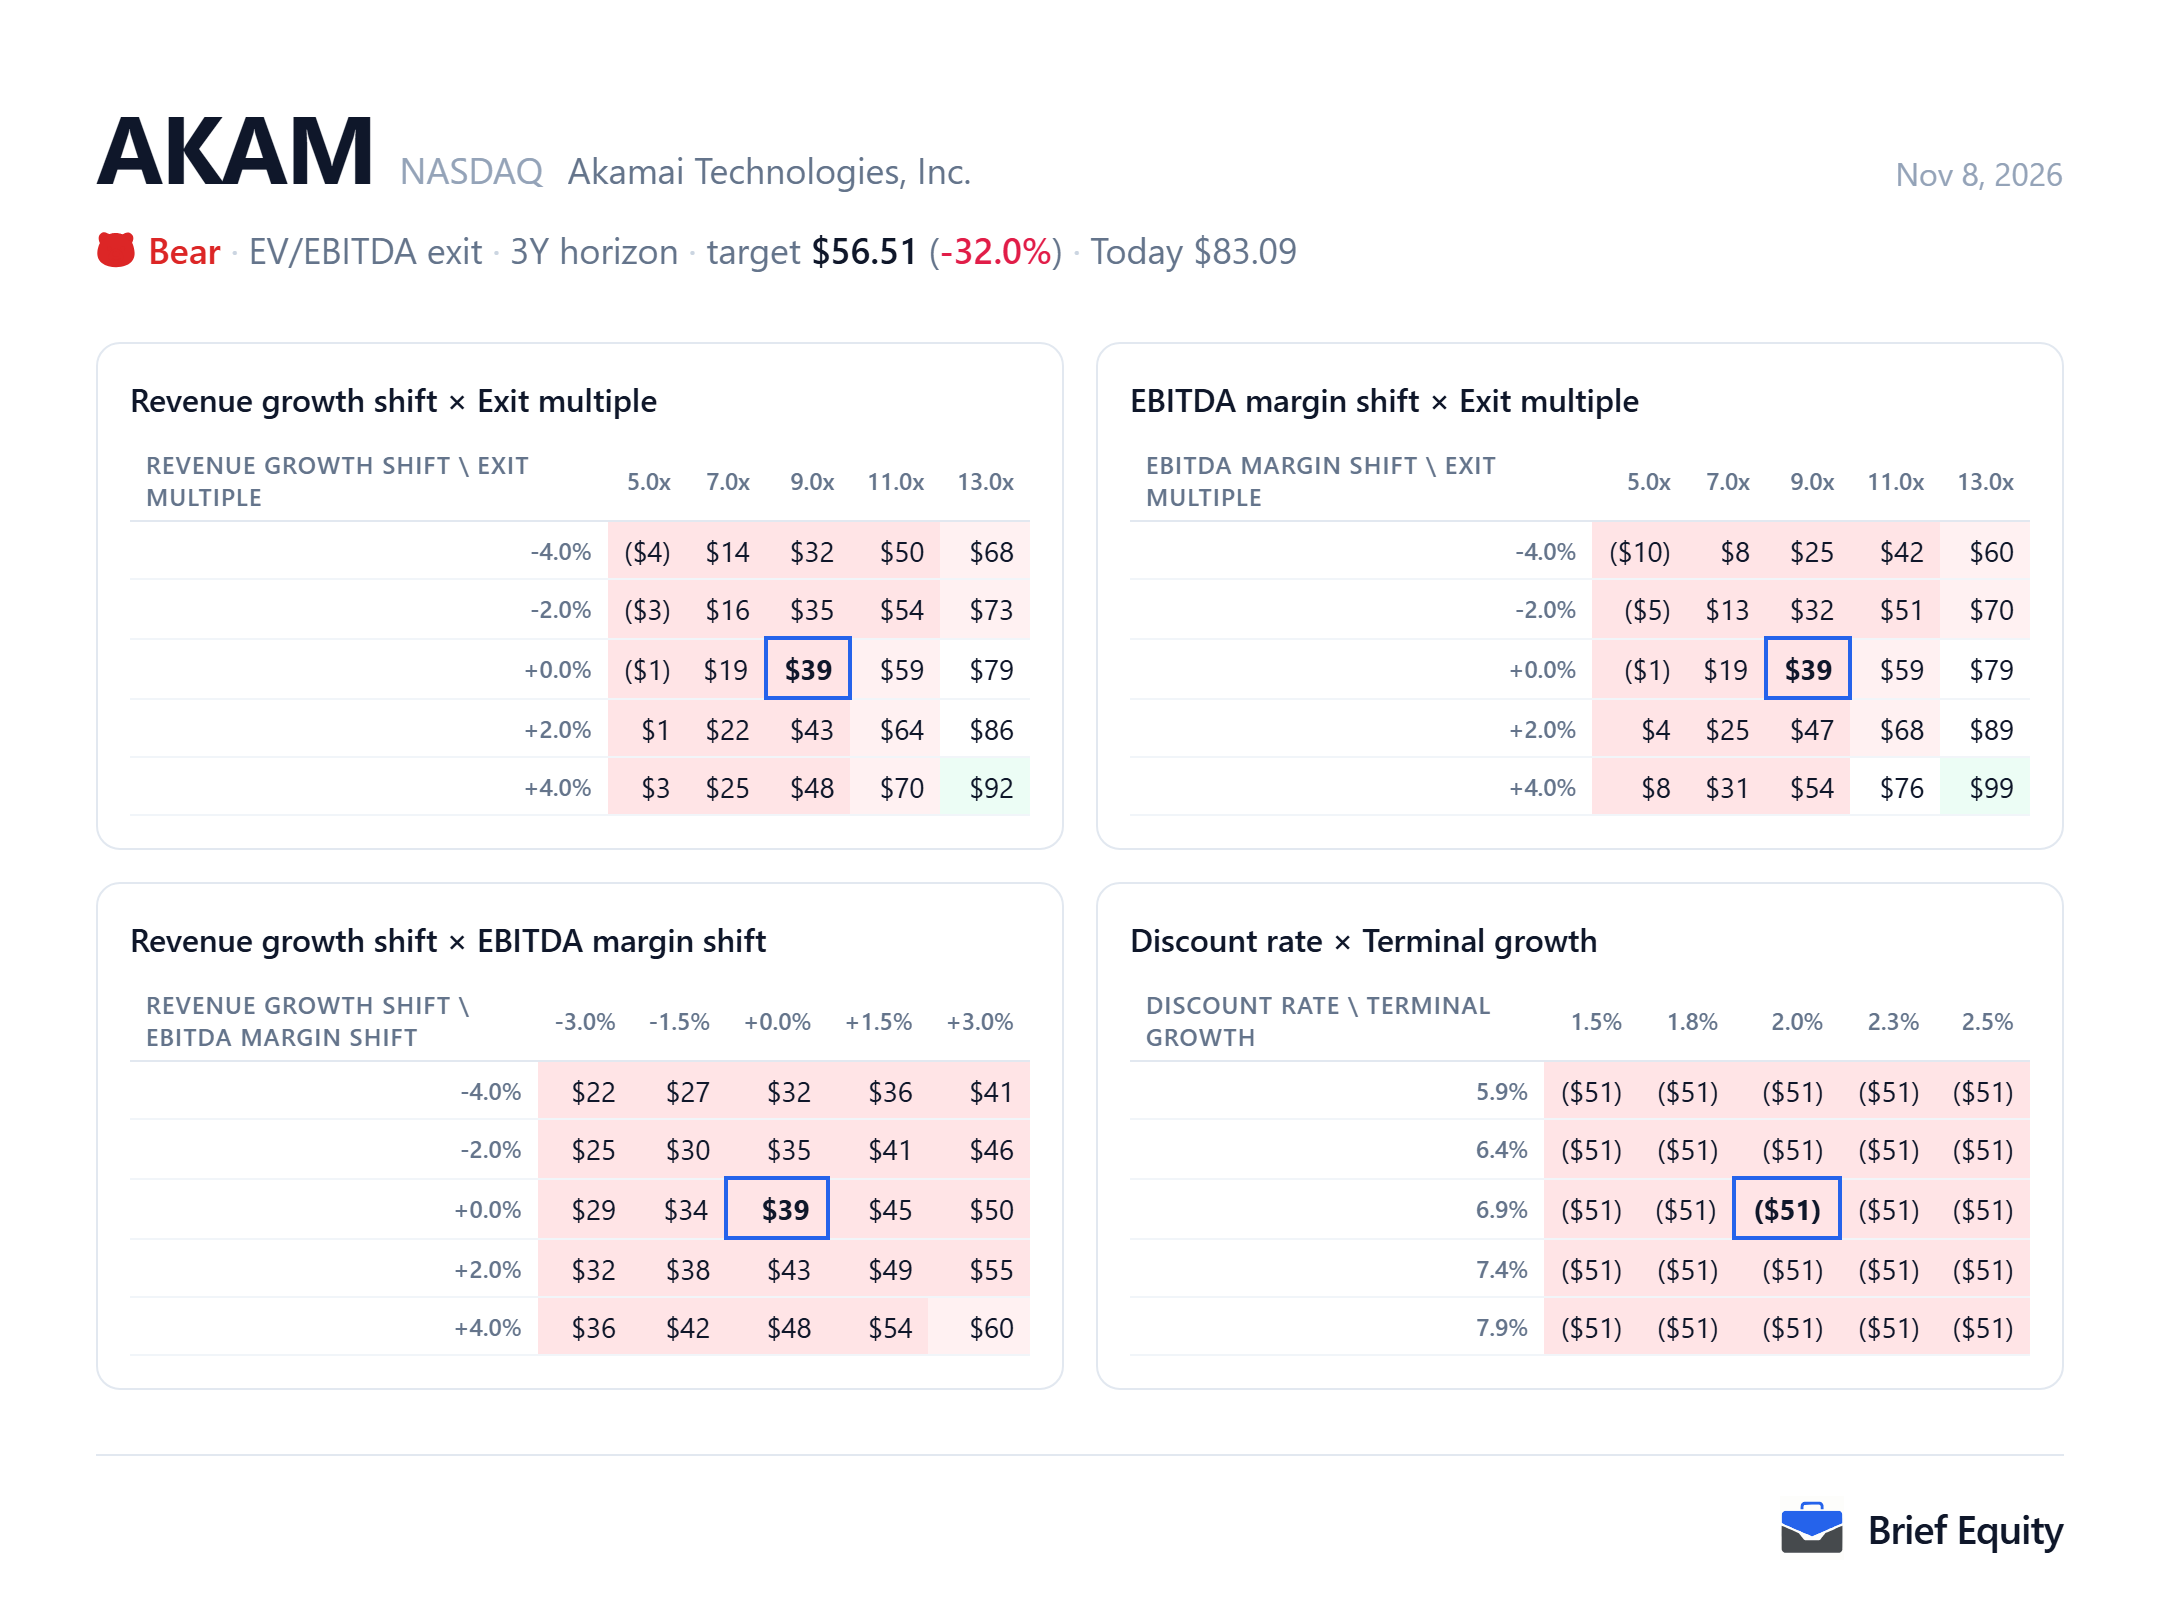
How the estimate moves with its assumptions
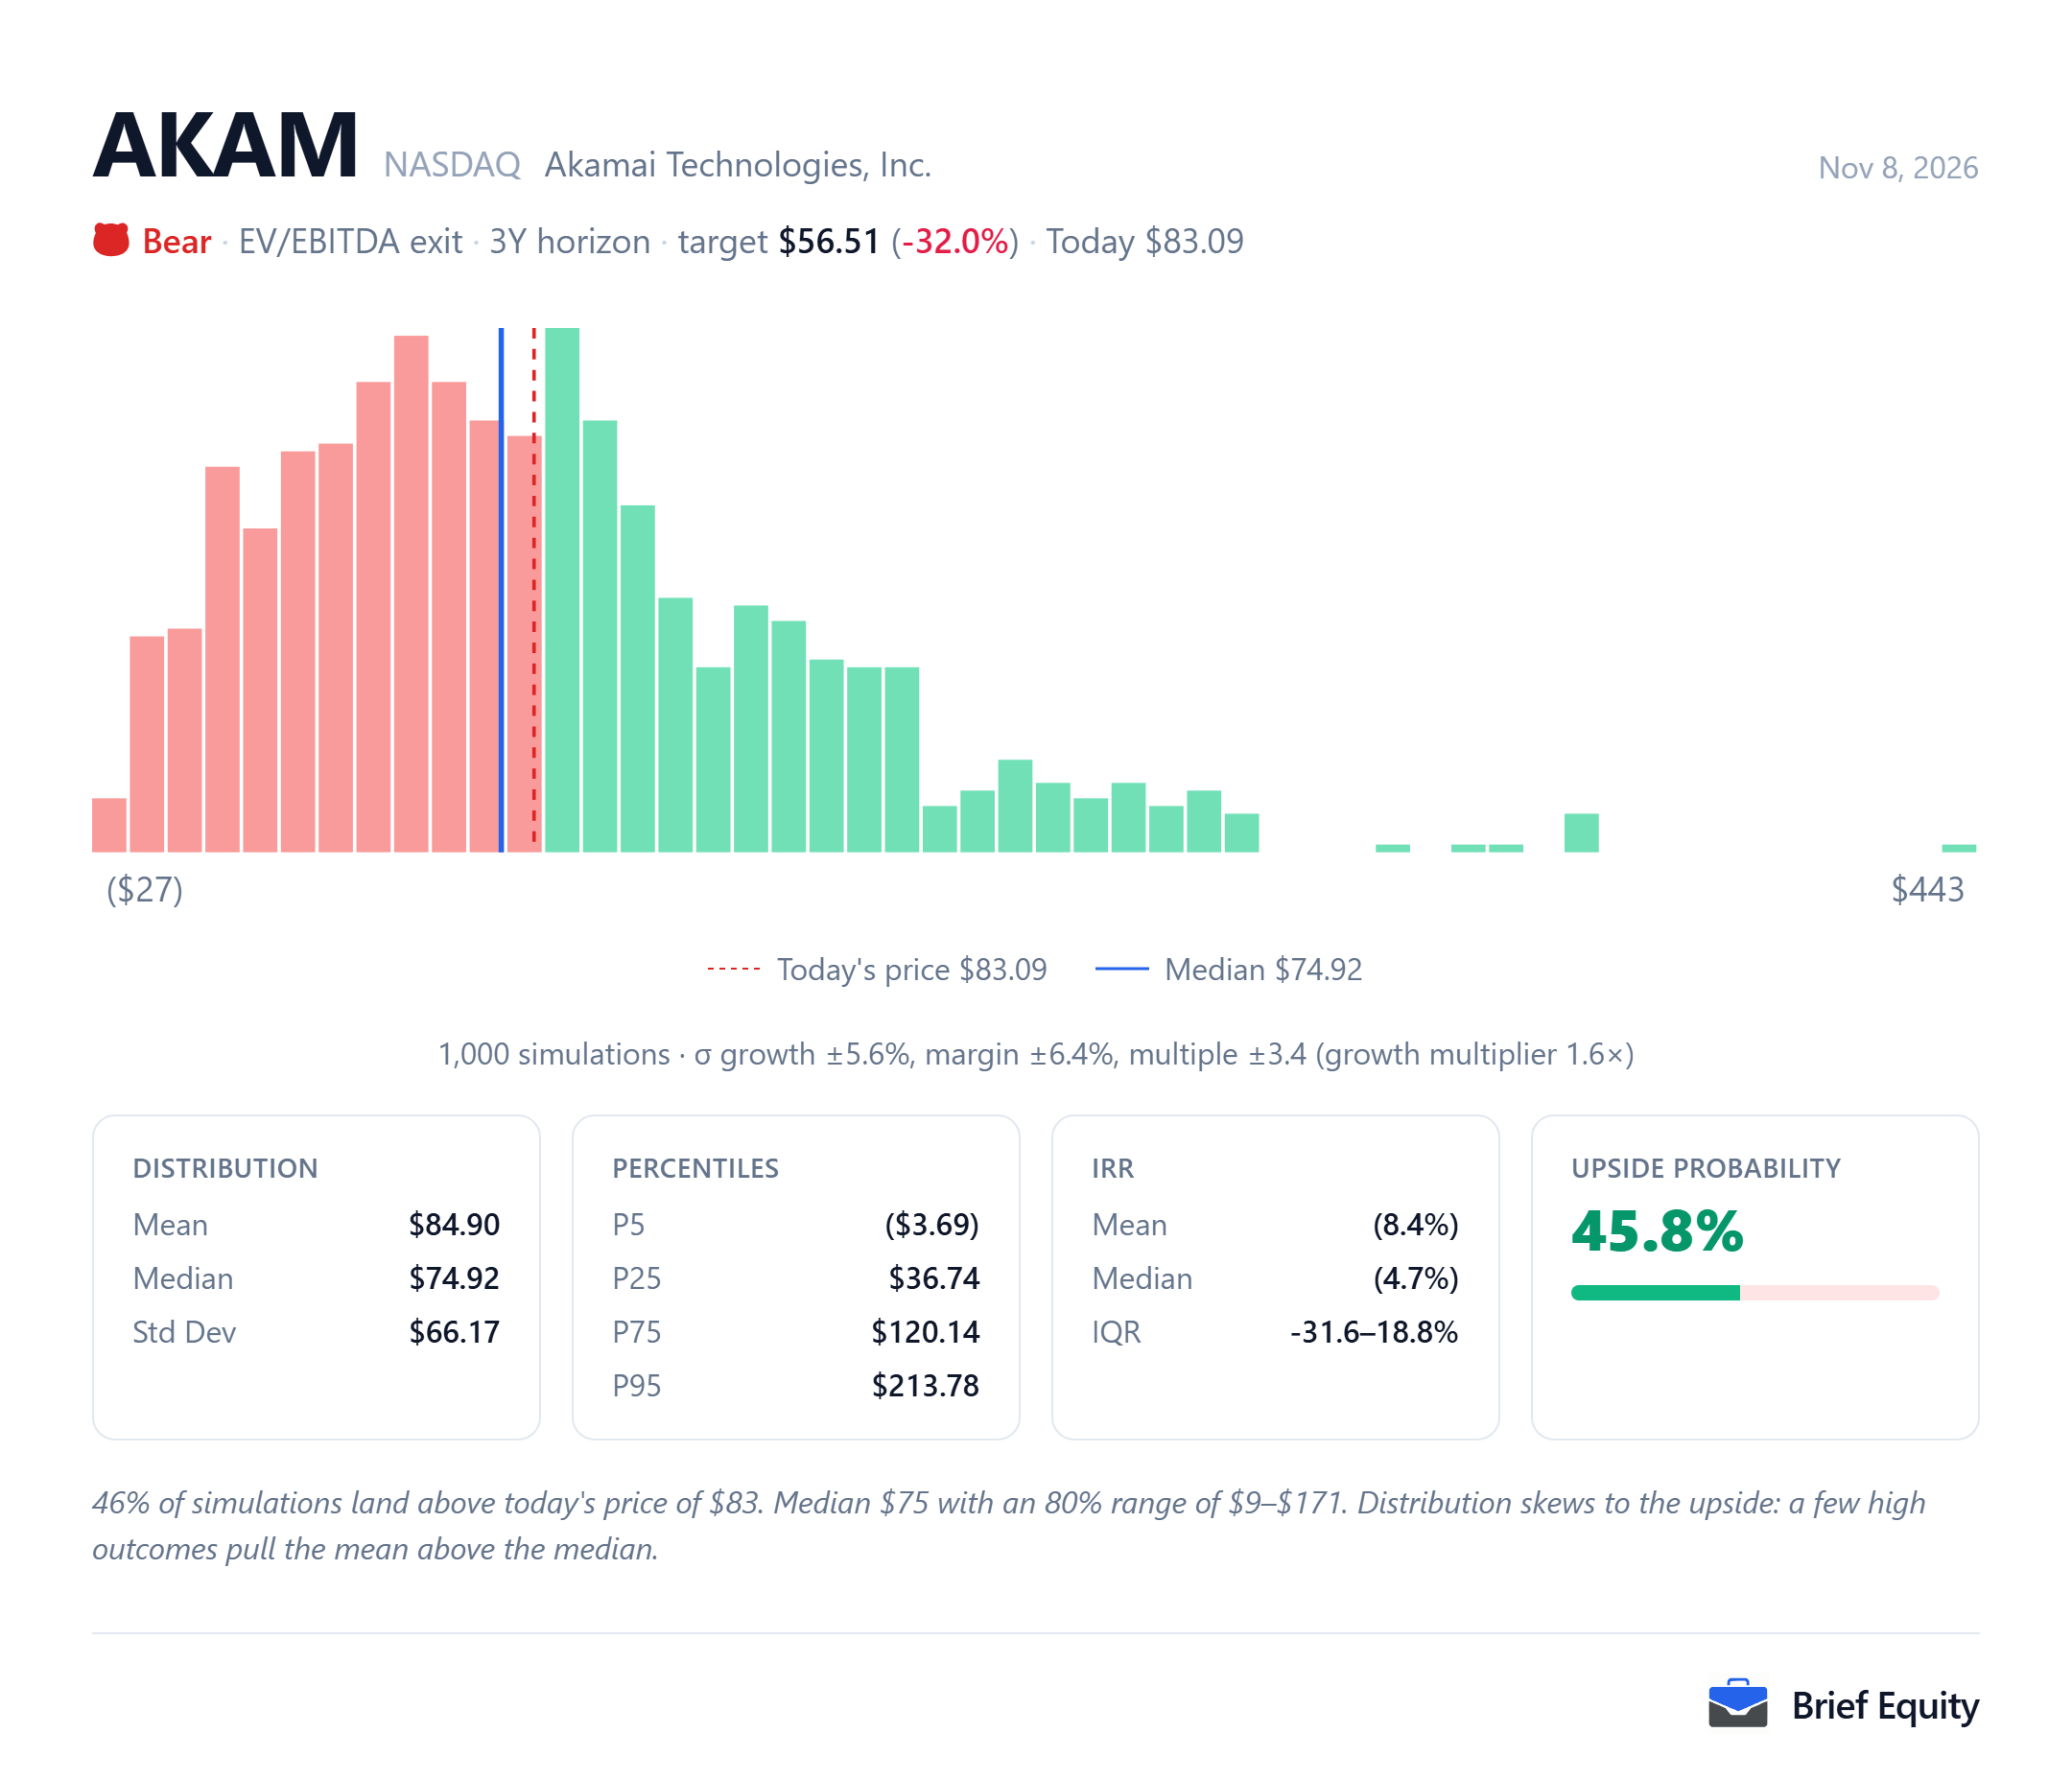
The two Akamai cards below test the estimate: the sensitivity grids move two assumptions at a time, and the Monte Carlo card reruns the model many times with growth, margin and the exit multiple drawn at random.
Questions about Akamai
These questions about Akamai (AKAM) are answered from the documents listed under Sources.
- What revenue does Akamai expect for 2027 and 2028?
- On November 5, 2026, Akamai projected 2027 revenue growth of 17% to 22% when adjusted for foreign exchange, and 2028 revenue of more than $7.0 billion.
- How much contracted revenue does Akamai have?
- Akamai's remaining performance obligations were $19.9 billion at September 30, 2026, against $5.2 billion at December 31, 2025. It expects to recognize about 35% of the September figure as revenue over the following two years.
- When does Akamai's next convertible note mature?
- As of September 30, 2026, Akamai's nearest maturity was its 2027 convertible notes, $1,150.0 million of principal due September 1, 2027.
Sources
The quotations and facts about Akamai (AKAM) on this page rest on the documents below.
- Akamai quarterly report on Form 10-Q for the third quarter of 2026, November 6, 2026
- Akamai third-quarter 2026 results release, November 5, 2026
- Akamai third-quarter 2026 earnings call, November 5, 2026
About this page
Brief Equity and its team hold no position in Akamai (AKAM) as of November 8, 2026.
This page is research, not investment advice. It describes one model and the assumptions behind it, and market data is delayed. Read how these models are built and our editorial policy.
Related guides: How to read a 10-K (SEC filing), How to research a stock before you buy, Where to read earnings transcripts and filings in one place.